


UL Solutions (ULS) just expanded its HVACR Center of Excellence in Plano, Texas, adding capacity to test energy efficient refrigerants and AI driven data center cooling systems for manufacturers targeting North American and global markets.
Investors have seen mixed momentum in UL Solutions this year, with the share price slipping around 19% over the past 90 days and the year to date share price return down roughly 12%. Meanwhile, the 1 year total shareholder return has declined about 8% despite product launches, leadership changes and the Plano HVACR expansion drawing fresh attention to the business.
Scan other testing and data center cooling plays moving on similar themes with the curated 92 AI infrastructure stocks that filters for companies exposed to the build out of computing and power capacity.
UL Solutions now has fresh HVACR capacity, a new AI focused executive and a stock that has slid double digits this year. Is a solid testing franchise being offered at a fair price or a value trap in the making?
Most Popular Narrative: 28% Undervalued
UL Solutions closed at $71.08, while the most followed narrative pegs fair value around $98.23. The gap between price and modeled worth is wide and is tied directly to how durable the testing franchise and margin profile prove to be over time.
The analysts have a consensus price target of $98.23 for UL Solutions based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $120.0, and the most bearish reporting a price target of just $79.0.
See why 5 investors see UL Solutions as 28% undervalued.
Result: Fair Value of $98.23 (UNDERVALUED)
Still, analyst models rely on assumptions that UL Solutions can sustain high P/E multiples and absorb higher tax rates; both could be challenged if execution or policy changes.
Find out about the key risks to this UL Solutions narrative.
Another View: UL Solutions Looks Expensive On Earnings
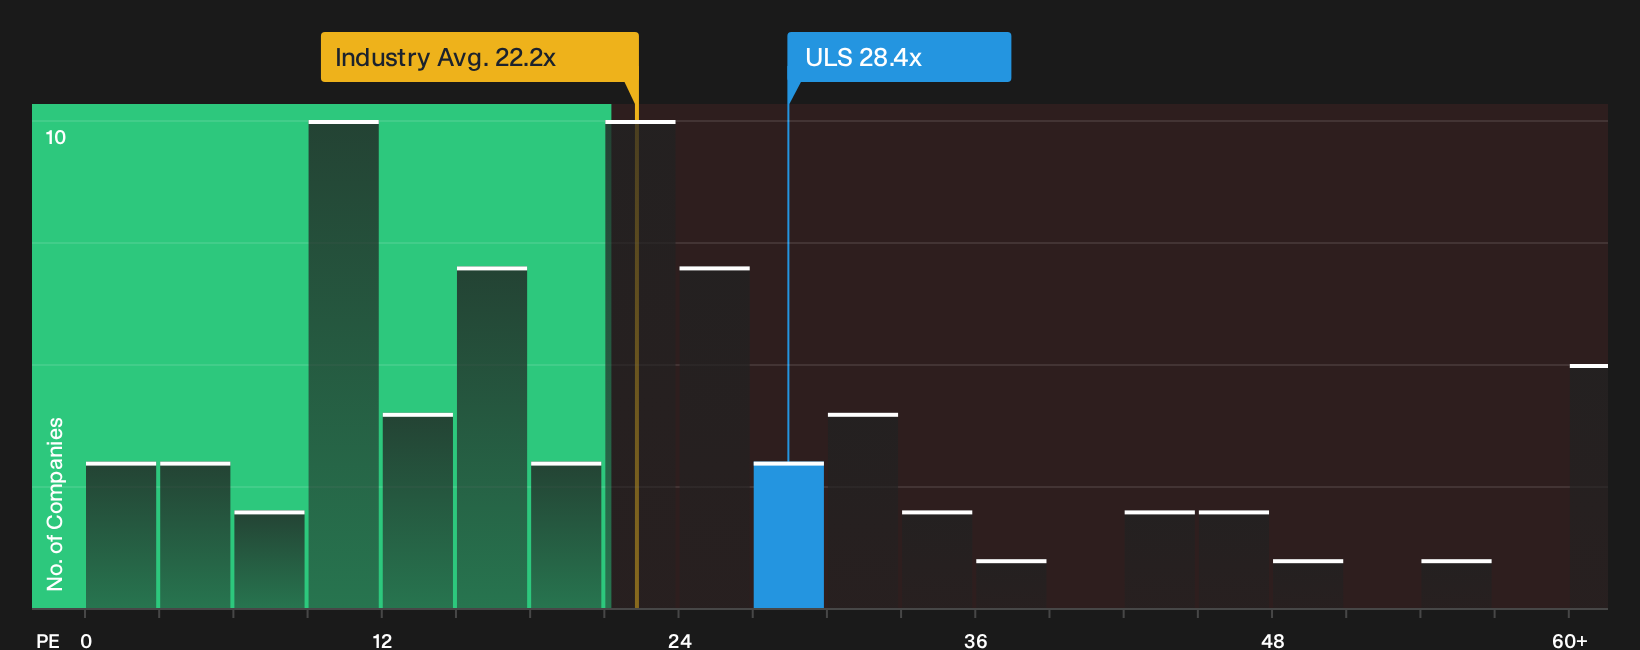
On the flip side of that fair value narrative, UL Solutions trades on a P/E of 28.4x, while the US Professional Services group sits nearer 22.3x and the peer average is about 25x. The fair ratio sits lower again at 16x, which points to valuation risk if sentiment cools.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on UL Solutions is split, and the time to pressure test the story is when opinions are this far apart. Move quickly; weigh both the potential upside and the red flags; then ground your own stance in the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond UL Solutions?
If UL Solutions has you thinking harder about valuation and risk, do not stop here. Use the Simply Wall Street Screener to line up fresh, data driven opportunities.
- Target quality at a discount by scanning the 32 high quality undervalued stocks that filters for strong fundamentals paired with prices that still trail underlying business strength.
- Prioritize resilience over thrills and check the 32 resilient stocks with low risk scores to focus on companies with steadier risk profiles and fewer unpleasant financial surprises.
- Hunt for future leaders before the crowd arrives by reviewing the 20 high quality undiscovered gems that highlights under the radar businesses with solid numbers and room to grow.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com