


Recent coverage placing Shiseido Company (TSE:4911) at the forefront of the expanding biosignal serums market, together with profit gains tied to cost cuts, has pushed the stock back onto investors’ radar.
That renewed interest is turning up in the chart. Shiseido Company’s share price is up 45.31% year to date, with a 10.98% 90 day share price return hinting at building momentum, although the 5 year total shareholder return is still down 51.87%.
Scan beyond Shiseido Company and compare this move in biosignal serums with a hand-picked short list of resilient skincare and beauty stocks, screened for balance-sheet strength and fundamentals using our list of solid balance sheet and fundamentals (21 results).
After a 45% year to date surge and long term returns still deeply underwater, Shiseido Company now forces a choice: lean into the rebound at today’s price, or wait and let the valuation do the talking next.
Most Popular Narrative: 29% Overvalued
On the most followed view of Shiseido Company, the current share price of ¥3,356 sits well above an implied fair value of ¥2,596. This puts the recent rally in contrast with a more cautious long term earnings story.
Structural reforms and aggressive cost reduction measures have been the primary drivers behind recent profit improvements, rather than underlying sales growth. As top-line remains flattish and key regions such as Japan, Americas, and Travel Retail continue to show weakness, the sustainability of net margins is extremely vulnerable if cost savings plateau, posing significant downside risk to long-term profitability.
See why 0 investors see Shiseido Company as 29% overvalued.
Result: Fair Value of ¥2,596 (OVERVALUED)
Still, if Shiseido Company converts ongoing cost reforms into lasting margin gains and reignites key brands in China and travel retail, this bearish script could become fragile.
Find out about the key risks to this Shiseido Company narrative.
Another View: Shiseido Company Through Sales-Based Ratios
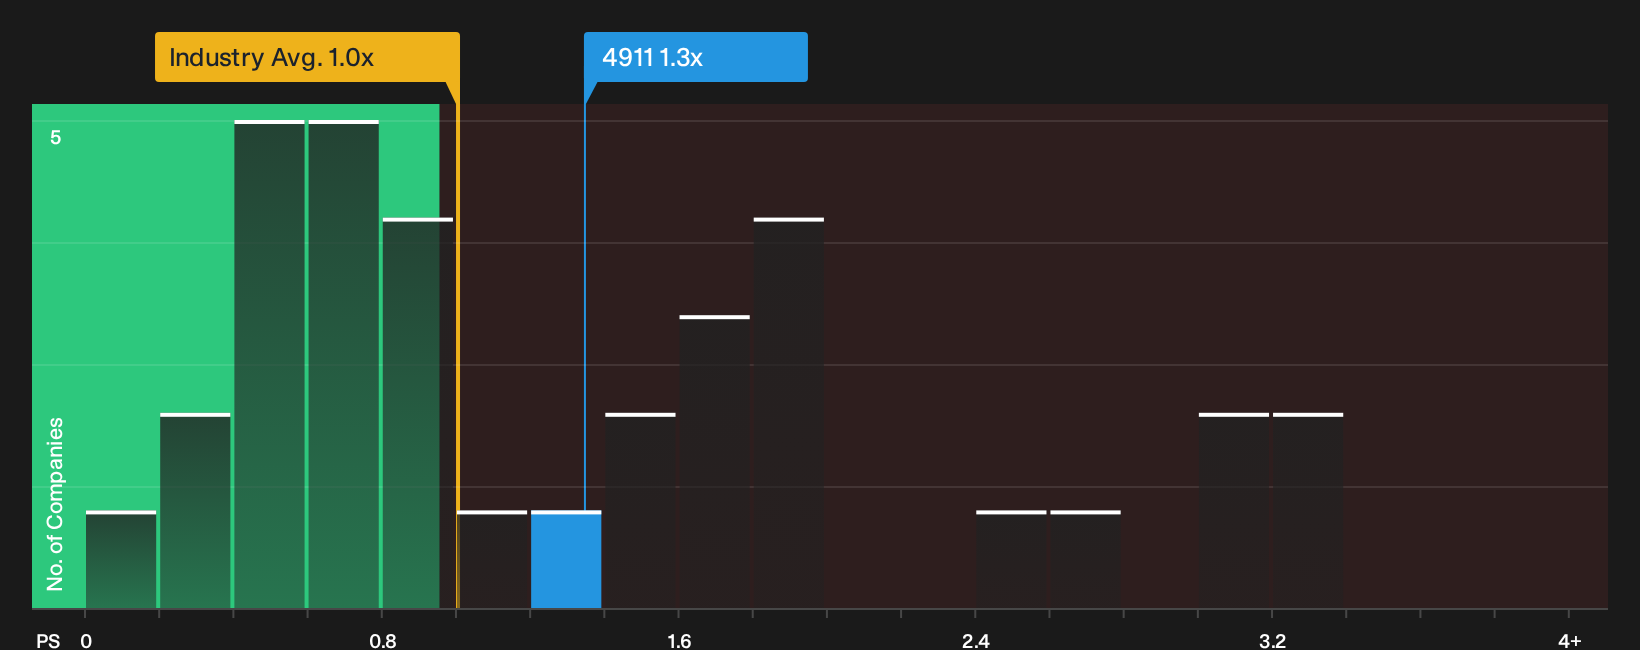
The fair value call at ¥2,596 paints Shiseido Company as overpriced, yet its P/S of 1.3x tells a different story. That figure sits below both the estimated fair ratio of 2.1x and peer average of 2.2x, which suggests sentiment risk more than pure valuation excess. Which signal do you trust more right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Shiseido Company is clearly split. Move quickly, review the full data set, and pressure test both sides of the argument using the 1 key reward and 2 important warning signs.
Looking for more Shiseido Company investment ideas?
Do not stop your research with Shiseido Company. Use the Simply Wall Street Screener to spot fresh ideas, compare quality, and keep your watchlist ahead of the crowd.
- Target resilient compounding potential by scanning a curated 14 high quality undervalued stocks that combines quality fundamentals with pricing that may appeal to value focused investors.
- Strengthen portfolio durability by reviewing a 22 resilient stocks with low risk scores built around businesses with more defensive risk profiles and sturdier financial characteristics.
- Get early to quieter opportunities through a 73 high quality undiscovered gems that highlights under-followed companies with robust underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com