


TransDigm Group (TDG) is back in focus after fresh commentary highlighted its pattern of beating earnings estimates and a current positive Earnings ESP, drawing attention to investor expectations ahead of the upcoming report.
The recent enthusiasm around TransDigm Group is bumping up against a weaker share price trend, with the stock down 18.12% on a year to date share price return and the 1-year total shareholder return slipping 15.25%, even as the 3-year and 5-year total shareholder returns of 50.76% and 106.85% point to a longer term story that has previously rewarded patient holders.
Scan other aerospace and capital goods stocks with similar earnings momentum and sentiment by reviewing our hand picked 32 high quality undervalued stocks alongside TransDigm Group.
For TransDigm Group, the tension is simple. After a sharp pullback, are you looking at fresh upside potential or a stock that has already delivered most of its gains?
Most Popular Narrative: 25% Undervalued
On the most followed view, TransDigm Group screens as undervalued, with a narrative fair value of $1,475.55 against a last close of $1,112.39. That gap is being explained by a mix of aftermarket strength, acquisition activity, and rising risk flags that investors are weighing differently.
The current valuation implies the share price already reflects concern about slower aftermarket growth, regulatory and legislative risk, and insider selling, even as the business delivers high EBITDA margins and increased 2026 cash flow guidance.
See why 34 investors see TransDigm Group as 25% undervalued.
Result: Fair Value of $1475.55 (UNDERVALUED)
Still, the bullish TransDigm Group story can be knocked off course if right to repair rules weaken its aftermarket grip or if regulators tighten the screws on future acquisitions.
Find out about the key risks to this TransDigm Group narrative.
Another View: What Multiples Say About TransDigm Group
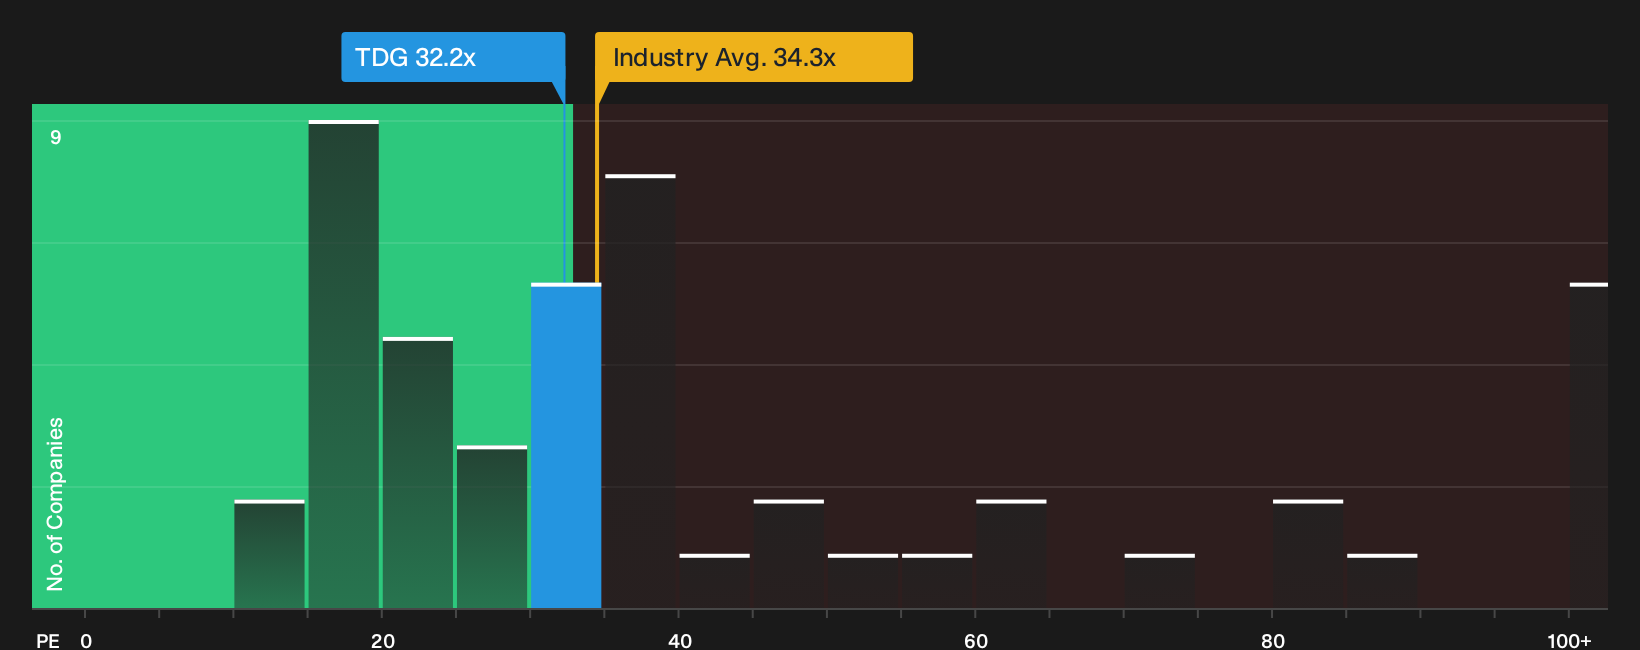
The story changes once you look at TransDigm Group through its P/E. The stock trades on 32.2x earnings, which is lower than the US Aerospace & Defense average of 34.3x, yet higher than the peer average of 26.2x and above a fair ratio of 30.6x that the market could move towards over time. That mix points to some valuation risk on compression, even if the broader sector backdrop stays supportive. How comfortable are you with paying a premium now for a business that some models already call undervalued on other measures?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The split view around TransDigm Group is clear, and the clock is ticking for you to weigh the risks against the upside and decide where you land. To see both sides laid out in one place, review the 4 key rewards and 3 important warning signs
Looking for more TransDigm Group sized ideas?
If you stop with TransDigm Group, you miss the wider opportunity set. Put a shortlist together now so the next move is on your terms.
- Target resilient compounding potential by scanning a 32 resilient stocks with low risk scores. It filters for businesses with steadier profiles when markets turn choppy.
- Hunt for strong fundamentals by running a list of solid balance sheet and fundamentals (25 results). It highlights companies with cash, manageable debt, and room to maneuver.
- Get ahead of the crowd by checking a 20 high quality undiscovered gems. It focuses on quality stories still flying under most investors' radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com