


Milwaukee, Wisconsin-based WEC Energy Group, Inc. (WEC) provides regulated natural gas and electricity, and renewable and nonregulated energy services in the United States. The company has a market cap of $34.5 billion and operates through Wisconsin, Illinois, Other States, Electric Transmission, and Non-Utility Energy Infrastructure segments. WEC is expected to release its Q3 2026 earnings soon.
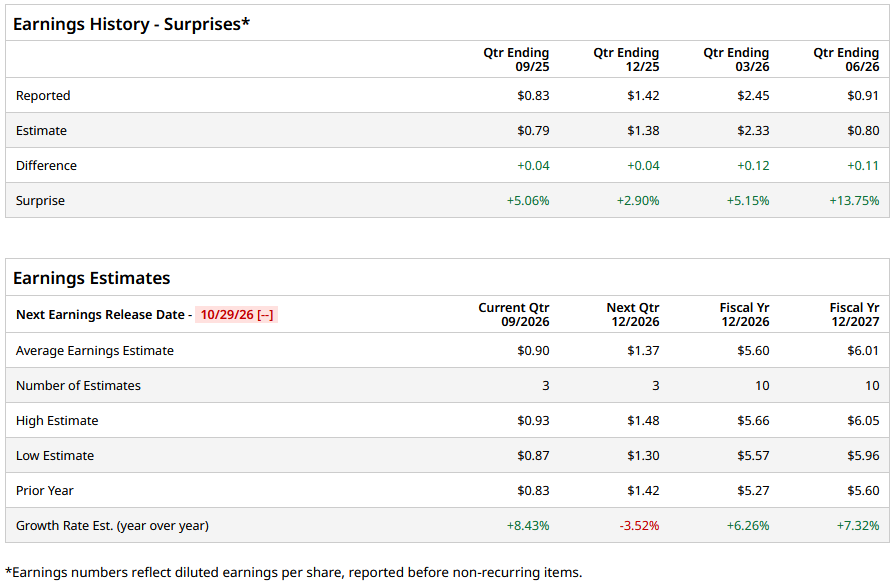
Ahead of this event, analysts anticipate the company will generate earnings of $0.90 per share, representing an increase of 8.4% from $0.83 per share reported in the same quarter last year. The company has surpassed the Street’s bottom-line estimates in each of the past four quarters.
For fiscal 2026, analysts expect the company to report an EPS of $5.60, indicating a 6.3% rise from $5.27 reported in fiscal 2025. Moreover, its EPS is expected to rise nearly 7.3% year over year (YoY) to $6.01 in fiscal 2027.
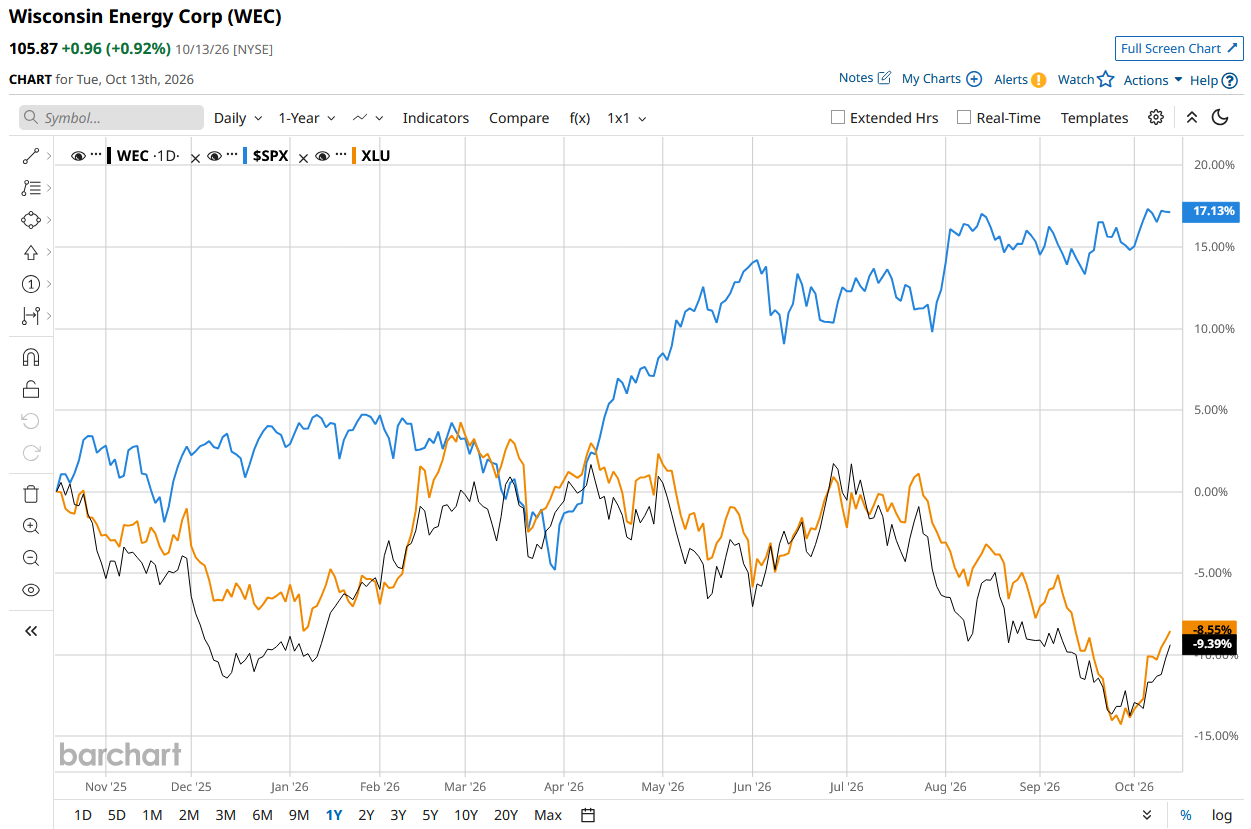
WEC Energy shares have declined more than 7.9% over the past 52 weeks, underperforming the S&P 500 Index’s ($SPX) 17.3% rise and also slightly lagging behind the State Street Utilities Select Sector SPDR ETF’s (XLU) 7.9% fall during the same time frame.
On July 29, WEC stock fell 2% following the release of its mixed Q2 2026 earnings. The company’s revenue for the period amounted to $2.1 billion, which missed the Street’s estimates. However, its adjusted EPS came in at $0.91, topping the consensus estimates. Moreover, WEC Energy expects full-year earnings to be $5.51 to $5.61 per share. Despite the earnings beat, investor confidence was lost due to the company failing to live up to analyst estimates.
Analysts’ consensus opinion on the stock is moderately bullish, with a “Moderate Buy” rating overall. Of the 19 analysts covering the stock, seven recommend a “Strong Buy,” 11 rate it a “Hold,” and one recommends a “Strong Sell.” WEC’s average analyst price target is $119.08, indicating an upside of 12.5% from the current level.
On the date of publication, Aritra Gangopadhyay did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.