


Takeover rumors typically lead to a near-term price gain for the target company's shareholders. On Oct. 9, Ambarella (AMBA) shares gained 7% after reports emerged that it was in acquisition talks with NXP Semiconductors (NXPI) and Qualcomm (QCOM).
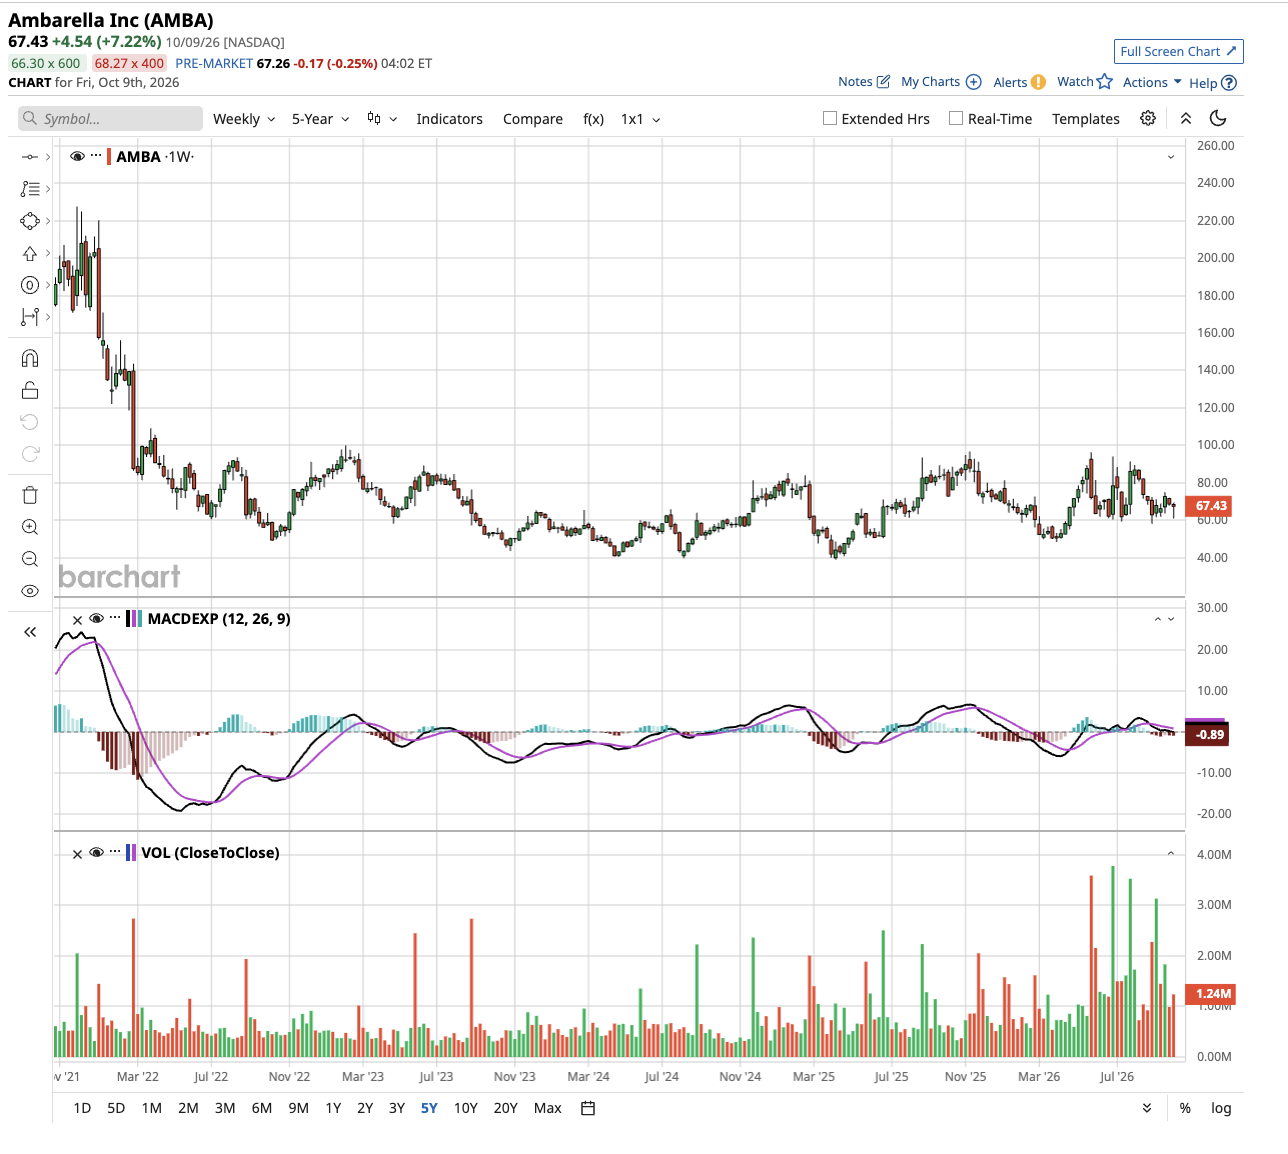
Valued at a market capitalization of $2.8 billion, AMBA stock has underperformed the broader markets over the last five years, falling about 63% since October 2021. Today, the small-cap chip stock is also down 70% from its all-time high and 33% from its 52-week high.
Is AMBA stock a good buy now that Ambarella is a potential acquisition target — and would you want to own shares of the company if no buyer ever showed up? Let's take a closer look.
Qualcomm Rumor Lifts Ambarella Stock
Ambarella stock rose more than 7% on Oct. 9 after traders pointed to a Betaville alert. The alert said that Qualcomm may be working with advisors on a potential deal to acquire Ambarella. Meanwhile, Ambarella is also rumored to be in talks with NXP and Qualcomm, with bankers involved.
The talks are reportedly in advanced stages after initial discussions began in July. Notably, late that month, AMBA stock surged more than 16% after the Financial Times reported that NXP was in talks to buy the chip designer.
Ambarella designs chips that let cameras, cars, and robots process real-time information. CEO Fermi Wang told the Citi Global TMT Conference on Sept. 9 that the company has focused on edge artificial intelligence (AI) for 10 years. Ambarella has also reportedly shipped more than 50 million edge AI chips.
At the conference, Wang noted that Analog Devices (ADI) recently bought a startup for $1.5 billion. By his account, the startup is fairly pre-revenue, while its chips also offer far less AI processing power than Ambarella’s chips. The CEO also noted that Ambarella generates about $400 million in revenue.
Ambarella's market value is only roughly double that startup price, making the potential acquisition even more attractive. Qualcomm is a chip-making giant and a direct competitor to Ambarella, but overlapping products could also add costs, so a deal is far from automatic.
A Focus on Steady Growth
In the fiscal second quarter, Ambarella reported revenue of $108.1 million, up more than 13% year-over-year (YOY). Automotive set a new revenue record, led by commercial vehicles in Q2, while management guided Q3 revenue to a range of $115 million to $124 million. Management also raised its five-year market estimate from $8.5 billion in fiscal 2027 to $22.9 billion in fiscal 2032, a 20% compound annual growth rate (CAGR).
Until now, almost all of Ambarella’s revenue has come from its own direct sales teams, a strategy which works well for larger customers. However, this leaves mid-sized buyers underserved. Ambarella has partnered with Capgemini and Macnica to address these issues.
Capgemini targets larger enterprises. The company says its partnership with Capgemini will help them move from testing edge AI to running it at scale and with less complexity. Capgemini brings engineering, system integration, and industry expertise, while Ambarella brings its power-efficient chips and software.
Meanwhile, global technical distributor Macnica signed a seven-year deal with Ambarella to build a network of software vendors around the latter’s chips, which includes onboarding and technical support. Targets include drones, retail, manufacturing, smart cities, and robotics.
Both partners will use Ambarella’s Cooper software platform. Executive Muneyb Minhazuddin described Macnica as a volume play and Capgemini as a value play. Wang noted that each partner could bring about $500 million in revenue over seven years, adding that early wins will be small while meaningful revenue is two to three years away.
Finally, Ambarella's semi-custom CV8 2-nanometer chip is expected to deliver its first production revenue in fiscal 2028.
The Bear Case for AMBA Stock
Similar to other chip companies, Ambarella is struggling to keep up with demand. At the Citi Global TMT Conference, Wang said that customers could not get November memory commitments from suppliers.
Wang is comfortable with the company’s Q3 revenue guidance of $115 million to $124 million. Customers’ forecasts for the quarter look solid, although he sees a little uncertainty, with memory already trimming revenue slightly. The executive said that customers told him their memory suppliers cannot even commit to November allocations. Buyers do not know how much memory they will get or what it will cost.
Ambarella ended the period with $272.3 million in cash and marketable securities, down $5.5 million from the prior quarter. While the company is expected to report marginal free cash outflow this year, its free cash flow is expected to rise to roughly $241 million in fiscal 2031.
Inventory days also rose to 157 from 145 in Q2. Inventory days roughly indicate how long it would take Ambarella to sell its in-stock chips. At 157 days, that is about five months of supply. CFO John Young said inventory dollars actually fell 4% sequentially for the quarter, so Ambarella didn't pile up more product during the period.
That said, Wang did note that supply across the industry is getting tight, from foundries to packaging. Holding more stock could be a deliberate buffer, although that is my analysis and not something either executive said.
Meanwhile, a key risk for Ambarella is customer concentration. The company reported that WT Microelectronics, a logistics partner in Taiwan, accounted for more than 60% of Q2 revenue. At the Citi conference, Wang was refreshingly honest, too. He said no single application has emerged to drive edge AI revenue, and he has no timeline. The CEO also noted that humanoid robots will need time before they move the needle in terms of revenue growth.
My Take on AMBA Stock
Ambarella looks cheaper than it did a year ago. However, AMBA stock still trades at an elevated forward price-to-earnings (P/E) multiple of 84.7 times.
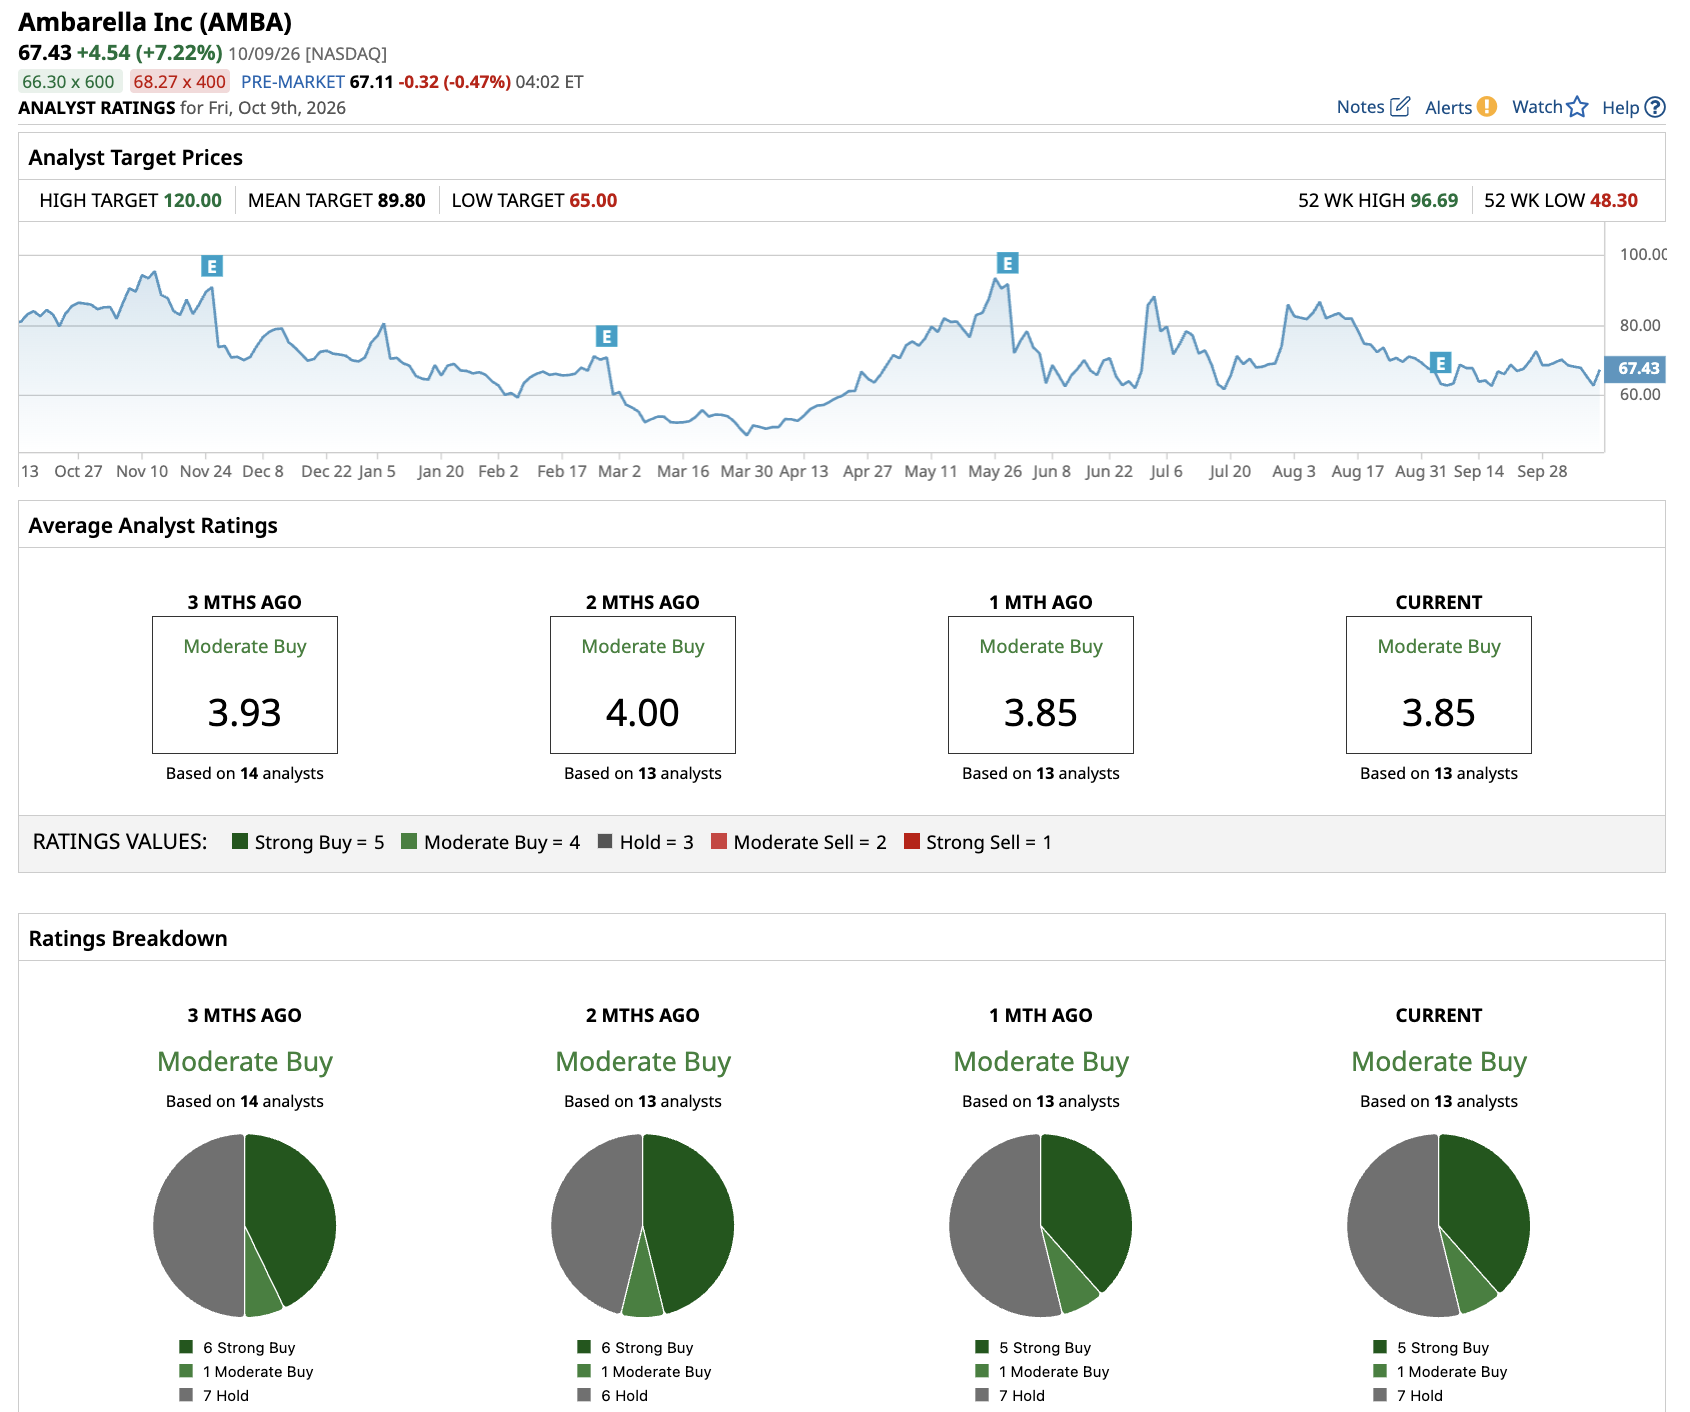
Overall, Ambarella stock has a consensus “Moderate Buy” rating on Wall Street. Out of the 13 analysts tracking AMBA stock, five recommend a “Strong Buy” rating, one recommends a “Moderate Buy” rating, and seven recommend a “Hold” rating. The average price target of $89.80 represents potential upside of 40% from current levels.
All told, I would not buy AMBA stock for a Qualcomm bid. If you buy the stock, do it because you believe in edge AI and have a long-term view.
On the date of publication, Aditya Raghunath did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.