


- Textron Systems recently introduced CoreMotion, a robotic control package that acts as a middle-layer execution system between autonomy software and ground vehicle hardware, designed to support rapid deployment of autonomous capabilities and retrofits across existing fleets.
- The CoreMotion launch points to Textron deepening its role in defense robotics by offering customers a scalable, lower risk path to modernize crewed vehicles into robotic platforms without full fleet replacement.
- We will now examine how Textron's investment narrative could shift as CoreMotion's autonomy middleware becomes part of the defense portfolio.
Scan how Textron's push into defense robotics compares with peers by reviewing the hand picked 90 robotics and automation stocks shaping autonomous ground systems and next generation military platforms.
Textron Investment Narrative Recap
For Textron, the big picture an investor needs to believe in is that management can steadily improve execution in Aviation and Bell while tilting more of the portfolio toward higher value defense systems. The CoreMotion launch fits that idea. It ties Textron more closely to the long running shift toward autonomous ground systems but does not change the main near term story around margins and program delivery.
The most important short term swing factor still sits with execution on manufacturing efficiency and MV 75 funding and charges, rather than CoreMotion itself. The largest immediate risk remains that production issues linger or funding decisions slip, which could pressure earnings and cash flow even if demand indicators and the defense backlog stay supportive.
Among the existing catalysts, the planned separation of the more than US$3b Industrial segment is the most relevant comparison for CoreMotion. Both developments point to Textron becoming a more focused aerospace and defense group, with a bigger concentration in platforms, support, and now autonomy middleware.
If management delivers the targeted uplift of about 150 basis points to revenue growth and 120 basis points to segment profit margin for the remaining company, investors may watch how new offerings like CoreMotion plug into that tighter portfolio. The main risk lies in execution complexity. Textron needs to juggle the spin, margin recovery efforts, and long dated programs like MV 75 while also demonstrating that newer systems such as CoreMotion can scale commercially rather than remaining niche.
Textron's consensus story points to revenues of US$16.8b and earnings of US$1.2b by 2029, based on analysts assuming 3.1% yearly revenue growth and an earnings increase of about US$261m from current earnings of US$939.0m.
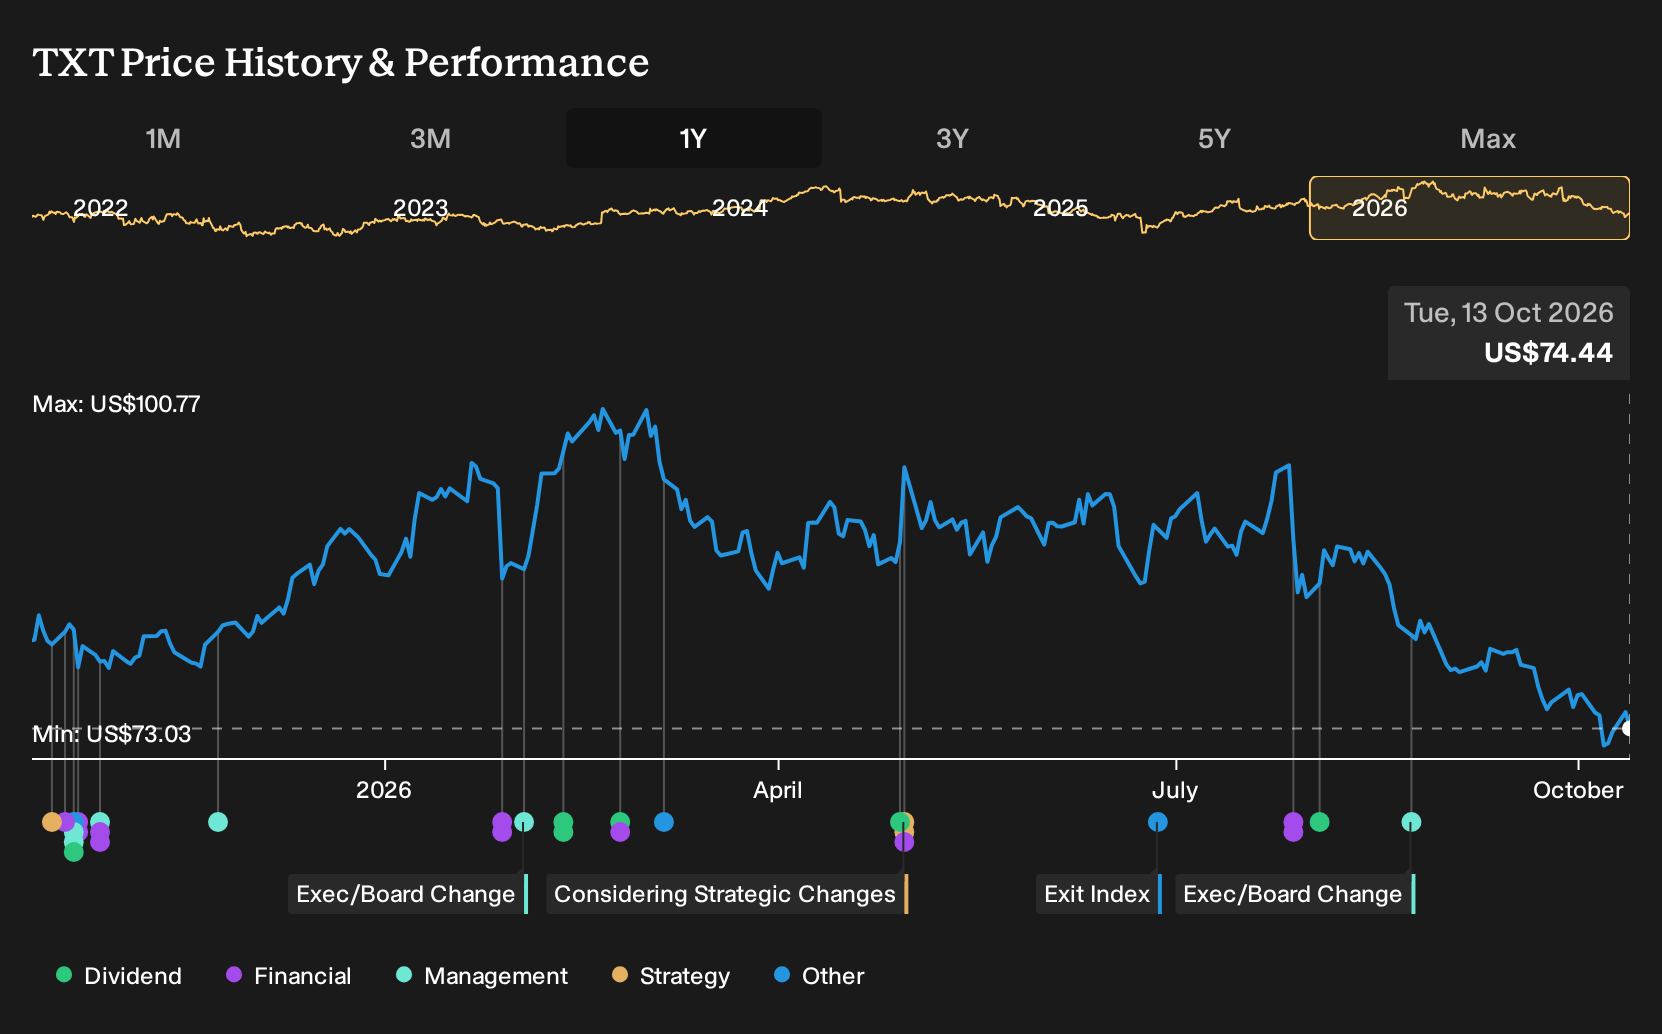
Uncover why Textron's fair value indicates a 36% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic Textron analysts focus on the Advanced Reconnaissance Vehicle program as a bigger swing factor than CoreMotion. Before this news, they were modelling revenues of about US$18.1b and earnings of roughly US$1.3b by 2029. You can treat CoreMotion as a fresh test of whether that upbeat view still holds or shifts.
Explore 4 other Textron fair value estimates, including one that suggests potential upside of as much as 93% from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own research and going with your instincts.
- A great starting point for your Textron research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Textron. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Textron's overall financial health at a glance.
Looking For More Investment Ideas Beyond Textron?
Once you are comfortable with your Textron view, it can help to line it up against a wider opportunity set using the Simply Wall St Screener. That way you can see where Textron fits alongside other businesses with different risk, income, and value profiles.
- If you want potential growth with a small starting size, scan a focused set of early stage opportunities through 11 elite penny stocks with strong financials that already show stronger financial markers than most tiny caps.
- For investors who care most about valuation support and balance sheet strength, weigh Textron against a curated 32 high quality undervalued stocks that combine cash generation with robust finances.
- If capital preservation and a smoother ride matter more to you than chasing every upswing, compare Textron with a 32 resilient stocks with low risk scores that screen well on Simply Wall St's risk scoring.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com