


Regulatory petition puts Trinity Industries’ cross border model under scrutiny
Trinity Industries (TRN) is now in the spotlight after UTLX Manufacturing, a Berkshire Hathaway subsidiary, filed antidumping and countervailing duty petitions targeting Trinity’s Mexico built railway tank car imports into the United States.
The filings, lodged with the U.S. Department of Commerce and the International Trade Commission, challenge a supply chain Trinity has used for decades and could influence how investors evaluate the resilience of its North American manufacturing footprint.
Recent trading reflects that scrutiny. Trinity Industries’ 1-day share price return of 1.16% comes after a 30-day share price decline of 7.89% and a 90-day slide of 27.20%, while the 3-year total shareholder return of 26.91% shows a very different longer term picture.
Scan how regulatory pressure is rippling across capital goods and rail suppliers by reviewing the hand picked 32 resilient stocks with low risk scores alongside Trinity Industries’ latest developments.
Trinity Industries trades at a discount to analyst targets after the regulatory hit and weakening earnings trends. Is that a margin of safety, or a warning light for valuation work that follows?
Most Popular Narrative: 20.5% Undervalued
Against a last close of $26.25, the most followed narrative pegs Trinity Industries’ fair value at $33.00, framing today’s price as a discount that hinges on how much of the railcar fleet’s embedded value can be realized.
Ongoing portfolio management actions such as railcar sales and partnership restructurings, including large non cash gains from recent transactions and management’s estimate that the owned fleet is worth 35% to 45% above carrying value, give Trinity Industries multiple ways to convert embedded asset value into gains, cash flow, and potentially higher earnings.
See why 2 investors see Trinity Industries as 20% undervalued.
Result: Fair Value of $33.00 (UNDERVALUED)
Still, Trinity Industries’ reliance on cyclical sectors and on large gains from railcar sales and partnership restructurings could quickly weaken that 20.5% undervaluation story.
Find out about the key risks to this Trinity Industries narrative.
Another View: Trinity Industries Through The Earnings Lens
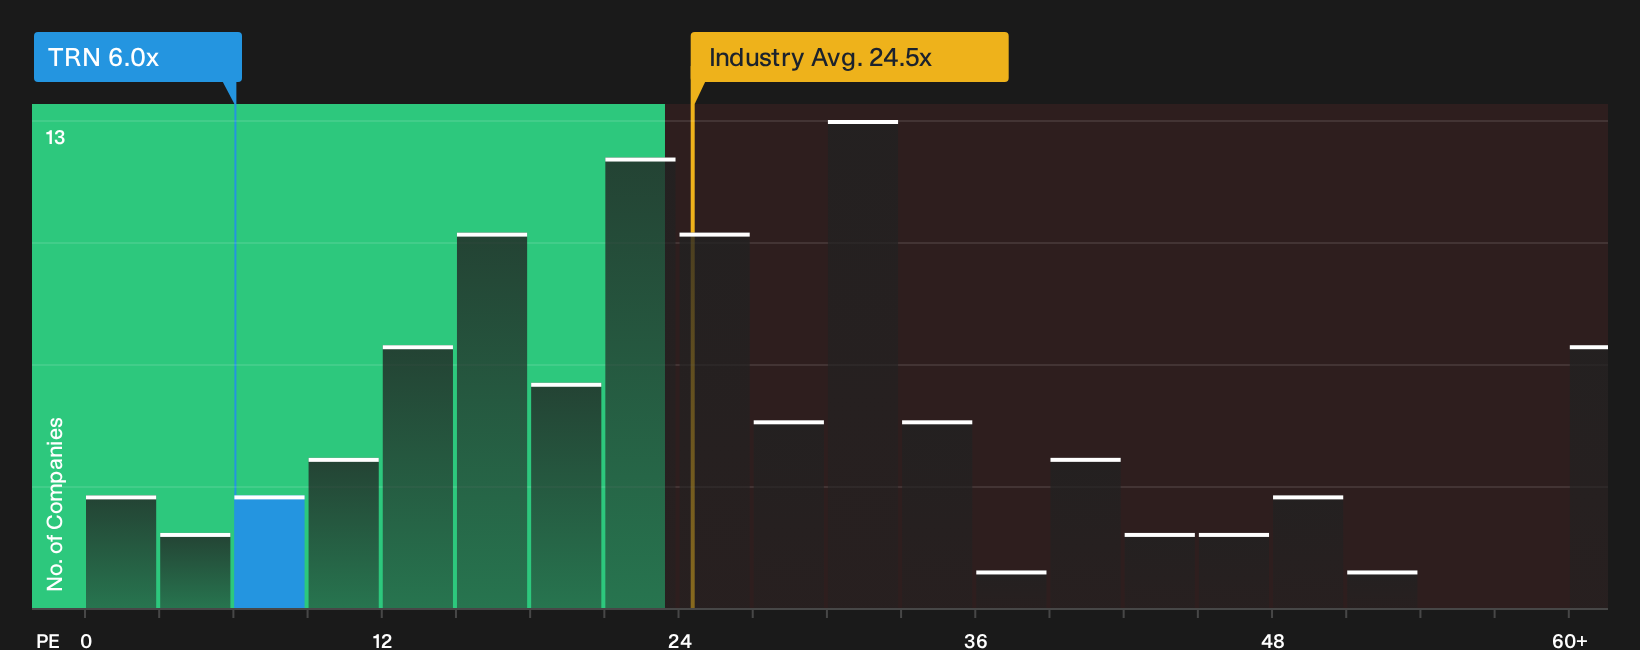
That 20.5% undervaluation story leans on analyst fair value, yet the current P/E of 6x tells a more cautious tale. Trinity Industries trades well below the US Machinery industry on 24.4x and a peer average of 18.9x, but above its own 5.1x fair ratio, which hints at some valuation risk if sentiment cools.
Put differently, the market is pricing Trinity Industries cheaply against its sector while still carrying a premium to the fair ratio that our models suggest the P/E could move toward. How much comfort you take from that mix of apparent value and embedded downside risk depends on your conviction in the earnings power behind the multiple See what the numbers say about this price — find out in our valuation breakdown..
To see where Trinity Industries stands next to its industry on this metric in one view, review the latest relative valuation chart for the stock
Next Steps
Mixed signals on Trinity Industries can be frustrating, so move quickly from headline takes to your own judgment by weighing its 2 key rewards and 5 important warning signs.
Looking for more investment ideas beyond Trinity Industries?
Trinity Industries gives you plenty to think about, but smart portfolios are built by comparing multiple opportunities side by side using a consistent process.
- Chase potential mispricing by scanning a curated set of value focused opportunities through the 32 high quality undervalued stocks.
- Secure your income stream by reviewing companies that feature resilient payouts and balance sheets using the 8 dividend fortresses.
- Protect your downside by filtering for businesses screened for resilience and stability via the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com