


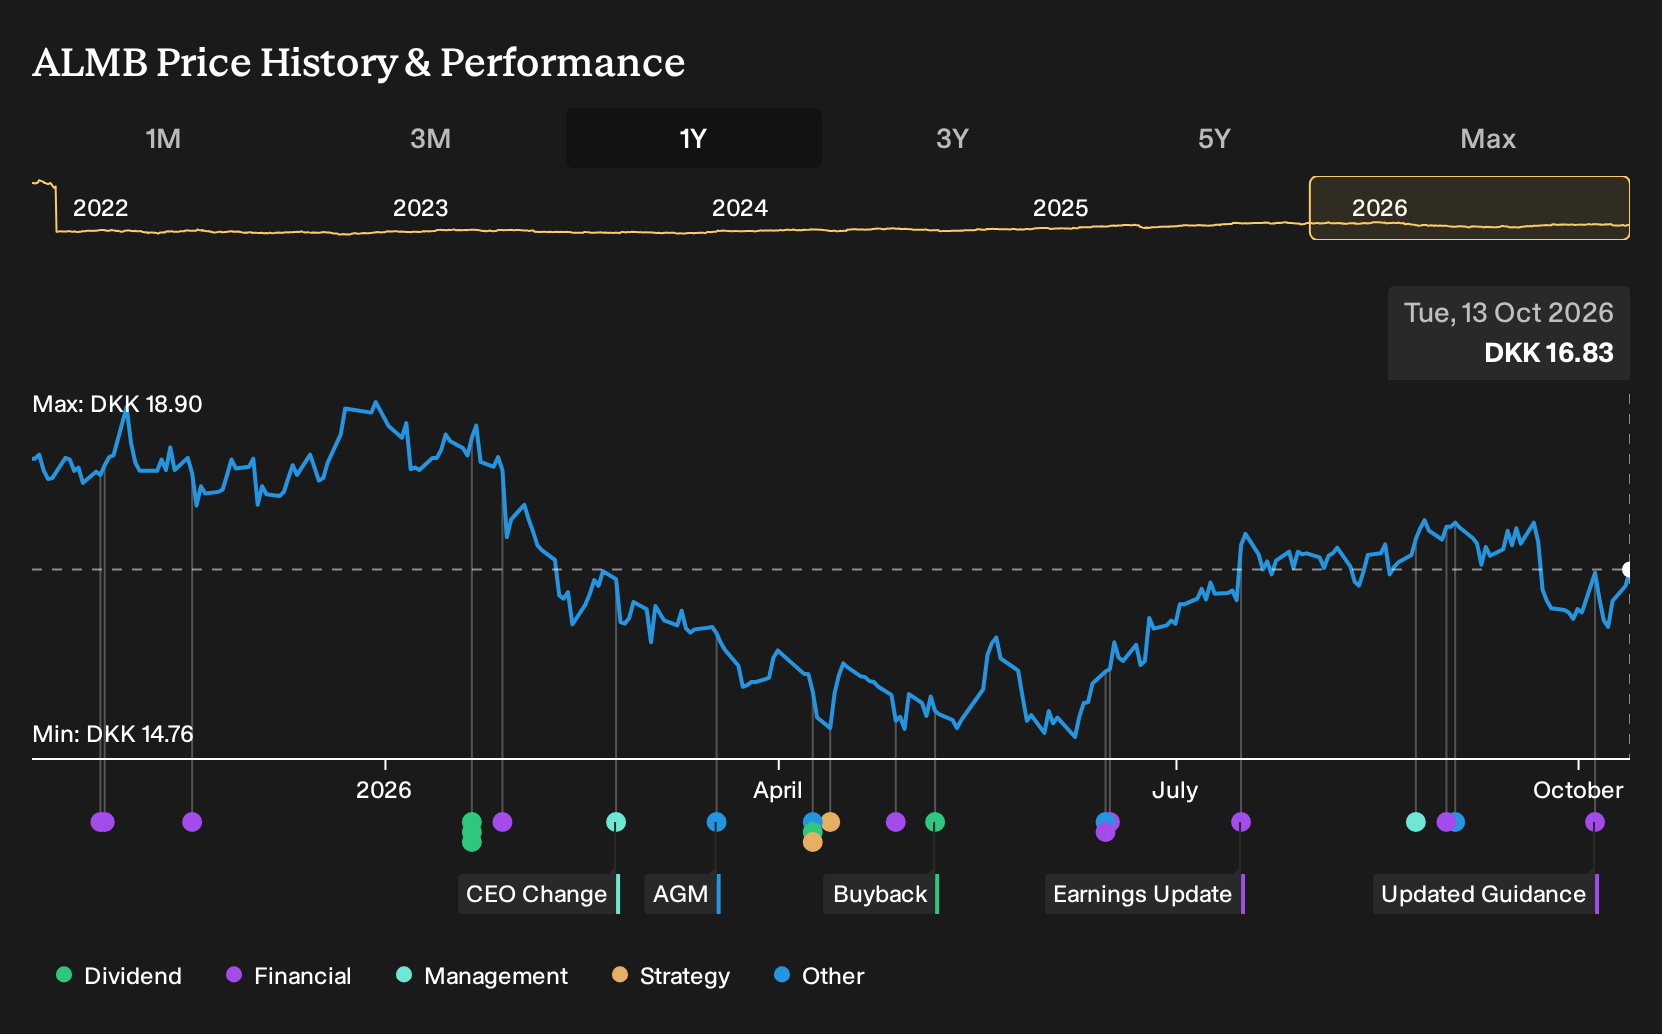
- Alm. Brand A/S has raised its 2026 full year insurance service result guidance to DKK 1.5b to 1.6b after a favourable Q3, up from the previous DKK 1.2b to 1.4b range and excluding potential run offs in Q4.
- The company is also running a share buy back program of up to DKK 593 million. As of 12 October 2026 it holds 49,009,465 own shares, equal to 3.49% of its outstanding equity, which tightens the free float while guidance moves higher.
- We will look at how Alm. Brand's investment narrative is affected by the higher 2026 insurance service result guidance after a strong quarter.
Scan how Alm. Brand's guidance upgrade and buyback stack up against other insurers by reviewing the curated 223 resilient stocks with low risk scores that may offer similar balance sheet resilience and earnings visibility.
Alm. Brand Investment Narrative Recap
To own Alm. Brand, you need to believe the insurance engine in Denmark can keep converting personal and commercial relationships into steady premiums while repricing and cost work support profitability. The higher 2026 insurance service result guidance points to healthier underlying operations in the near term, although it still excludes any Q4 run offs.
The key short term swing factor remains execution on repricing and claims management, especially in motor, where earlier frequency relief might prove temporary. The biggest risk is that high payouts and buybacks tighten financial flexibility just as competition, regulatory demands or a higher tax burden put pressure on earnings quality.
The most relevant announcement here is the DKK 1.5b to 1.6b insurance service result guidance for 2026, lifted by DKK 250m after a strong Q3. That revision ties directly into the existing catalyst around synergy extraction and repricing, since it reflects how current underwriting and cost actions are feeding into near term profitability expectations.
For you as a shareholder, this updated outlook intersects with the ongoing DKK 593m share buyback. A higher earnings contribution combined with a smaller share count can support per share metrics, although the high payout approach also amplifies the earlier risk that Alm. Brand has less room to reinvest if claims trends, competition or regulation turn less friendly.
Alm. Brand's current analyst narrative points to DKK 13.4b in revenue and DKK 1.6b in earnings by 2029. That aligns with a flat top line profile and implies earnings would need to rise by about DKK 400m from DKK 1.2b today.
Uncover why Alm. Brand's fair value indicates a 17% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster between DKK 19.7 and about DKK 28.3, so some retail investors see Alm. Brand as materially mispriced. Those viewpoints pre date the October guidance lift and ongoing buyback, and sit alongside risks around high payout, motor claims and capital rules that could shift the story. Readers should treat these as starting points and compare several alternative opinions before deciding how Alm. Brand fits in their portfolio.
Explore another Alm. Brand fair value estimate, including one that suggests it could be worth just DKK 19.70.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Alm. Brand research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Alm. Brand. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alm. Brand's overall financial health at a glance.
Looking for more Alm. Brand style investment ideas?
If Alm. Brand's mix of upgraded guidance and capital returns appeals to you, it can help to line it up against other opportunities that share similar qualities or offer a different risk and income profile.
- If resilience matters most to you, compare Alm. Brand with a curated set of companies that screen well for balance sheet strength using our list of solid balance sheet and fundamentals (203 results).
- If you are hunting for value, weigh Alm. Brand against a broader group of potentially underpriced businesses by scanning the 184 high quality undervalued stocks.
- If income and staying power sit higher on your checklist, line up Alm. Brand next to other steady payers and capital preservers in the 219 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com