


FMC has seen its share price fall hard over the past few years, and that kind of setback naturally raises a simple question for anyone looking at the stock today. Is the current US$8.31 price tag supported by the sales the business is generating, or has the market moved further than the underlying revenue profile can justify?
- Over the past 5 years, FMC shares have declined 89.4%, which puts the spotlight squarely on whether the drop has brought the valuation closer in line with its sales.
- The business model still leans on converting product sales into cash flow, which can matter a lot for how investors judge the value they are placing on each dollar of revenue.
- Your read on FMC is one view; the desks covering it have another. See what analysts think FMC's shares could be worth.
The stock's next move may depend on whether the current market price lines up with what FMC's sales suggest the business should be worth.
If a deep drawdown like FMC's has you reassessing your watchlist, it can help to start fresh with a focused screen of companies that fit clear value and quality criteria such as 32 high quality undervalued stocks.
Is FMC Still Cheap on Sales?
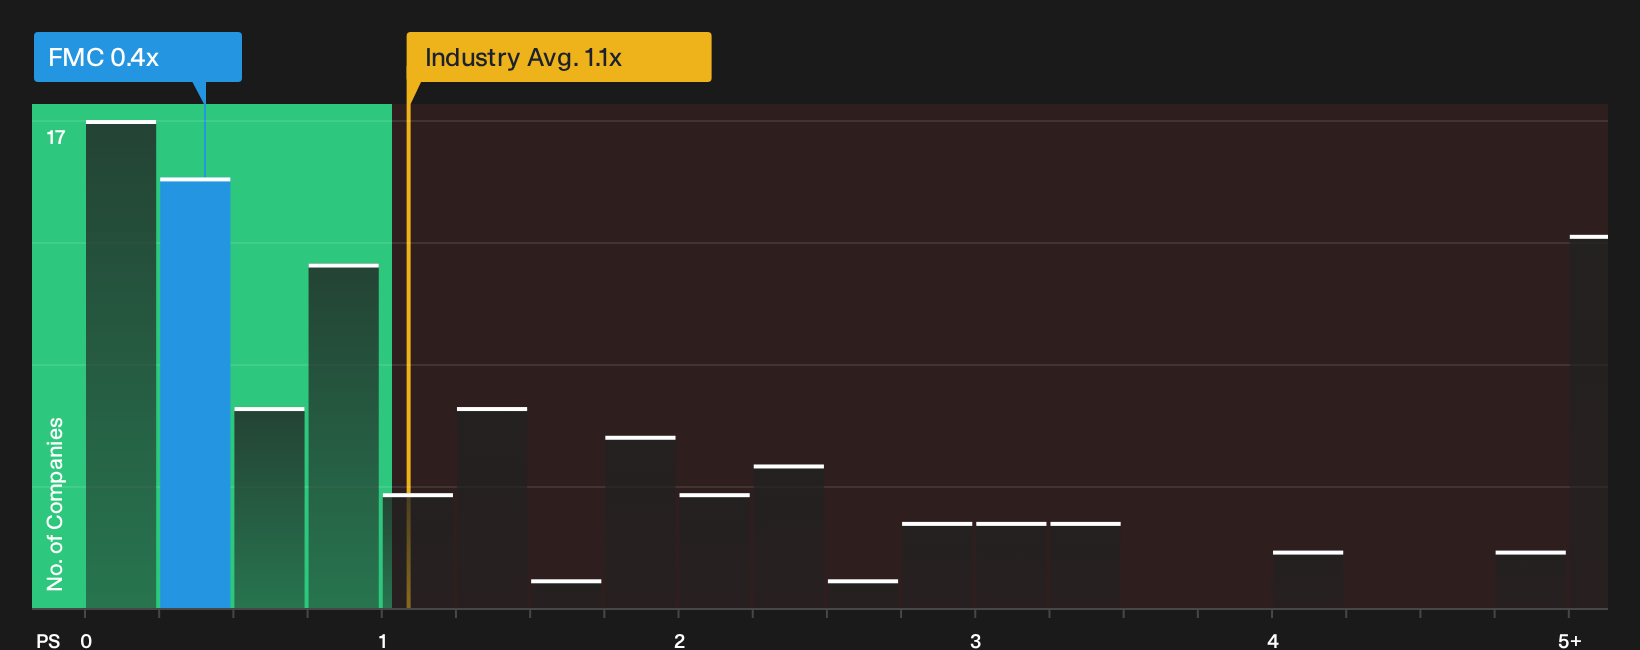
P/S fits FMC because revenue is still the main yardstick investors can use when earnings are distorted. On this measure, the stock trades on a P/S of 0.4x, compared with about 1.1x for the wider Chemicals industry and roughly 1.3x for peers. That is a wide gap for a mature agricultural chemicals player whose value is often anchored to its sales base.
The valuation model that blends FMC's growth profile, profitability, size and risk points to a higher P/S as a more tailored reference level. As a result, the current 0.4x sits below what that framework would suggest. For anyone tracking FMC, the key question is whether current sales quality and future demand justify the market pricing each dollar of revenue at this kind of discount relative to that benchmark. Explore the numbers behind FMC's P/S valuation.
The FMC Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where FMC's valuation puzzle leaves off and spell out what kind of future growth, margins and earnings path would need to play out for the stock to be worth far more or materially less than today's price, all housed on the Community page. Each scenario ties a fair value to a particular mix of potential catalysts and risks, so you can track over time which version of FMC's story appears to be unfolding.
One of the top community narratives on FMC: 39% undervalued
"FMC needs the transition toward IP protected new active ingredients and collaborations, together with execution on manufacturing restructuring, to offset pricing pressure..."
Discover why this Narrative puts FMC at 39% undervalued.
FMC’s valuation still leaves one key piece of the puzzle unresolved
The price tag on FMC tells only part of the story because the people steering the company and the way their pay is structured can strongly shape how that story plays out. See who runs FMC and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com