


- Kontron has begun U.S. production of its rugged VX307H 3U VPX compute platform at Nextek in Huntsville, Alabama, moving the product from build to order to build to stock to support defense customers seeking greater supply-chain resilience, faster delivery and U.S.-based support.
- The shift to American manufacturing of the VX307H, with plans to extend U.S. VPX production to the VX3060 and VX30101, points to a deeper push into high reliability defense computing and a heavier commitment to onshore capacity.
- The next step is a closer look at how Kontron's investment narrative could be influenced by this move to U.S. VX307H production.
Scan for other defense and edge-computing stocks building similar momentum to Kontron by zeroing in on our curated list of 92 AI infrastructure stocks as this U.S. VX307H rollout takes shape.
What Is Kontron's Investment Narrative?
Owning Kontron means buying into an embedded computing specialist that leans heavily on defense, IoT and industrial clients rather than mass market gadgets. The big belief is that specialized hardware and software, like the VX307H platform and broader VPX line, keep finding complex use cases where reliability matters more than headline growth rates. U.S. production in Huntsville fits that idea. It tightens lead times for defense projects, supports build to stock availability and ties directly into near term demand from American programs that care about certified, local manufacturing.
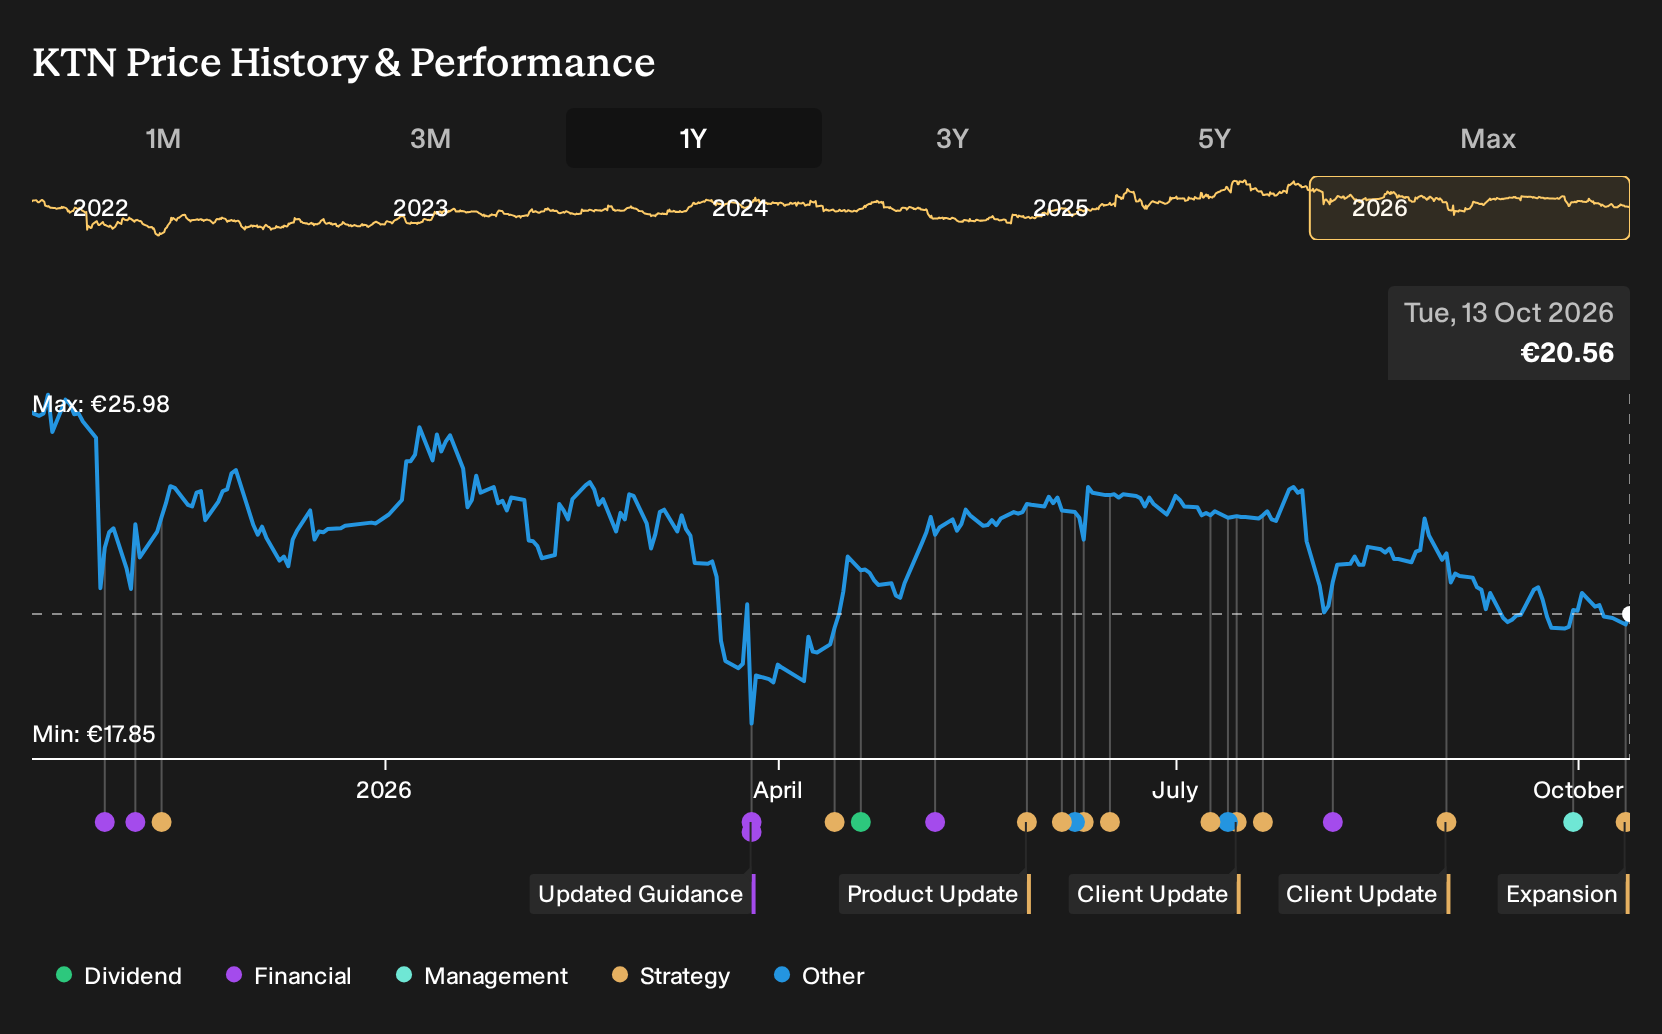
The short term swing factors still sit around execution quality, pricing discipline in contracts, and how capex-heavy this U.S. build out becomes versus the margin pressure already visible. Profit margins moved from 8.2% to 5.4% and recent earnings include a large one off gain of €91.2m, so clean profitability is harder to read. A new CTO with long industry experience, plus analyst models that point to faster earnings growth and a P/E of 14.8x below peer averages, provide some support for this story. Yet the share price is down about 19% over the past year, which shows investors still want proof that the VX307H shift and broader U.S. VPX push turn into durable cash generation rather than just higher fixed costs.
That said, there is a quieter issue around Kontron that could matter far more than the U.S. factory headlines if ...
There's only one way to know the right time to buy, sell or hold Kontron. Head to Simply Wall St's company report for the latest analysis of Kontron's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community currently includes 2 fair value views on Kontron, with estimates spread between €29.13 and €38.58 per share. Those figures were set before the VX307H move into U.S. production and the CTO appointment on 30 September 2026, so you are seeing opinions that may lag fresh information. Investor takes can differ widely, so it can help to review several of these community viewpoints before deciding how the new U.S. defense push might influence your own expectations.
Explore another Kontron fair value estimate, including one that suggests as much as 88% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Kontron research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kontron. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kontron's overall financial health at a glance.
Looking For More Investment Ideas Beyond Kontron?
Once you have a view on Kontron, it can help to put it in context by scanning other opportunities with similar or contrasting qualities using the Simply Wall St Screener.
- If your focus is on stronger balance sheets and fundamentals, start by reviewing our list of solid balance sheet and fundamentals (203 results) that could fit a more conservative approach.
- For readers who want potential mispricings, compare Kontron against our 184 high quality undervalued stocks that pair quality metrics with compressed valuations.
- Income oriented investors can round out their watchlists by checking out our 218 dividend fortresses that combine higher yields with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com