


Inflation is proving sticky again, gas prices are biting into wallets, and short-term interest rates are sitting close to 3.9%, which pulls cash and money-market returns back into the spotlight. That mix creates both pressure and potential opportunity, especially for investors trying to park cash or earn yield without stretching too far on risk. This article examines three stocks that appear closely connected to these trends and outlines how the latest data could be relevant for your portfolio decisions.
The three stocks that follow are just a starting sample, with the full screen surfacing 44 more U.S.-listed banks, brokers, and asset managers tied to short-duration and cash-management themes that are not covered in this article. To go straight to the broader opportunity set, use the Short-Duration Cash and Money-Market Investment Providers screener to identify, compare, and analyze which ideas best fit your own risk and income goals.
Avidbank Holdings (AVBH)
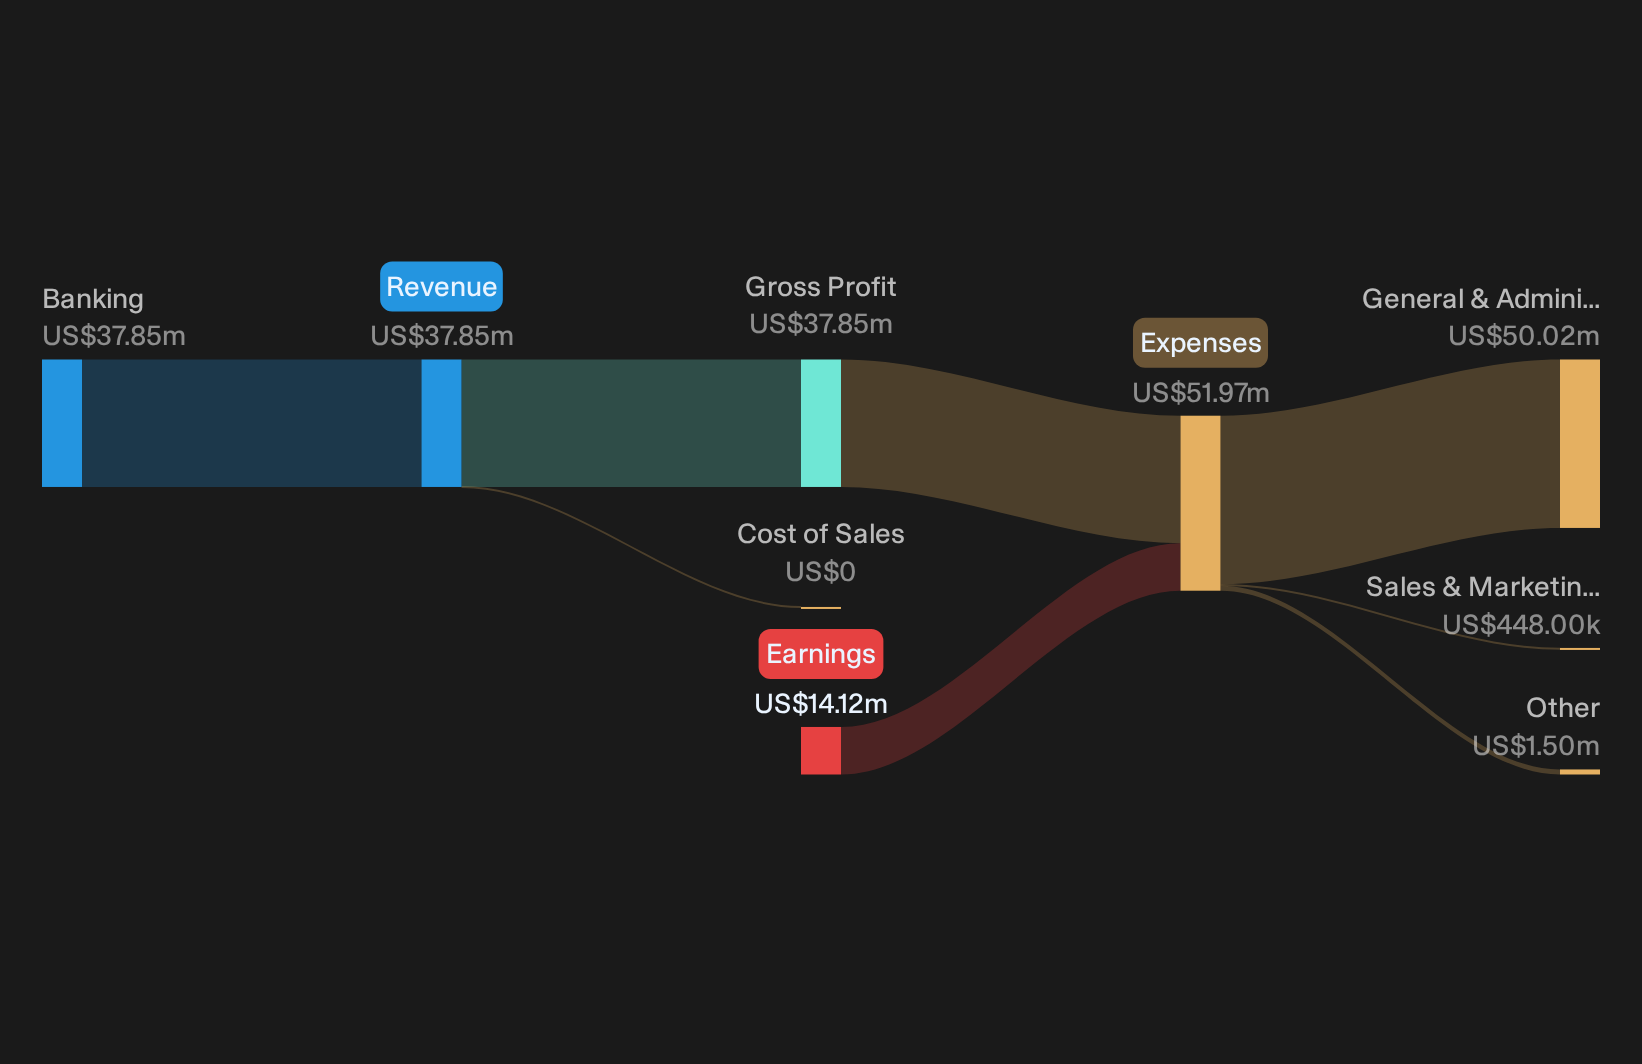
Avidbank Holdings taps directly into the short-duration cash and money-market theme through its mix of deposit products, treasury services, and lending to commercial, venture, and private equity clients, generating about US$38 million from banking activities in the United States and carrying a market value near US$343 million.
Avidbank Holdings illustrates the role of short-duration lenders when rates remain elevated for extended periods, using its balance sheet to pursue better-yielding cash and securities opportunities rather than simply parking excess funds.
"The reinvestment of US$163 million into mortgage backed CMOs at an average yield of 4.54% and the plan to keep the securities portfolio at roughly 10% to 15% of earning assets point to a more focused use of the balance sheet toward loans and higher yielding instruments."
What happens to that careful repositioning if one unseen funding pressure starts to bite into future margins and pricing power?
That funding question is exactly where the story gets interesting, and the full narrative for Avidbank Holdings shows how Avidbank Holdings could respond if deposit costs start accelerating.
Isabella Bank (ISBA)
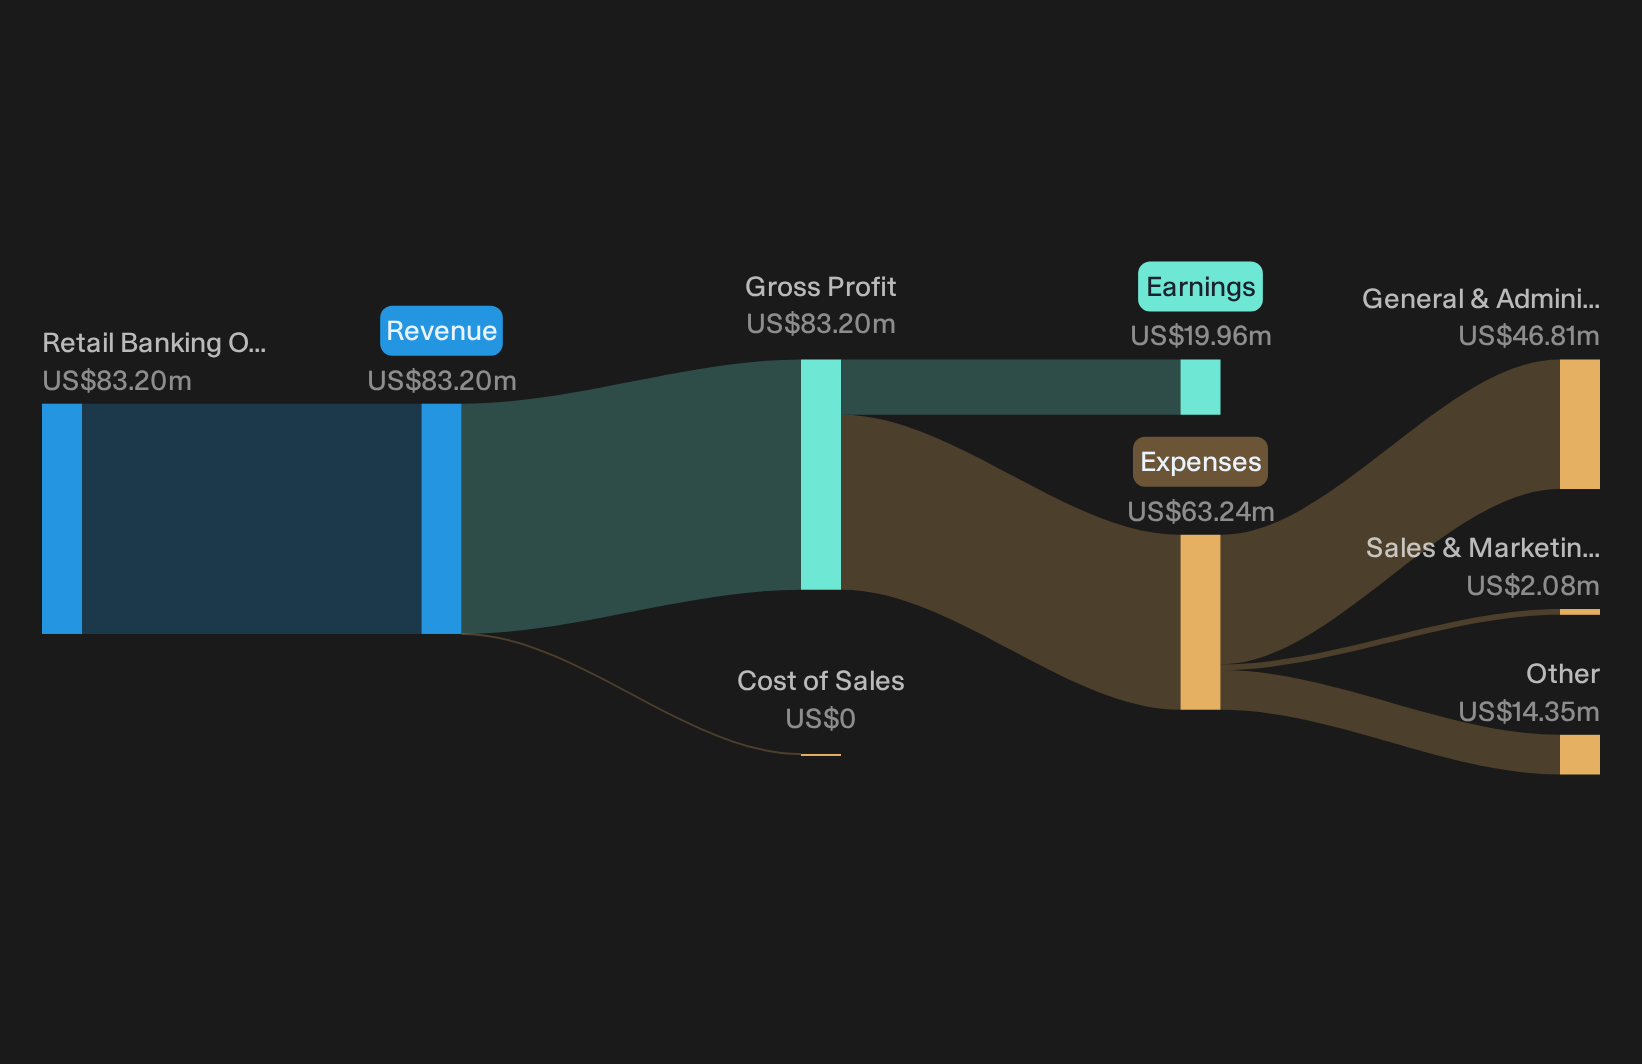
Isabella Bank Corporation is a Michigan community bank that focuses on checking, savings, cash management and likely money-market style offerings tied to short-duration cash needs. It generates about US$83 million from retail banking operations in the United States, with a market value near US$286 million.
Isabella Bank combines traditional community banking with cash-management and wealth services that can appeal to depositors seeking higher yields when short-term rates remain elevated. Reliable income through its dividend and solid net interest income support that cash-focused approach. However, any change in rate-sensitive pressures on its margins will be important for investors who pay close attention to short-duration returns.
Those rate pressures make it a good time to review the Isabella Bank financial health report to evaluate how Isabella Bank’s balance sheet could handle a faster shift in funding costs.
Alerus Financial (ALRS)
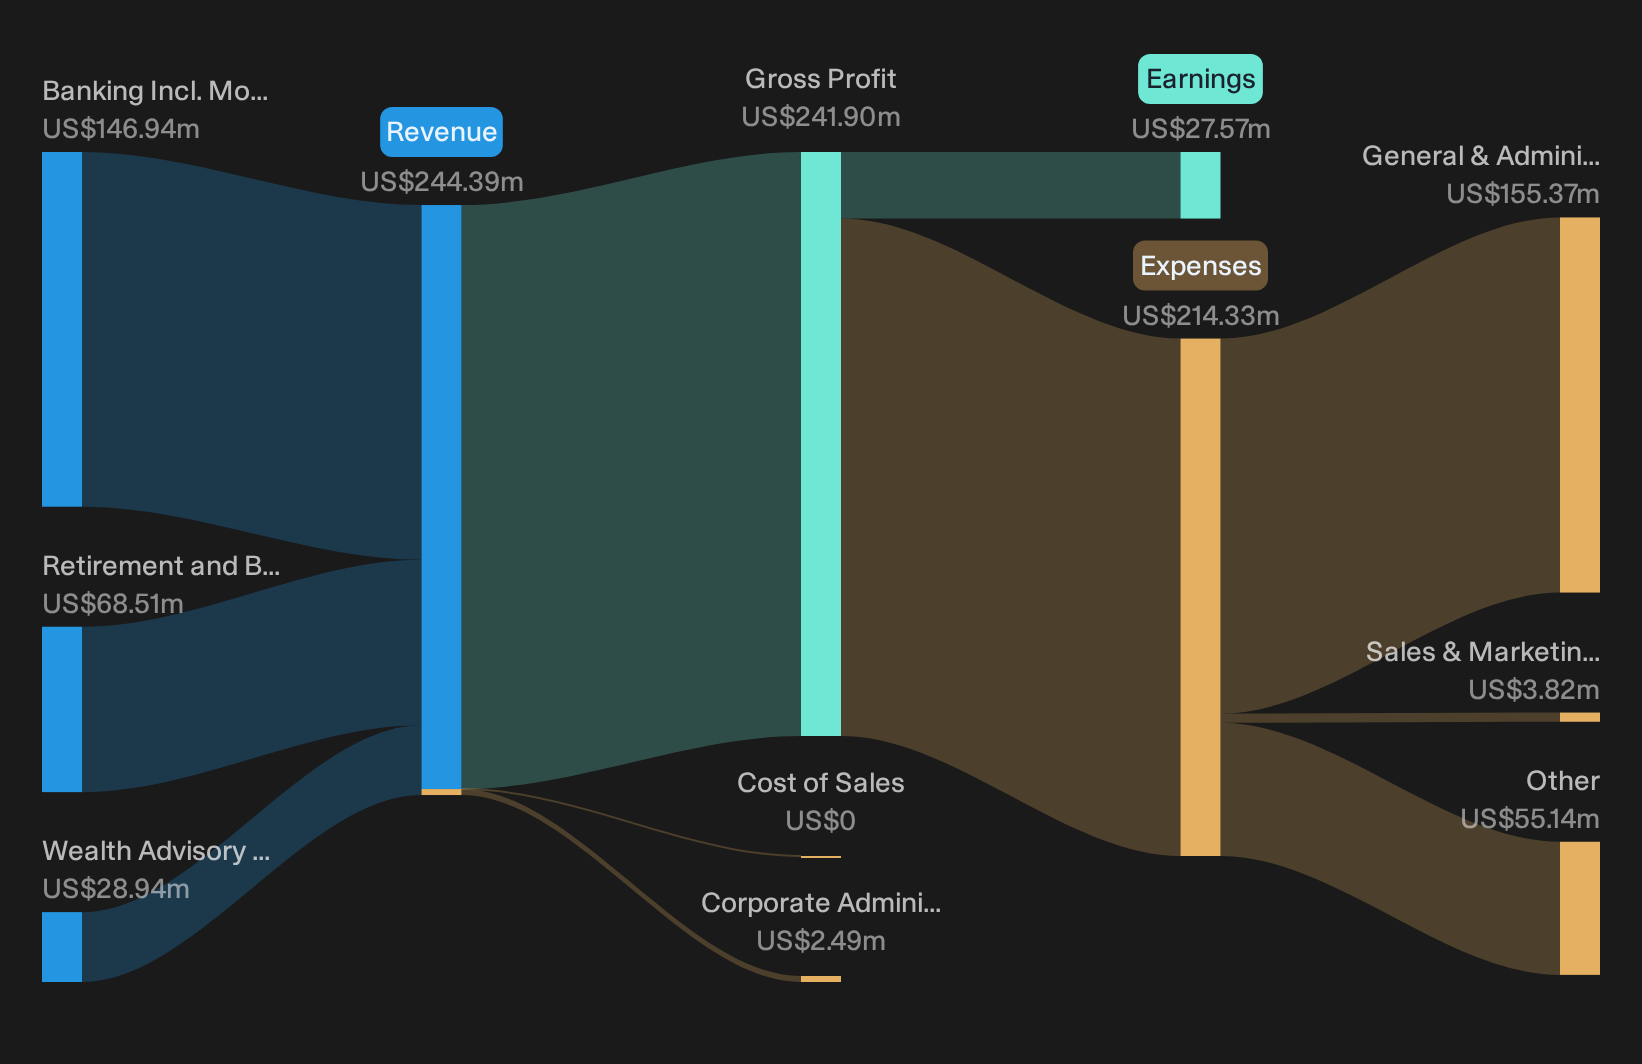
Alerus Financial leans into the short duration cash theme through its mix of money market accounts, treasury management tools, and fee heavy retirement and wealth services that sit alongside a traditional loan book, with about $146 million from banking, $69 million from retirement services, and $29 million from wealth advisory, and a market value near $773 million.
For investors focused on short term cash and yield, Alerus Financial brings something different to this screen. Its role in cash style deposits, paired with fee driven retirement and wealth arms, sets up a business model that does not rely only on the rate spread story.
"Continued build out of retirement and benefit services, where fee income represented more than 40% of total revenue in recent quarters and is supported by assets under administration and low cost deposits such as HSA balances, is expected to provide a recurring, capital light revenue base that can smooth earnings through different rate cycles."
The real test comes if a single assumption about how that fee mix and short duration funding behave under persistent higher rates starts to shift.
If that assumption is starting to wobble, the full narrative for Alerus Financial outlines how Alerus Financial could see fee momentum decoupling from rate moves and what might accelerate next.
Seeking Alternatives Before Momentum Flies
Fresh stock ideas can start breaking out while most investors stay focused on yesterday’s moves. Use curated screeners before the crowd notices, while it matters, and get in early.
- Scan a curated group of potential 8 dividend fortresses built for investors who prioritise income that can keep paying even when prices drop.
- Target fast moving themes in software, chips, and data centers with a focused set of 92 AI infrastructure stocks before institutional money finishes pricing in the next leg of demand.
- Look for potential long-term compounders among a hand picked 32 resilient stocks with low risk scores list so you can focus on sturdier balance sheets while others focus on headline noise.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com