


- First Orion announced the expansion of its partnership with Vodafone Group in late September 2026, rolling out INFORM Branded Calling for enterprise customers on Vodafone’s network in Ireland using the same CAMARA-based API already live in Germany and the UK.
- The wider European footprint for branded calling gives Vodafone another tool to deepen relationships with cross border corporate clients and support higher value digital communication services built directly on its existing network infrastructure.
- We will now look at how Vodafone's growing Europe wide branded calling platform could influence the broader investment narrative around digital services.
Scan Vodafone Group’s push into branded calling in comparison with other telecom opportunities and see which operators are quietly building similar network-based services through our 43 power grid technology and infrastructure stocks
Vodafone Group Investment Narrative Recap
To own Vodafone Group, you need to believe that heavy lifting in restructuring and German operational fixes eventually supports steadier earnings from a large, mostly recurring connectivity base, with higher margin digital services adding some extra fuel. The branded calling rollout fits that story, but on its own it does not change the near term picture in a big way.
The key short term swing factor is still execution in Germany and the wider restructuring program, which carries cost and integration risk at a time when Vodafone is unprofitable and carries meaningful debt. Branded calling helps the digital services narrative, although it does not remove pressure from weak service trends in that core market.
The most relevant recent development alongside branded calling is Vodafone's portfolio clean up, including the sale of assets in Italy and earlier divestments such as Vantage Towers and Spain. These deals increase financial flexibility at a moment when the group is trying to fund network upgrades, improve customer experience and support products like INFORM Branded Calling across Europe.
Extra liquidity can support capital spending in Germany, fiber build outs and enterprise focused offerings such as cloud and IoT, which are important potential catalysts for any improvement in margins and future earnings. The risk is that restructuring complexity, weaker German performance and high leverage dilute the benefit of asset sales, leave returns on that new spending under scrutiny and keep the investment case for Vodafone tied to disciplined execution rather than new product headlines.
Vodafone Group's current loss of €289.0 million is set against analyst expectations for earnings of €3.3 billion by 2029. This implies an earnings swing of about €3.6 billion, supported by an assumed 5.3% yearly increase in revenue and a forecast top line of €47.3 billion in that same year.
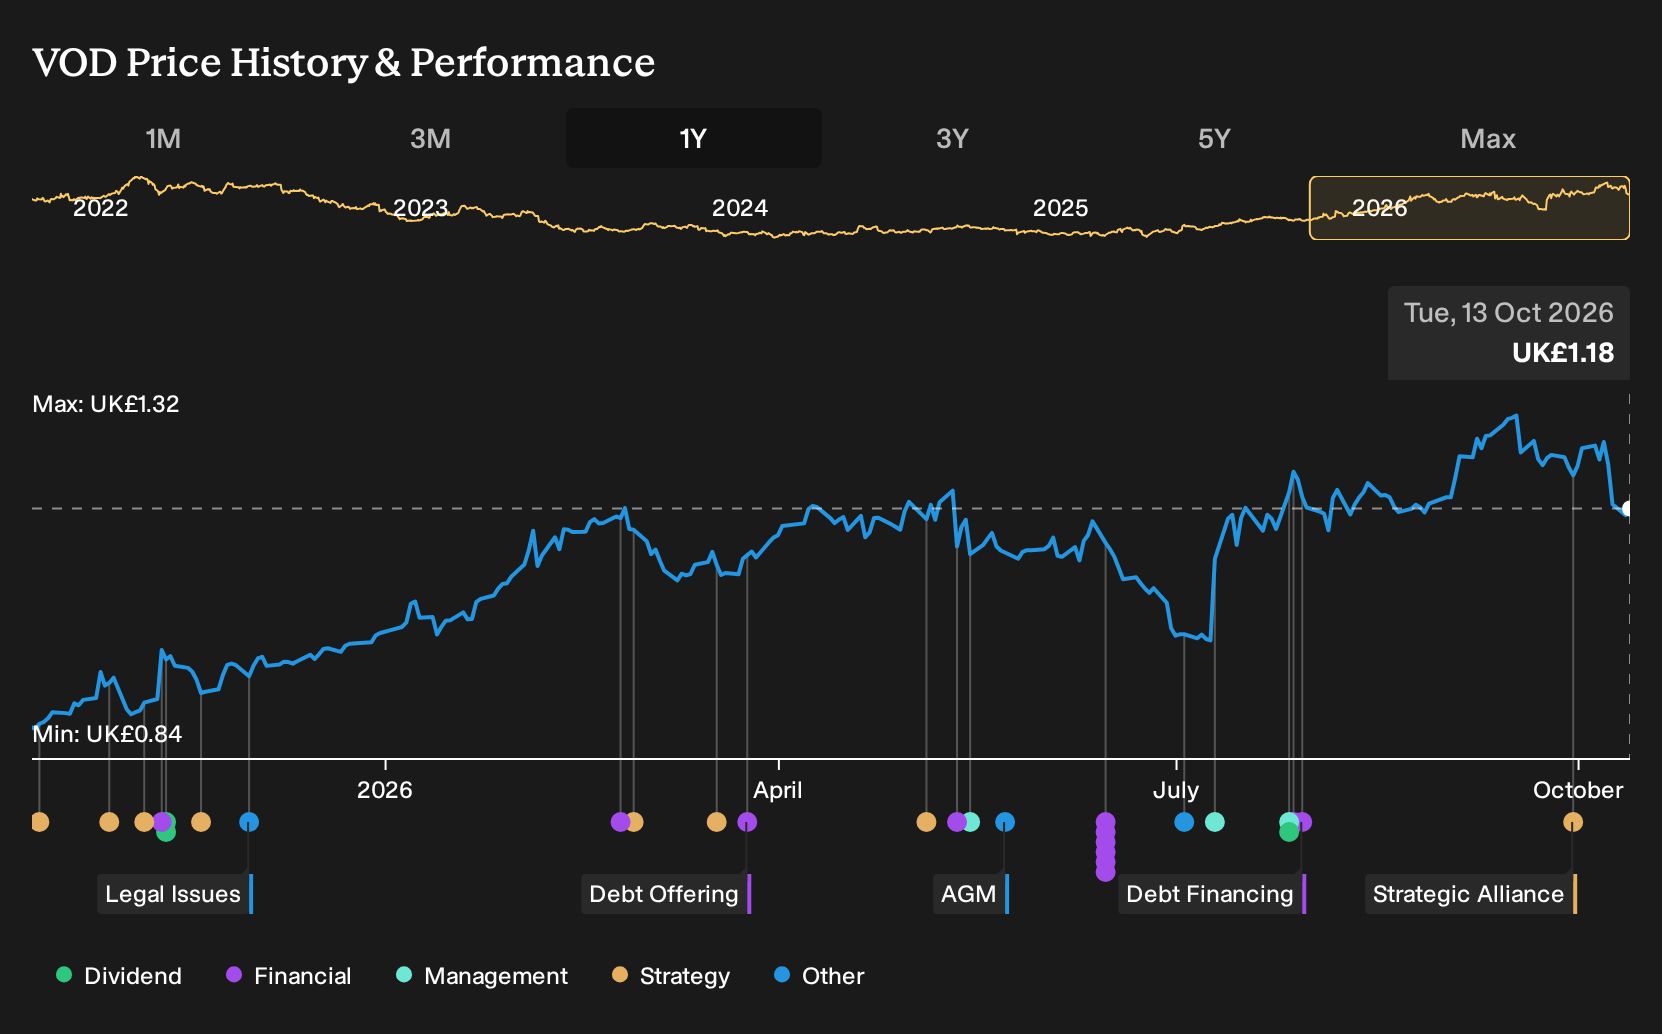
Uncover why Vodafone Group's fair value indicates a 4% potential upside to its current price. This discount may not last if sentiment turns.
Exploring Other Perspectives
Some of the most optimistic Vodafone analysts think digital services like branded calling could matter far more than today’s consensus narrative suggests. Before this Ireland launch, the bullish camp was already pencilling in €50.1b of revenue and €4.5b of earnings by 2029. You can compare that view with others and decide which story feels more realistic as this rollout evolves.
Explore 4 other Vodafone Group fair value estimates, including one that suggests potential upside of as much as 215% from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Vodafone Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Vodafone Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vodafone Group's overall financial health at a glance.
Looking for more Vodafone Group investment ideas beyond telecoms?
If the Vodafone Group story has sharpened your thinking, it can help to line it up against other opportunities and see where the risk, income and balance sheet profiles differ. The Simply Wall St Screener lets you do exactly that, filtering for traits that match how you prefer to invest rather than forcing every decision through a single narrative.
- If you want potential value with quality traits, start by checking companies that appear mispriced on fundamentals through our 8 high quality undervalued stocks.
- If income matters more to you than headline growth, focus on businesses that pair higher yields with stronger balance sheets using the 2 dividend fortresses.
- If capital preservation comes first, narrow your universe to sturdier companies with steadier profiles through the 4 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com