


Norwegian Cruise Line Holdings has seen its share price fall sharply over recent years, and with fresh financing moves now in play, the real question for investors is whether the current valuation lines up with what the business earns.
- Over the past 5 years, the stock has declined 40.2%, which puts the focus squarely on whether the market is now pricing Norwegian Cruise Line mainly on its earnings power rather than on past setbacks.
- The proposed US$750 million senior notes due 2031, aimed at refinancing existing debt, may support interest costs and cash flow timing, which feeds directly into how sustainable earnings look at today's share price.
- Your read on Norwegian Cruise Line Holdings is one view; the desks covering it have another. See what analysts think Norwegian Cruise Line Holdings's shares could be worth.
The issue now is whether Norwegian Cruise Line Holdings' recent share price around US$15.32 is justified by the earnings the company is generating today.
If you care about whether Norwegian Cruise Line Holdings' US$15.32 share price lines up with its earnings, a focused screen of 32 high quality undervalued stocks is a useful second reference point.
Is Norwegian Cruise Line Holdings Still Cheap on Earnings?
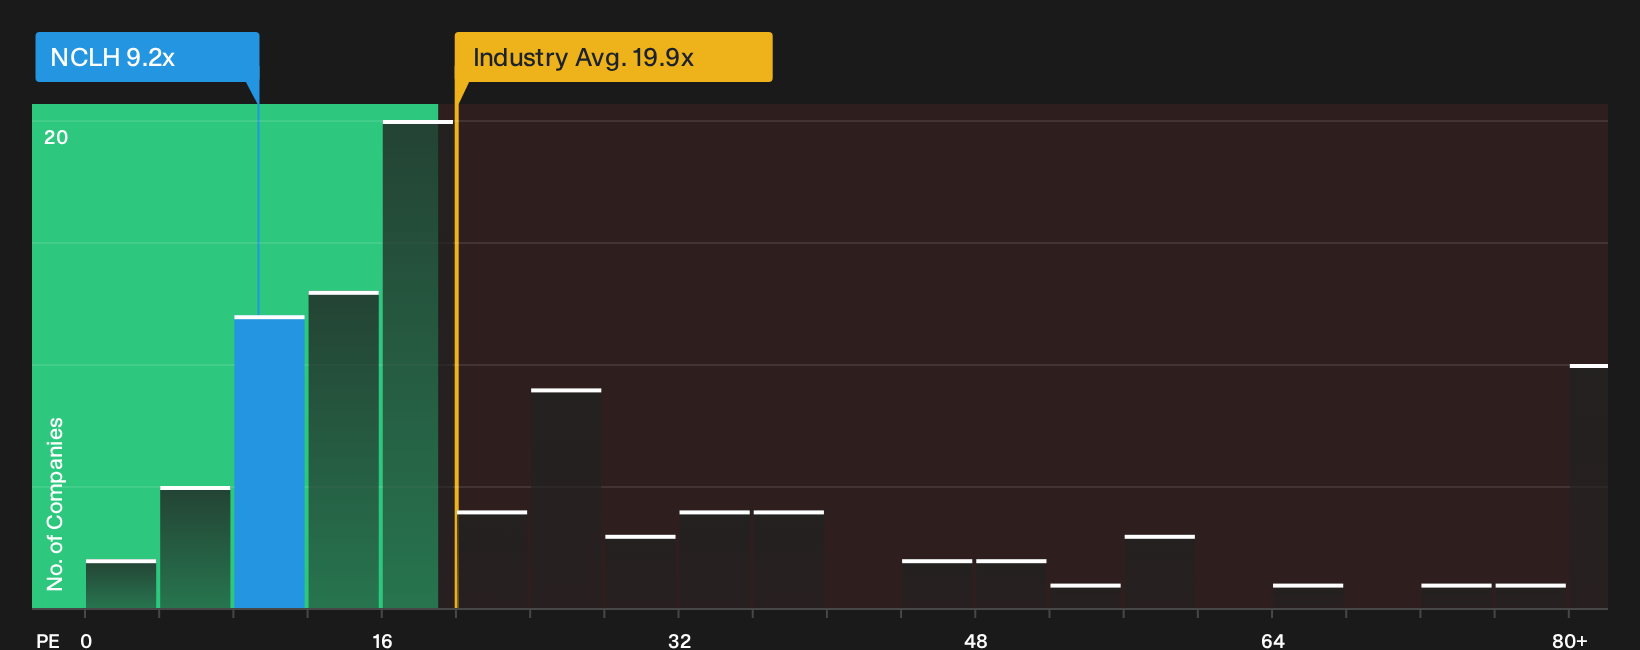
The P/E ratio is a useful yardstick here because Norwegian Cruise Line Holdings is being judged heavily on how much profit it can earn relative to its sizeable debt load. On this metric, the shares trade at about 9.2x earnings, which is well below the hospitality sector average of roughly 19.9x and also far under a peer group level near 45.5x.
Based on the tailored fair-value framework, which considers Norwegian Cruise Line Holdings' growth profile, profitability, size and risk, the current P/E sits at a discount to where the model would typically place the stock. Because the recent US$750 million refinancing plan targets interest costs and balance sheet pressure, the market is pricing the stock below that implied multiple despite the effort to improve finances. For investors, the low P/E versus both the sector and this fair-value yardstick points to a market that is still cautious about the business even as earnings begin to matter more than past setbacks. Explore the numbers behind Norwegian Cruise Line Holdings's P/E valuation.
The Norwegian Cruise Line Holdings Narrative: What Would Justify Today's Price?
Narratives for Norwegian Cruise Line Holdings pick up where the P/E debate leaves off by spelling out what kind of future growth, margins and earnings power would need to show up for the stock to be worth significantly more or materially less than today. They sit on Simply Wall St's Community page so you can see the reasoning behind each view. Rather than leaning on a single multiple or one model output, each Narrative lays out its own fair value assumptions so you can compare those inputs with the company’s actual results over time.
The community is split on Norwegian Cruise Line Holdings, with one camp seeing meaningful upside and another arguing the turnaround work is already in the price.
Bull case: 24% undervalued
"Structural SG&A and marketing savings, including more than US$500m of identified cost actions since 2024 and an expected 15% reduction in salary and benefits, are already reflected in lower adjusted NCC ex fuel guidance and provide a foundation for future net margin and EPS improvement if revenue stabilizes..."
Discover why this Narrative puts Norwegian Cruise Line Holdings at 24% undervalued.
Bear case: 18% overvalued
"Repeated cuts to 2026 net yield guidance and expectations for net yield to fall around 5% for the year, with declines of about 8.9% in Q3, 6.5% in Q4 and further pressure into H1 2027, point to a scenario where cost initiatives are overwhelmed by weaker pricing and leave EBITDA margins and earnings below what current forecasts imply..."
Explore why this Narrative puts Norwegian Cruise Line Holdings at 18% overvalued.
Norwegian Cruise Line Holdings has risk checks that deserve your attention
Before you lean too heavily on any earnings multiple or valuation gap for Norwegian Cruise Line Holdings, it is worth pausing to see what the underlying risk checks are flagging and how they might affect your thesis. Take a closer look at 1 major warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com