


BYD has seen its share price fall sharply over the past year, and the slide raises a straightforward question for investors who care about valuation. Is the current Hong Kong listing price of HK$72.85 still aligned with what the group is earning from its electric vehicles, batteries and related businesses.
- The share price is down 32.6% over the past year, which puts the focus firmly on whether that move has brought the earnings multiple closer to, or further away from, what looks reasonable against Fair Ratio.
- Recent headlines around global sales growth, aggressive European expansion and fresh model launches suggest earnings expectations may be shifting, with knock on effects for how much investors are prepared to pay for each unit of profit.
- Your read on BYD is one view; the desks covering it have another. See what analysts think BYD's shares could be worth.
The issue now is whether BYD's current valuation can be justified by its earnings power today and what those profits may reasonably support over time.
If you want to stress test the same earnings based valuation question beyond BYD, it is worth lining up its recent slide against 186 high quality undervalued stocks.
Does BYD Look Pricey on Earnings?
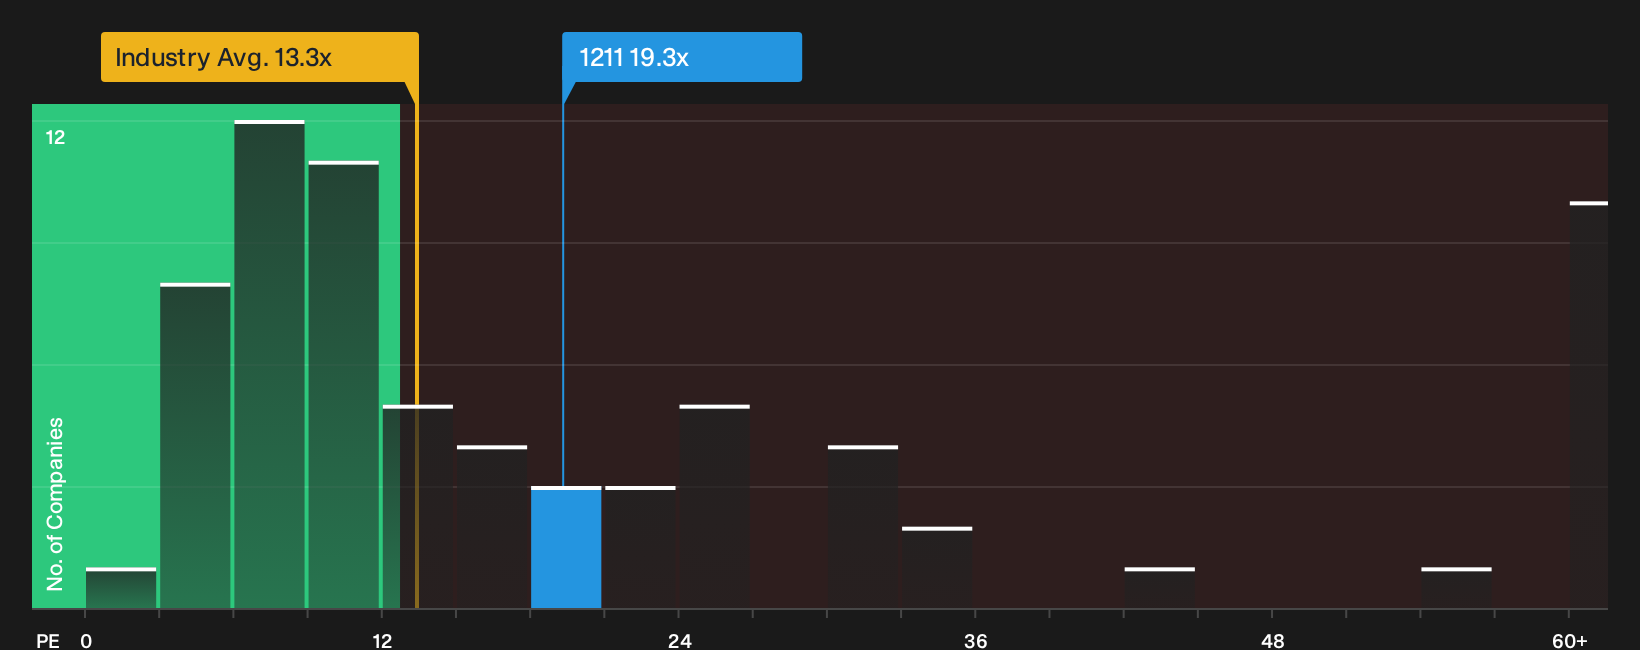
The P/E ratio is a useful lens for BYD because earnings remain a key anchor for how investors frame the business, even with its battery and EV exposure. BYD trades on a P/E of 19.3x, which is above the Auto industry average of 13.5x and slightly below the peer group on 21.2x. On this metric alone, the stock changes hands at a richer multiple than the broad sector while not looking especially cheap next to closer listed rivals in the segment.
That premium looks stretched once you compare it with the Fair Ratio, which is the multiple you might expect for BYD after factoring in its recent profitability, scale, capital intensity and risk profile. Despite the recent headlines about overseas sales growth and a heavier push into Europe, the current P/E still screens as overvalued against that tailored yardstick. This leaves investors relying on their own conviction about the durability of those earnings to bridge the gap. Explore the numbers behind BYD's P/E valuation.
The BYD Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E discussion leaves off by spelling out which paths for BYD's growth, margins and earnings would make today's valuation look stretched or restrained. Each narrative lays out the assumptions behind its own idea of fair value, so you can see them in one place and then compare those expectations with BYD's actual reported numbers as new results arrive.
One of the top community narratives on BYD: 52% undervalued
BYD is no longer just competing on price. They are competing on intelligence and longevity, while Tesla grapples with hardware fragmentation and a shifting pricing model…
Discover why this Narrative puts BYD at 52% undervalued.
One more piece of the BYD puzzle investors are missing
The current P/E tells you what the market is paying for BYD today, but not how professional analysts see its profits a few years from now, or how that compares with this valuation. Explore where analysts expect BYD to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com