


Artisan Partners Asset Management shares have fallen sharply this year, and the drop raises a straightforward question for investors who follow the stock. Is the current price of around US$31 putting a fair tag on the earnings power of this asset management business or not?
- The share price is down 24.5% year to date. This puts the spotlight firmly on whether the earnings behind Artisan Partners Asset Management still support today’s valuation.
- The group earns its money by charging fees on client assets. Trends in assets under management, fee rates and operating costs can therefore heavily influence how much profit ultimately backs each share.
- The analysts covering Artisan Partners Asset Management have run their own numbers. See what analysts think Artisan Partners Asset Management's shares could be worth.
The issue now is whether the recent share price slump leaves Artisan Partners Asset Management trading at a level that is well aligned with its earnings power or not.
If you want a broader watchlist while you assess whether Artisan Partners Asset Management’s earnings support today’s price, a focused stock screen built around 32 high quality undervalued stocks can be a useful starting point.
Is Artisan Partners Asset Management a Bargain on Earnings?
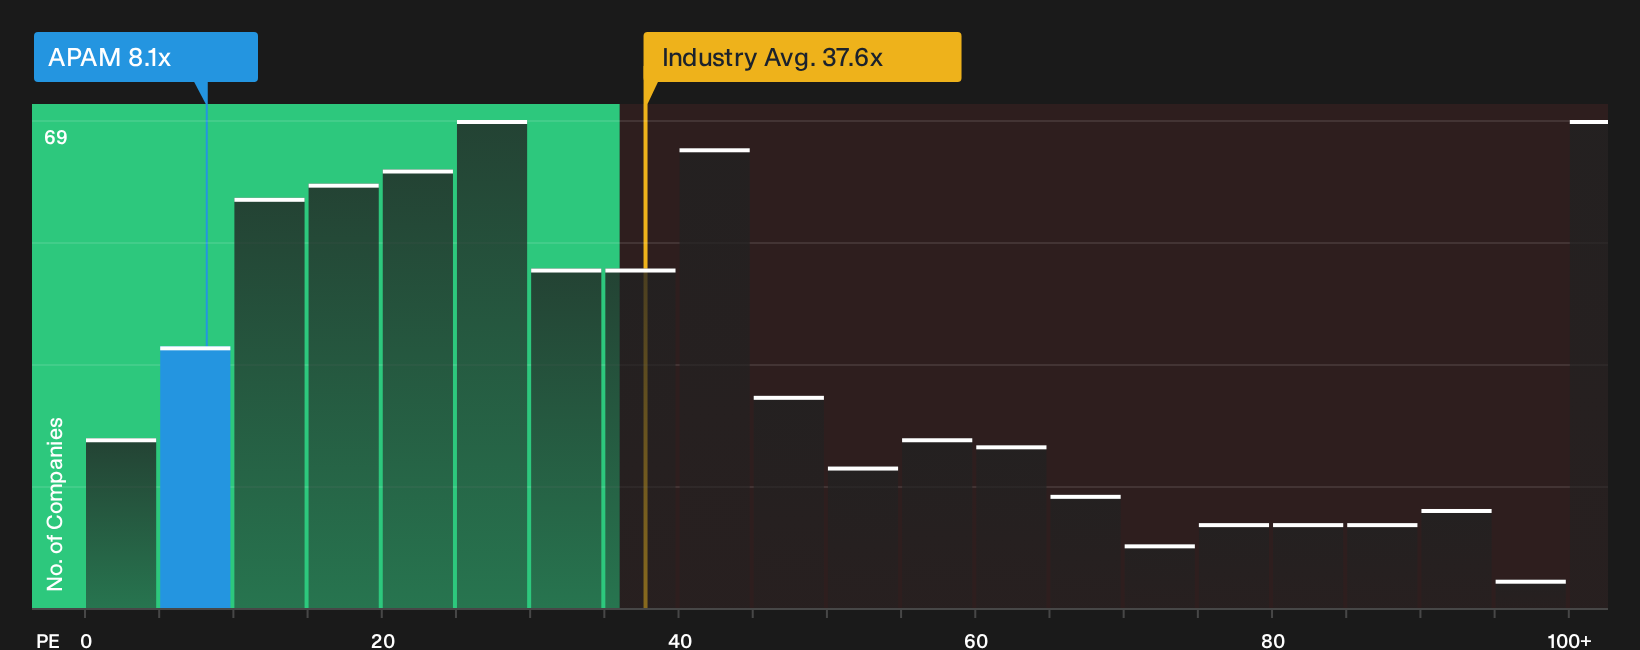
The P/E ratio fits Artisan Partners Asset Management well because earnings are a central yardstick for an asset manager that charges fees on client capital. On that measure, the stock trades on a P/E of 8.1x, against a Capital Markets industry average of 37.6x and a peer group sitting around 19.7x. That is a wide gap between what the market pays for Artisan’s earnings and what it pays for profits at comparable businesses.
A tailored fair value framework, which factors in Artisan Partners Asset Management’s profitability profile, business mix, size and risk, points to a higher P/E than the one currently implied by the share price. The present 8.1x multiple sits below that modelled range and signals that the market is pricing the company’s earnings at a discount to what this framework suggests. For investors, the key question is whether that gap reflects overlooked earnings power or embedded concerns that are not fully captured in the numbers. Explore the numbers behind Artisan Partners Asset Management's P/E valuation.
The Artisan Partners Asset Management Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take the valuation puzzle around Artisan Partners Asset Management and outline the different paths for future earnings, fee margins and client asset levels that would need to occur for the shares to appear materially cheaper or more expensive than they are today. Rather than leaving you with a single output from a ratio or model, they map the future assumptions that figure relies on so you can see how Artisan Partners Asset Management's real-world progress aligns with that story on the Community page.
One of the top community narratives on Artisan Partners Asset Management: 18% undervalued
"Expansion into more investment teams and strategies may strain resources and increase operational costs, impacting net margins..."
Discover why this Narrative puts Artisan Partners Asset Management at 18% undervalued.
One more Artisan Partners Asset Management check that belongs beside the valuation work
Price tags and earnings multiples only tell part of the story for Artisan Partners Asset Management, since separate risk checks have flagged specific issues that investors may want to review before drawing their own conclusion. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com