


ESR-REIT (SGX:9A4U) drew attention after securing a ¥7.10b sustainability-linked unsecured term loan facility from Malayan Banking's Singapore Branch. Investors are weighing this funding move against the trust's current unit price performance.
Recent trading tells a different story to the funding headline. ESR-REIT’s unit price is at SGD2.04, with the 30-day share price return down 7.27% and the year-to-date share price return down 25.27%, while the 1-year total shareholder return has declined 20.92%. This points to fading momentum even as the new sustainability-linked loan signals lenders’ confidence in its balance sheet and future project pipeline.
Scan beyond ESR-REIT’s recent loan deal and unit price weakness by sizing it up against a curated 187 high quality undervalued stocks that share strong fundamentals and potential value gaps.
ESR-REIT now trades at a steep discount to both analyst targets and intrinsic estimates, even after securing fresh sustainability-linked funding. Is this a valuation gap, or a fair reflection of rising risk?
Preferred Price-to-Earnings of 98.7x: Is It Justified?
ESR-REIT may look cheap against analyst targets and SWS DCF estimates, but the P/E ratio of 98.7x tells a very different story when you line it up against its recent earnings profile.
The P/E ratio compares the current unit price to earnings per unit. For an industrial REIT like ESR-REIT, this figure signals how much investors are willing to pay today for each dollar of profit. A high multiple often reflects strong confidence in earnings quality or growth, while a lower figure can point to either cautious expectations or already mature income streams.
Here, the current P/E of 98.7x is far higher than the Asian Industrial REITs industry average of 15.6x. It also sits well above the estimated fair P/E of 24.5x implied by the fair ratio model. That gap suggests the market valuation could move closer to a level that reflects more typical sector pricing and the underlying earnings profile.
Explore the SWS fair ratio for ESR-REIT.
Result: Price-to-Earnings of 98.7x (OVERVALUED)
Still, ESR-REIT faces pressure from its declining 1-year and 5-year total returns, and any further revenue contraction could quickly challenge the current valuation story.
Find out about the key risks to this ESR-REIT narrative.
Another View On ESR-REIT’s Value
The P/E of 98.7x screams expensive, yet the SWS DCF model points the other way. On this cash flow view, ESR-REIT at SGD2.04 trades at roughly a 50.8% discount to an estimated value of SGD4.15. That shifts the question from price tag to timing. What would need to change for the gap to narrow?
For readers who want to see how that cash flow view is built step by step, Look into how the SWS DCF model arrives at its fair value.
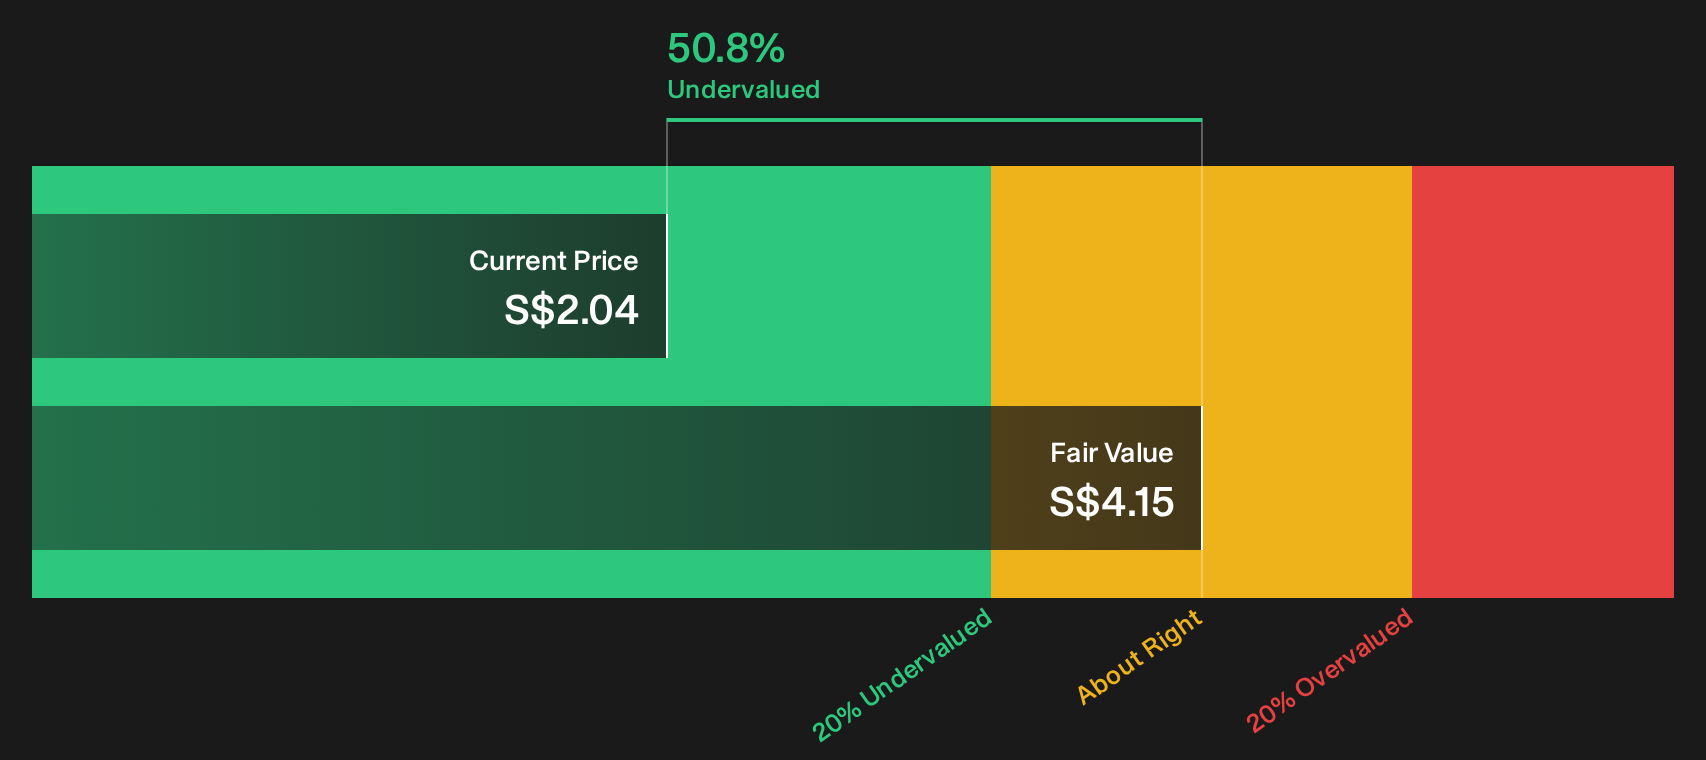
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ESR-REIT for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 187 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted about what all this means for ESR-REIT right now? Take a closer look at the numbers, weigh the trade offs, then ground your view in the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond ESR-REIT?
Do not leave your next move to chance. Use targeted stock lists to filter the noise, focus on quality, and keep your watchlist working harder for you.
- Zero in on potential mispricings by scanning a curated 187 high quality undervalued stocks that combine strong fundamentals with possible upside gaps.
- Prioritise resilience by checking a 224 resilient stocks with low risk scores that score well on stability so your portfolio is not leaning on fragile stories.
- Get ahead of the crowd by reviewing a 616 high quality undiscovered gems that pair quality metrics with limited current attention from the broader market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com