


With a market cap of $86.8 billion, Howmet Aerospace Inc. (HWM) is a leading global provider of advanced engineered solutions for the aerospace and transportation industries. Operating through four key segments: Engine Products; Fastening Systems; Engineered Structures; and Forged Wheels, the company serves customers worldwide with high-performance components and systems.
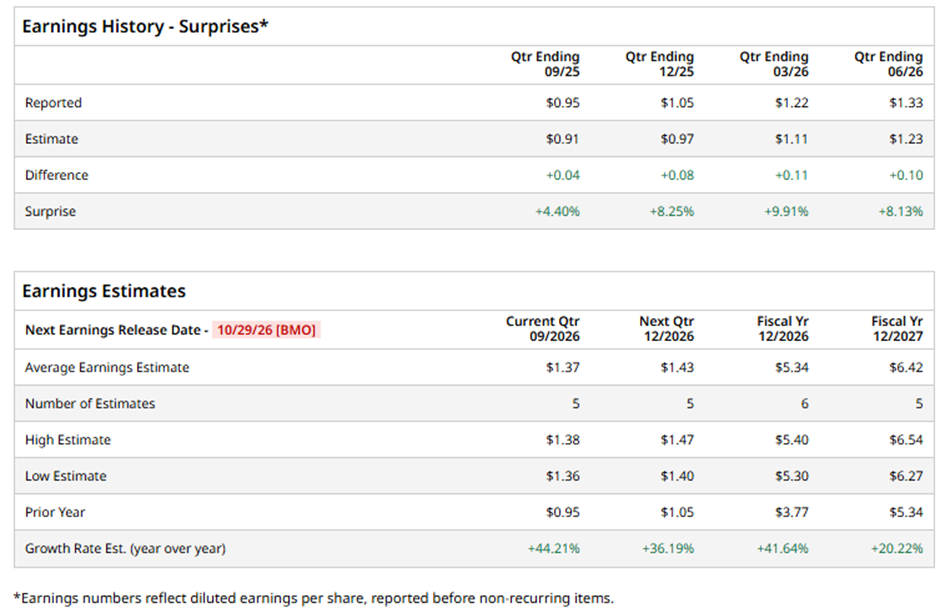
The Pittsburgh, Pennsylvania-based company is expected to release its fiscal Q3 2026 results before the market opens on Thursday, Oct. 29. Ahead of this event, analysts project HWM to report an adjusted EPS of $1.37, a 44.2% growth from $0.95 in the year-ago quarter. The company has exceeded Wall Street's bottom-line estimates in each of the last four quarters.
For fiscal 2026, analysts forecast the maker of engineered products to post adjusted EPS of $5.34, up 41.6% from $3.77 in fiscal 2025.
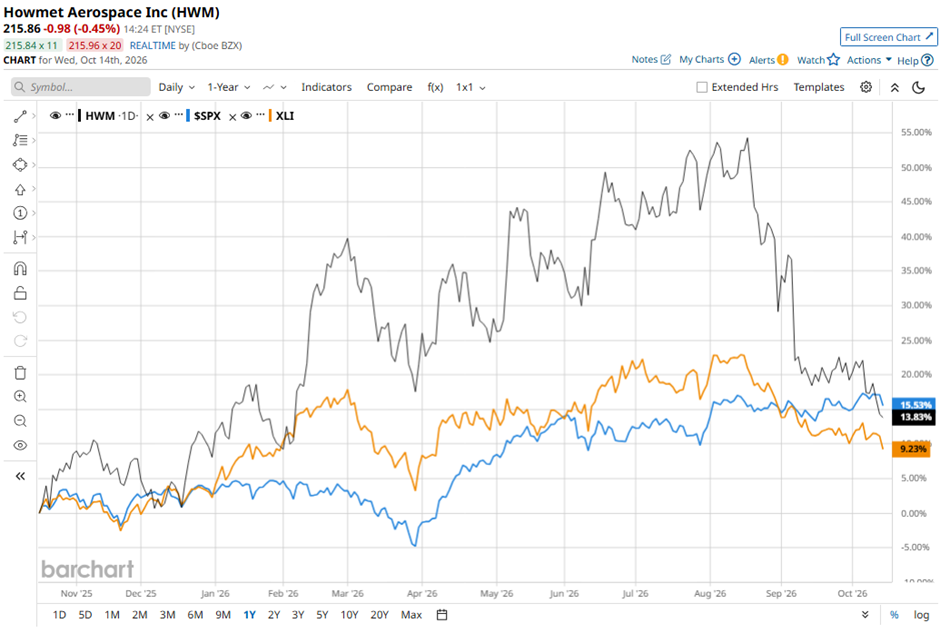
HWM stock has climbed 12.4% over the past 52 weeks, lagging behind the broader S&P 500 Index's ($SPX) nearly 16% return. However, the stock has outpaced the State Street Industrial Select Sector SPDR ETF's (XLI) 8.6% gain over the same period.
Howmet Aerospace reported Q2 2026 results on Aug. 6. The company raised its 2026 adjusted EPS forecast to $5.23 - $5.31 and revenue guidance to $10 billion - $10.1 billion, driven by robust demand for aerospace parts as Boeing and Airbus increase jet production. Q2 adjusted EPS jumped 46% to $1.33 and revenue rose 24% to $2.55 billion, beating the estimates, supported by stronger aircraft demand and growing sales of gas-turbine blades for data centers.
Rising widebody production, anticipated increases in Boeing 787 and Airbus A350 output, higher fastener prices, and data-center-related power-generation projects expected to support growth through 2030 further strengthened the outlook.
Analysts' consensus view on HWM stock is bullish, with a "Strong Buy" rating overall. Among 24 analysts covering the stock, 19 suggest a "Strong Buy," one gives a "Moderate Buy," and four provide a "Hold" rating. This configuration is slightly more bullish than three months ago, with 18 analysts suggesting a "Strong Buy."
The average analyst price target is $319.50, suggesting a potential upside of 48% from current levels.
On the date of publication, Sohini Mondal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.