


It’s not the 322% revenue growth that catches your eye in Applied Digital's (APLD) recent earnings, but how the company plans to turn today’s AI infrastructure demand into decades of revenue.
The AI boom could last for years; thus, Applied Digital is building its business around a much longer horizon. The company wants to develop data centers that remain useful through multiple generations of computing hardware, backed by long-term contracts with major technology customers. Its recent fiscal first-quarter earnings call offered a closer look at how it plans to turn that vision into recurring revenue.
Applied Digital is Building Data Centers for More Than One AI Cycle
While investors are fixated on how AI infrastructure companies are performing today, the bigger question is how they plan to turn today's demand into revenue and profits for years to come. And that’s what Applied Digital’s strategy is all about. Applied Digital builds large data center facilities to support high-performance computing and AI workloads. It understands that AI data centers are expensive to build. So, it wants them to last long enough to pay off for decades, not just one generation of chips. Its strategy rests on long-term leases, adaptable facilities, access to power, and the ability to expand campuses customers already use.
During the fiscal Q1 earnings call, CEO Wes Cummins said the company designs its AI facilities for a useful life of more than 30 years, compared with the typical five- to six-year life cycle of a GPU generation. The company says its designs can accommodate changes in computing architecture, network configurations, power density, and cooling requirements. This should allow customers the flexibility to just upgrade their equipment instead of Applied Digital replacing an entire facility. It could then continue leasing the same infrastructure as tenants refresh their hardware.
15-Year Leases Provide the Revenue Foundation
Then comes the second part of its strategy. Applied Digital also wants customers to commit to using its facilities for extended periods. The company targets take-or-pay leases with base terms of at least 15 years, primarily with established, investment-grade hyperscalers. The structure will include customers committing to contractual payments rather than simply paying for whatever capacity they happen to use. These agreements can therefore provide greater visibility into future revenue than short-term arrangements.
In the first quarter, Applied Digital reported $36 billion in contracted revenue tied to five campuses located across three states. This is a substantial backlog, but this is also not collected revenue. Construction schedules, contractual conditions, and the timing of customer payments will determine when this turns to reported revenue.
Applied Digital is also aiming at its existing campuses to generate more value. It wants to expand existing locations and secure additional agreements with customers already using its infrastructure. A data center manufacturing process already includes local restrictions, demanding zoning requirements, longer permit processes, and community opposition. Therefore, once a campus is established, it will be much easier to expand it rather than building a comparable facility from scratch. CEO Cummins mentioned the company’s plan to sign new leases for an additional 250 MW of data center capacity by the end of 2026, at prices more than 15% higher than its earlier agreements. The company may also negotiate longer contracts with its customers.
Charging higher prices could help Applied Digital earn more from its existing data centers without having to build entirely new facilities for every new deal. However, the 250 MW target is not yet a done deal. Investors will need to see the leases signed and their final terms confirmed before knowing how much these agreements could improve the company's revenue and profitability.
Revenue Is Growing Fast, but the Debt Load Remains
Applied Digital’s revenue in the first quarter grew a staggering 322% year-over-year (YoY) to $341.9 million. Its high-performance computing (HPC) segment generated $262.6 million, including $65.8 million in base rent and $183.5 million from tenant fit-out services. However, Applied Digital’s bottom line remains weaker. It reported a $221 million net loss as it continues investing heavily in data centers. The company ended the quarter with around $6.4 billion in debt, against $2.9 billion in cash and cash equivalents and another $700 million in restricted cash.
Although 80% of its debt principal is not due until fiscal 2031 or later, the debt load remains a concern. The company expects to finance new campuses using preferred equity followed by project-level debt, allowing it to fund construction while retaining majority ownership of each site. Investors need to watch financing costs, construction progress, and the company's ability to turn its contracted revenue into sustainable cash flow.
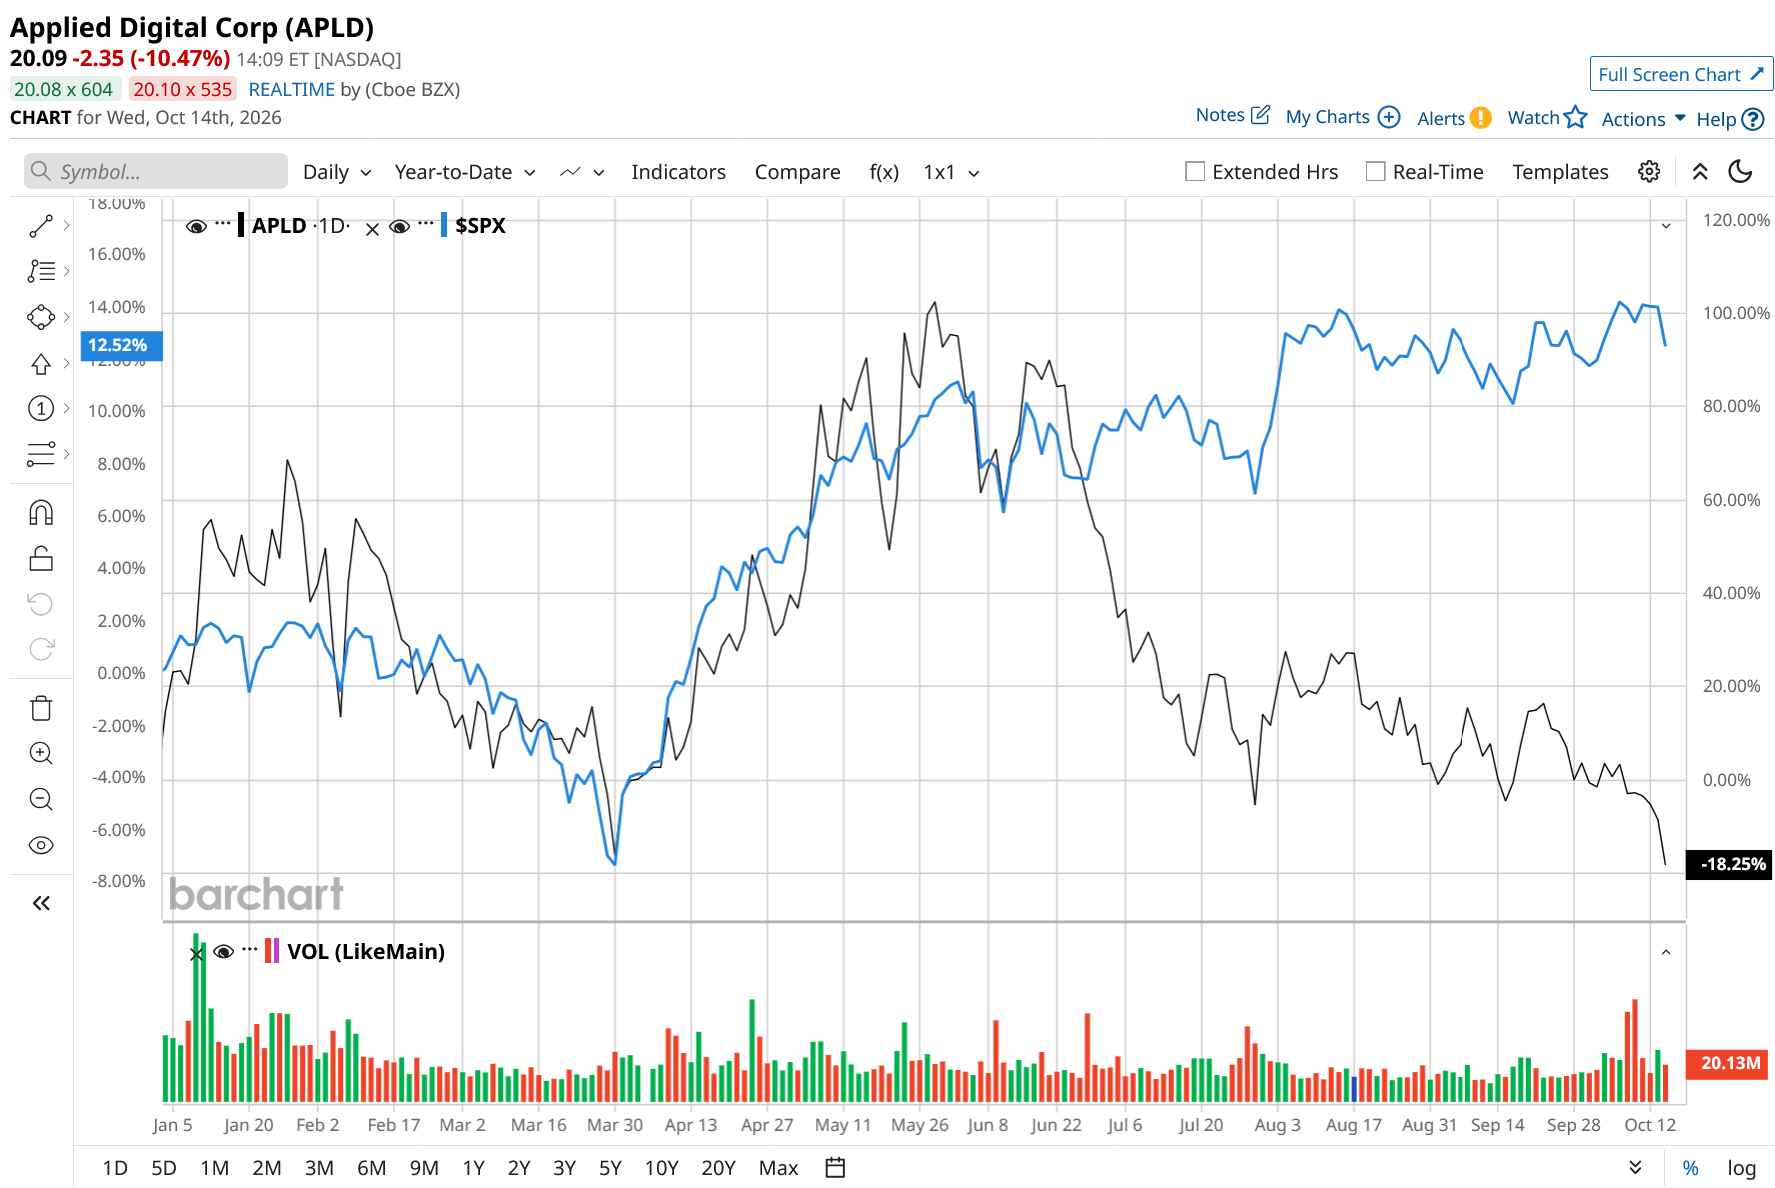
Despite another encouraging quarter and an ambitious long-term vision, investors remain unconvinced that Applied Digital can turn its growth plans into sustained financial returns. That skepticism is reflected in APLD stock’s 17% dip year-to-date (YTD), and today's steep 10% drop, as it continues to underperform the broader market.
What the Strategy Means for APLD Stock
Overall, Applied Digital has developed a strategy to convert today's AI infrastructure need into a much longer-term business. Its 15-year leases offer a foundation, and its 30-plus-year design horizon offers a longer-term vision. But renewals, premium pricing, power availability, and disciplined execution will ultimately determine how much of that potential ultimately reaches shareholders.
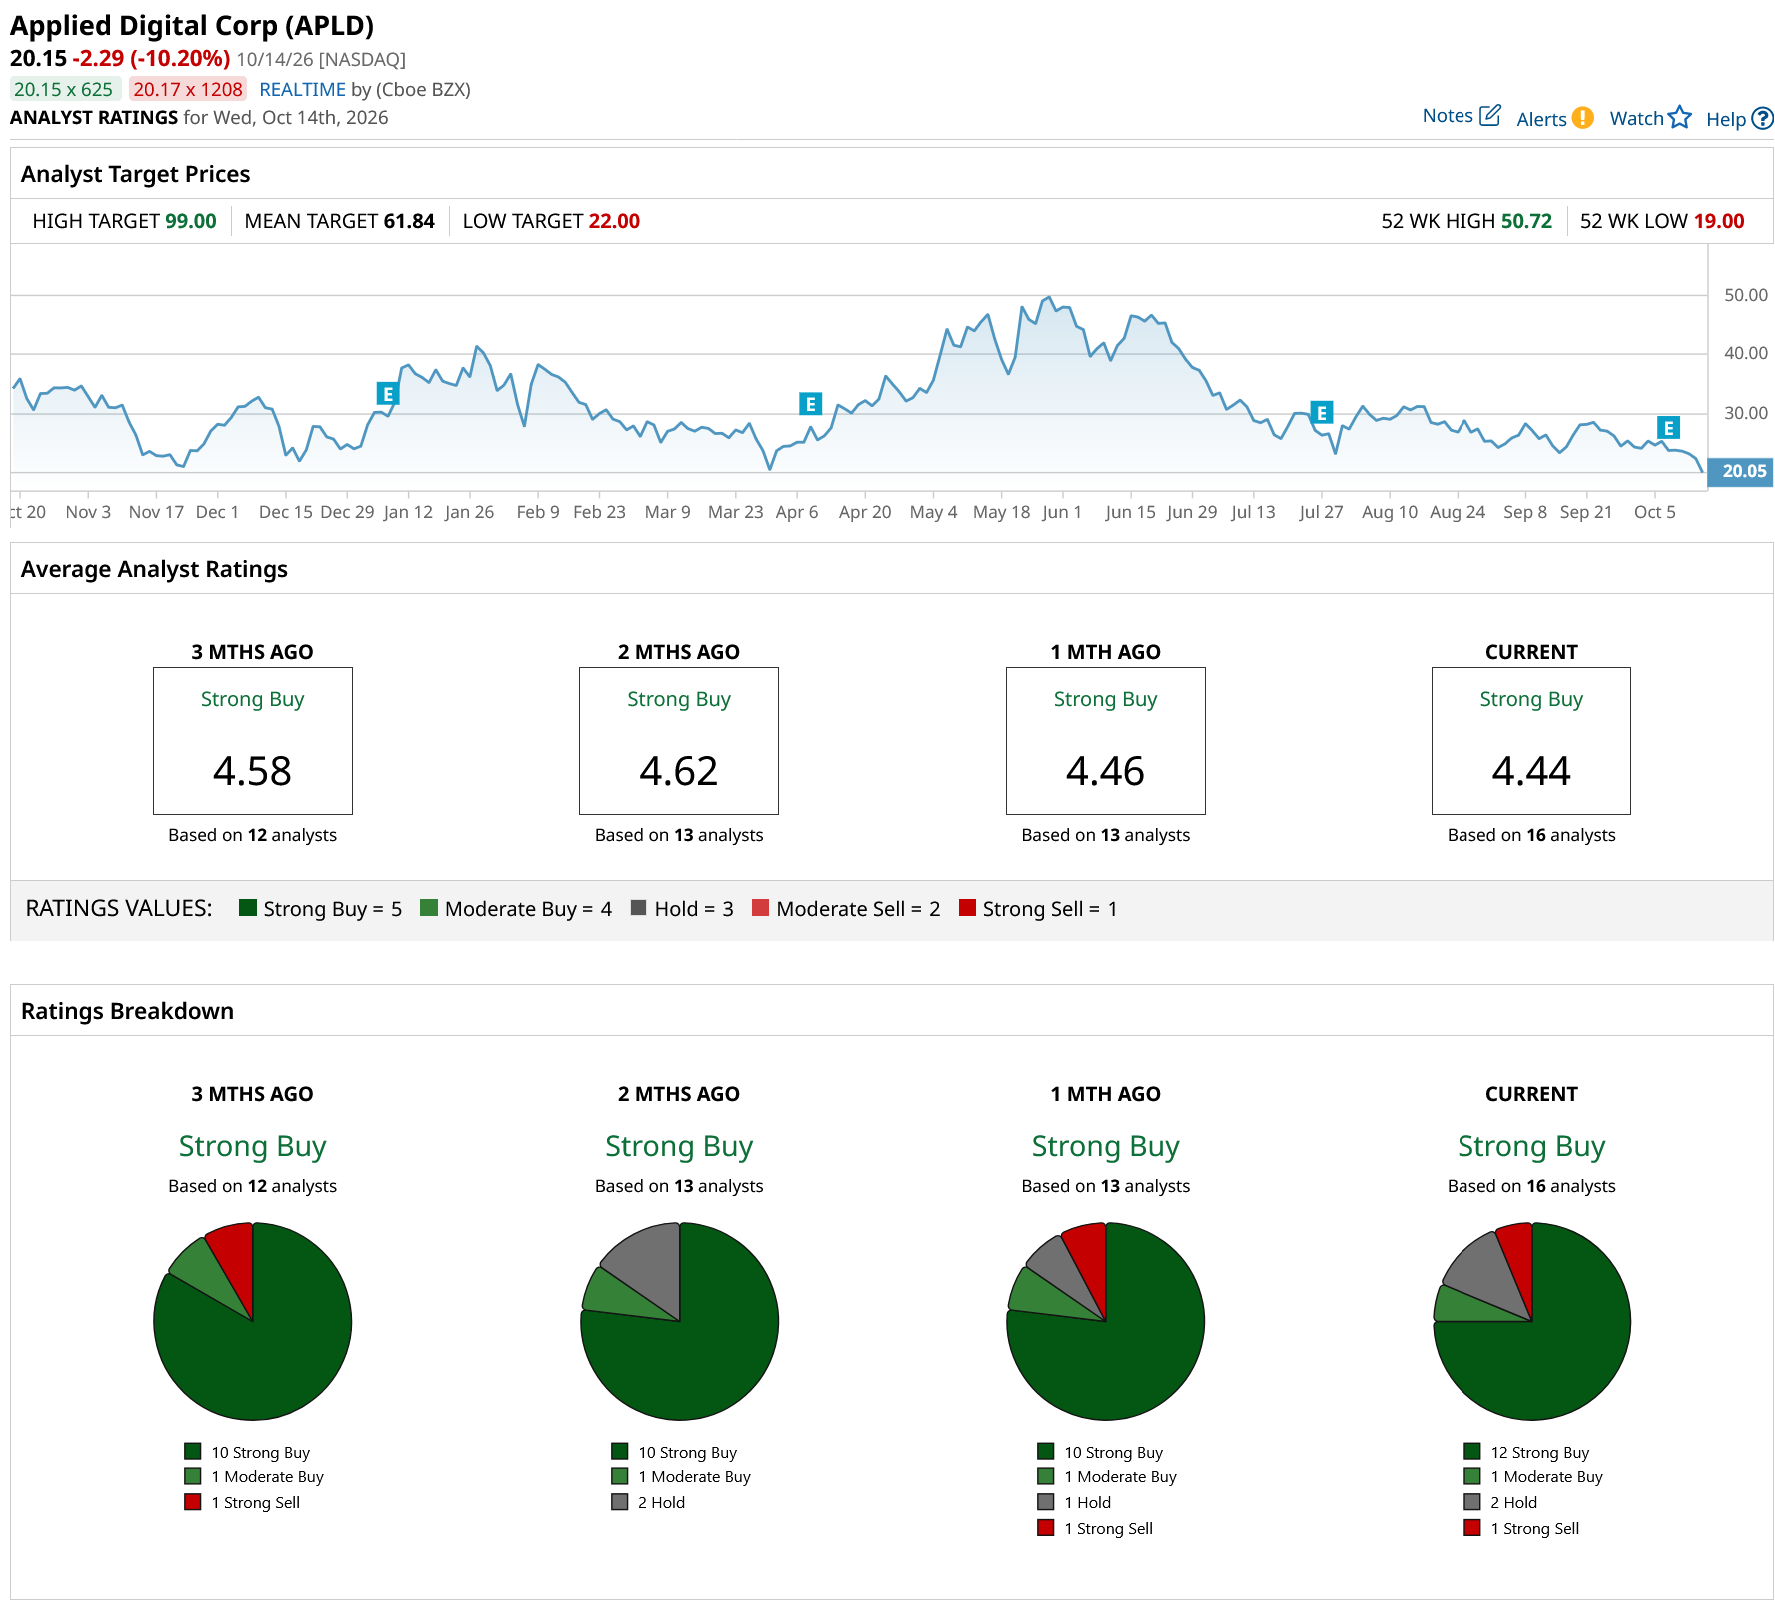
On Wall Street, APLD stock holds a consensus “Strong Buy” rating. The average target price of $61.84 implies the stock could climb by 207% over current levels. But the high price estimate of $99 implies an upside potential of 341% over the next 12 months. Of the 16 analysts covering the stock, 12 rate it a “Strong Buy,” one says it is a “Moderate Buy,” two rate it a “Hold,” and one recommends a “Strong Sell.”
On the date of publication, Sushree Mohanty did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.