


As the Australian market gears up for a potentially positive start to the week, investors remain cautious about bond yields and their impact on local shares. In this climate, penny stocks continue to attract attention for their potential value, even though the term may seem outdated. By examining those with strong financials and clear growth prospects, investors can uncover opportunities in smaller companies that might offer both stability and upside potential.
Let's review some notable picks from our screened stocks.
Corporate Travel Management (ASX:CTD)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: Corporate Travel Management Limited is a travel management solutions company that oversees the procurement and delivery of travel services across Australia, New Zealand, North America, Asia, and Europe with a market cap of A$364.01 million.
Operations: The company's revenue is derived from travel services across various regions, with A$61.71 million from Asia, A$113.45 million from Europe, A$310.18 million from North America, and A$180.52 million from Australia and New Zealand.
Market Cap: A$364.01M
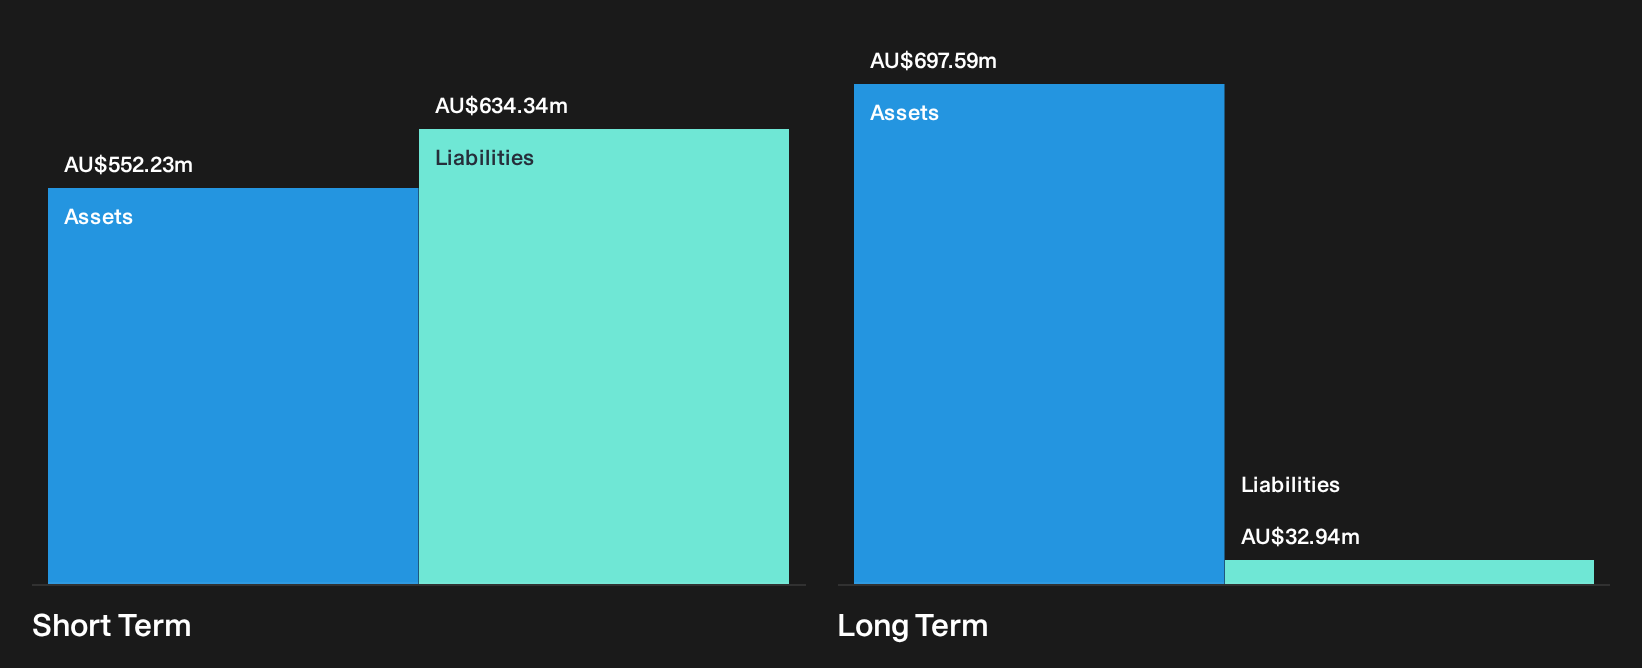
Corporate Travel Management Limited has demonstrated a significant turnaround, reporting A$17.7 million in net income for the year ended June 2026, compared to a substantial loss the previous year. The company operates without debt, easing financial pressures related to interest payments. However, short-term liabilities exceed short-term assets by A$82.1 million, presenting liquidity challenges. Despite this, its seasoned management and board provide stability and strategic direction. The stock trades significantly below estimated fair value and earnings are forecasted to grow annually by 28.23%, indicating potential for future growth amidst current operational improvements.
- Unlock comprehensive insights into our analysis of Corporate Travel Management stock in this financial health report.
- Learn about Corporate Travel Management's future growth trajectory here.
OM Holdings (ASX:OMH)
Simply Wall St Financial Health Rating: ★★★★☆☆
Overview: OM Holdings Limited is an investment holding company involved in the global mining, smelting, trading, and marketing of manganese ores and ferroalloys, with a market capitalization of A$156.69 million.
Operations: The company's revenue is primarily derived from its Smelting segment, which generated $465.84 million, and its Marketing and Trading segment, which contributed $654.79 million.
Market Cap: A$156.69M
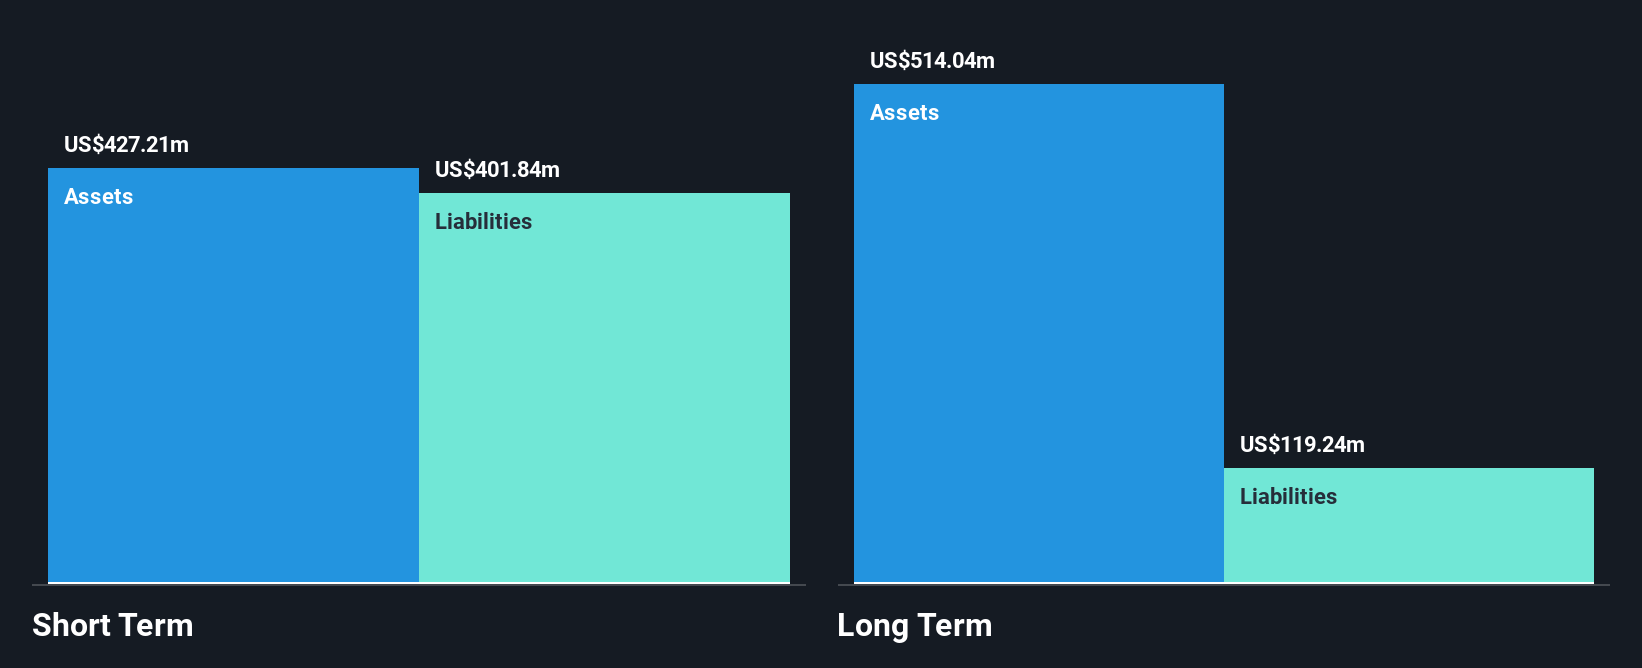
OM Holdings Limited reported a net income of US$26.32 million for the half year ending June 2026, marking a recovery from last year's loss. Despite this improvement, the company remains unprofitable overall and has seen earnings decline by an average of 51.5% annually over five years. Its operating cash flow is negative, indicating challenges in covering debt through cash generation, though its net debt to equity ratio is satisfactory at 31.4%. The board's extensive experience provides strategic oversight as OM Holdings navigates financial complexities, including interest coverage issues with EBIT at only 0.4 times interest payments.
- Click to explore a detailed breakdown of our findings in OM Holdings' financial health report.
- Gain insights into OM Holdings' past trends and performance with our report on the company's historical track record.
Vita Life Sciences (ASX:VLS)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: Vita Life Sciences Limited is a healthcare company that formulates, packages, distributes, and sells vitamins and supplements across Australia, Singapore, Malaysia, Thailand, Vietnam, Indonesia, and China with a market cap of A$156.25 million.
Operations: The company's revenue is primarily generated from its operations in Australia (A$43.35 million) and Malaysia & Singapore (A$46.33 million), with additional contributions from investments in China & Vietnam (A$6.35 million).
Market Cap: A$156.25M
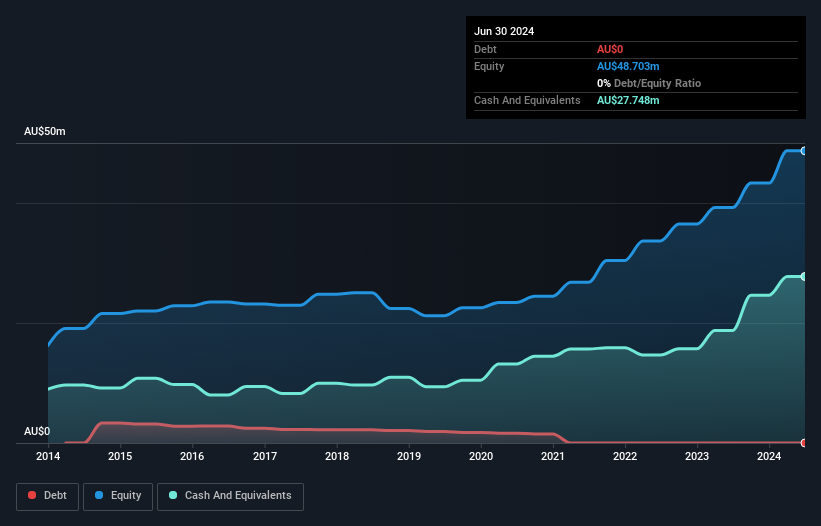
Vita Life Sciences Limited demonstrates financial stability with no debt and strong asset coverage for both short- and long-term liabilities. The company has shown consistent earnings growth, reporting a net income of A$5.56 million for the half year ending June 2026, up from A$4.84 million the previous year. Its return on equity is high at 20%, and it offers a reliable dividend yield of 4.84%. Despite significant insider selling recently, Vita Life Sciences remains undervalued by approximately 71.9% compared to its estimated fair value, providing potential investment appeal in the penny stock segment.
- Dive into the specifics of Vita Life Sciences here with our thorough balance sheet health report.
- Assess Vita Life Sciences' previous results with our detailed historical performance reports.
Where To Now?
- Navigate through the entire inventory of 412 ASX Penny Stocks here.
- Ready To Venture Into Other Investment Styles? These 25 companies survived and thrived after COVID and have the right ingredients to survive Trump's tariffs. Discover why before your portfolio feels the trade war pinch.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com