


Dividend reset and fresh guidance put Fast Retailing in focus
Fast Retailing (TSE:9983) has moved back into the spotlight after reporting full year earnings, sharply revising its dividend outlook and laying out new guidance for the year ending August 31, 2027.
Against this backdrop of fresh earnings and dividend news, Fast Retailing’s share price has climbed, with a 1-month share price return of 13.6% and a year to date share price gain of 32.63%. The 5-year total shareholder return of 216.86% points to strong long term momentum that recent guidance and the dividend reset appear to have reinforced rather than reversed.
Scan how Fast Retailing’s dividend reset and earnings jump compare with other companies that prioritize both growth investment and shareholder payouts by running through the 28 dividend fortresses
Fast Retailing now trades sharply higher after the dividend reset, while analyst targets and intrinsic estimates point in different directions. Where does a reasonable fair value range actually land within that spread?
Price-to-earnings of 42.9x: Is it justified?
Fast Retailing now changes hands at a rich valuation, with a P/E of 42.9x against a last close of ¥75,840 that already reflects strong recent gains.
The P/E ratio compares the current share price to earnings per share. For a retailer like Fast Retailing with a global footprint across UNIQLO Japan, UNIQLO International, GU and other brands, this metric captures how much investors are willing to pay today for each unit of current profit.
On that measure, the stock carries a heavy premium. The P/E of 42.9x is far above the JP Specialty Retail industry average of 13x and also well ahead of the peer group average of 17.5x, signalling that the market is pricing in materially stronger profitability and resilience than the sector norm. The estimated fair P/E of 28.7x is also well below the current multiple, which points to a level that valuations could gravitate toward if expectations cool.
Explore the SWS fair ratio for Fast Retailing.
Result: Price-to-earnings of 42.9x (OVERVALUED)
Still, Fast Retailing’s premium depends on continued earnings strength and smooth execution across Greater China and other key regions where conditions can shift quickly.
Find out about the key risks to this Fast Retailing narrative.
Another view on Fast Retailing’s value
The P/E comparison already looks stretched for Fast Retailing, yet the SWS DCF model pushes that concern further. On this cash flow view, the shares around ¥75,840 trade well above an estimated value of ¥39,878.71, which implies the market is paying up heavily for the current story. Where does that leave investors who want growth without overpaying for it?
Look into how the SWS DCF model arrives at its fair value.
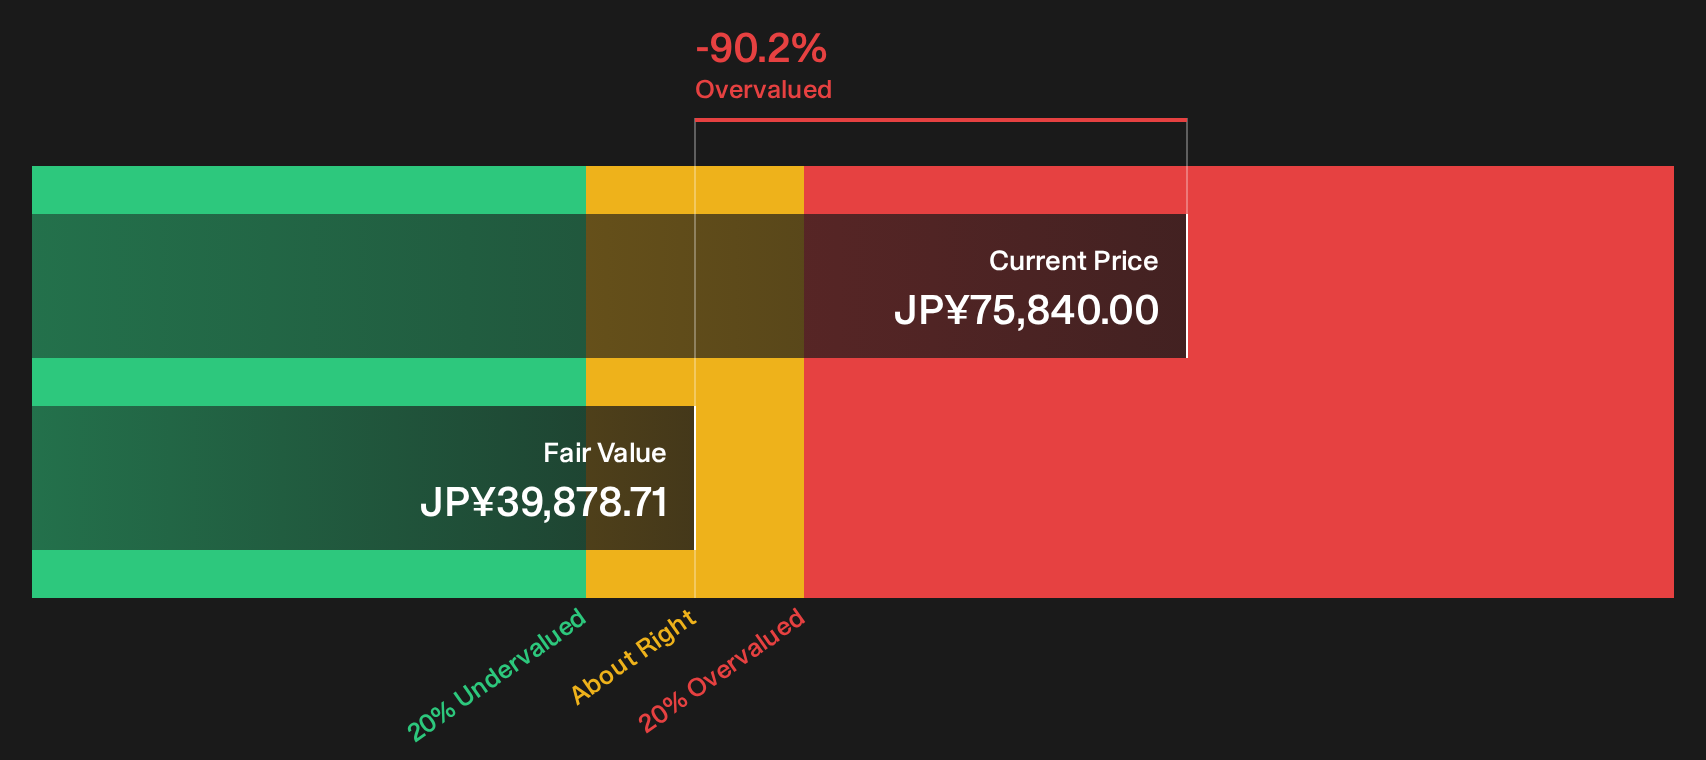
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fast Retailing for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Fast Retailing’s valuation and outlook can feel confusing, so move quickly to check the underlying data, weigh both the risks and upside, and ground your own view with the 2 key rewards and 1 important warning sign
Looking for more Fast Retailing style ideas?
If Fast Retailing’s setup has you thinking bigger, use this moment to widen your watchlist and pressure test fresh ideas before the next move.
- Target value with conviction by scanning a 15 high quality undervalued stocks that pairs quality fundamentals with prices that still look reasonable on the numbers.
- Protect your downside by focusing on a 23 resilient stocks with low risk scores built around resilient balance sheets and steadier risk profiles.
- Spot fresh opportunities early by reviewing a 73 high quality undiscovered gems that highlights under-followed businesses with solid underlying performance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com