


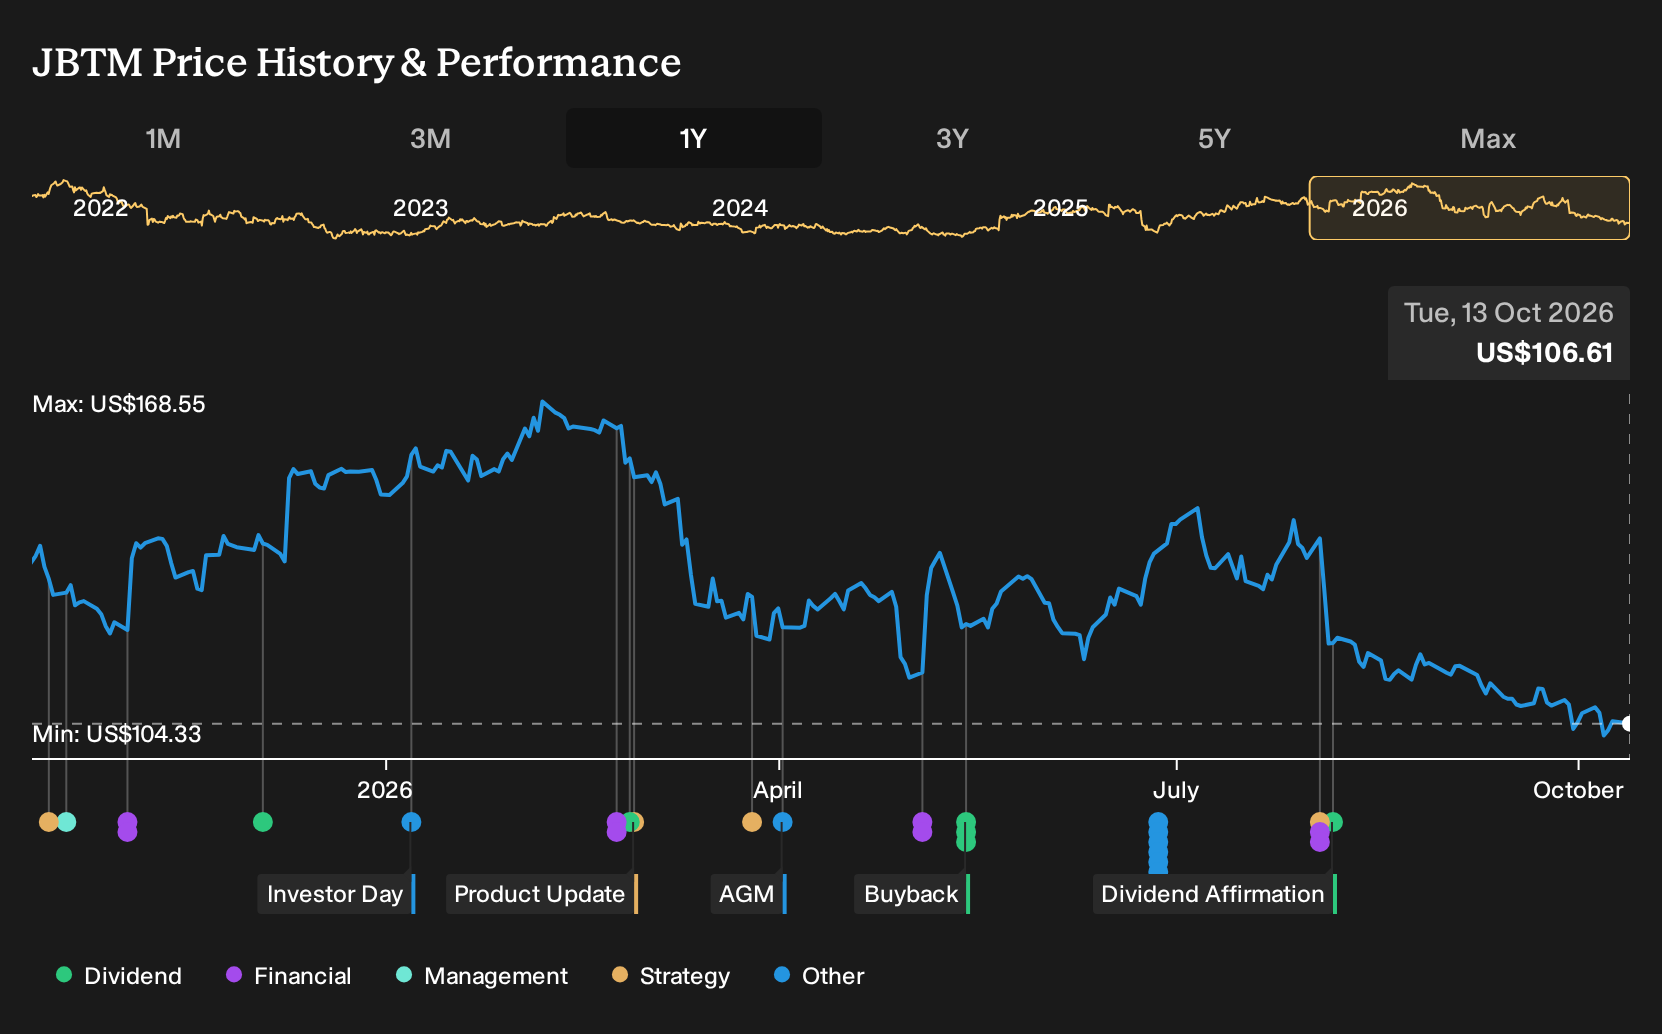
- JBT Marel recently reported revenue that aligned with analyst expectations, but issued full year EPS guidance and EPS estimates that fell well short of forecasts.
- The weak full year outlook, especially relative to peers, points to pressure on JBT Marel's profitability assumptions despite steady reported sales.
- Next, the focus shifts to how this weaker EPS guidance reshapes JBT Marel's investment narrative and the assumptions investors rely on.
Stress test your thesis on JBT Marel by comparing this weaker earnings outlook with 32 high quality undervalued stocks, which currently pair solid fundamentals with more resilient profit profiles.
JBT Marel Investment Narrative Recap
To own JBT Marel, you need to believe in a long runway for automation, food safety and traceability spending, and in the merged group turning that demand into reliable earnings. The recent EPS guidance reset tests that confidence in the near term. The key short term catalyst now is execution on cost control and merger synergies to close the gap between solid sales and weaker profitability.
The largest risk is that tariff pressure, integration complexity and cyclical equipment orders combine to keep margins subdued longer than expected. If synergy capture stalls or supply chain changes around tariffs drag on, the investment case tilts more toward a lower return profile, even with a healthy order backdrop.
With revenues tracking expectations, the striking part of the update is how the full year EPS outlook underperforms peers and triggered a share price drop of almost 25% since the results. That move puts more weight on whether JBT Marel can translate its food and beverage exposure, aftermarket mix and automation demand into cleaner, less one off heavy earnings.
In this context, the merger with Marel remains the central ongoing development. Synergies, cross selling and aftermarket growth were framed as key supports for margin expansion into 2027 in earlier expectations. The latest guidance now acts as a live test of that thesis because slower than hoped progress on cost savings or integration risks would directly weaken the case for faster profit growth from here.
JBT Marel's current analyst story points to revenues of $4.4b and earnings of $581.5 million by 2029, built on assumed yearly top line growth of 4.2% and an earnings step up of about $388 million from $193.3 million today.
Uncover how JBT Marel's fair value indicates a 57% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the lowest JBT Marel forecasts were already flagging logistics friction as a key swing factor, with revenue growth assumptions of about 4.1% a year and earnings reaching roughly US$606.3 million by 2029. That group now looks more pessimistic on execution quality. Use this reset to compare those views and test which story resonates most with you.
Explore 2 other JBT Marel fair value estimates, including one that suggests it could be worth just $167.06!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your JBT Marel research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for JBT Marel. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate JBT Marel's overall financial health at a glance.
Looking for more JBT Marel investment ideas?
If the reset in JBT Marel expectations has you reassessing where to put fresh capital, it can help to line this stock up against other candidates with clear, data driven filters.
- For investors who want quality on sale, compare JBT Marel against companies screened for strong fundamentals and attractive pricing through 32 high quality undervalued stocks.
- If capital protection matters most, focus on businesses with sturdier financial footing and minimal balance sheet stress using the list of solid balance sheet and fundamentals (25 results).
- For those hunting for ideas that the market may be underappreciating, broaden your watchlist with a curated set of underfollowed opportunities via 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com