


- Wise Group recently launched a travel-focused bundle that combines customizable eSIM data plans with a cross-border QR payments feature across five continents, alongside new travel tools inside the Wise Account.
- The appointment of long-time technology operator Barak Eilam as Non Executive Director and Chair Designate adds board-level experience in scaling cloud platforms and working with global enterprises and fintechs.
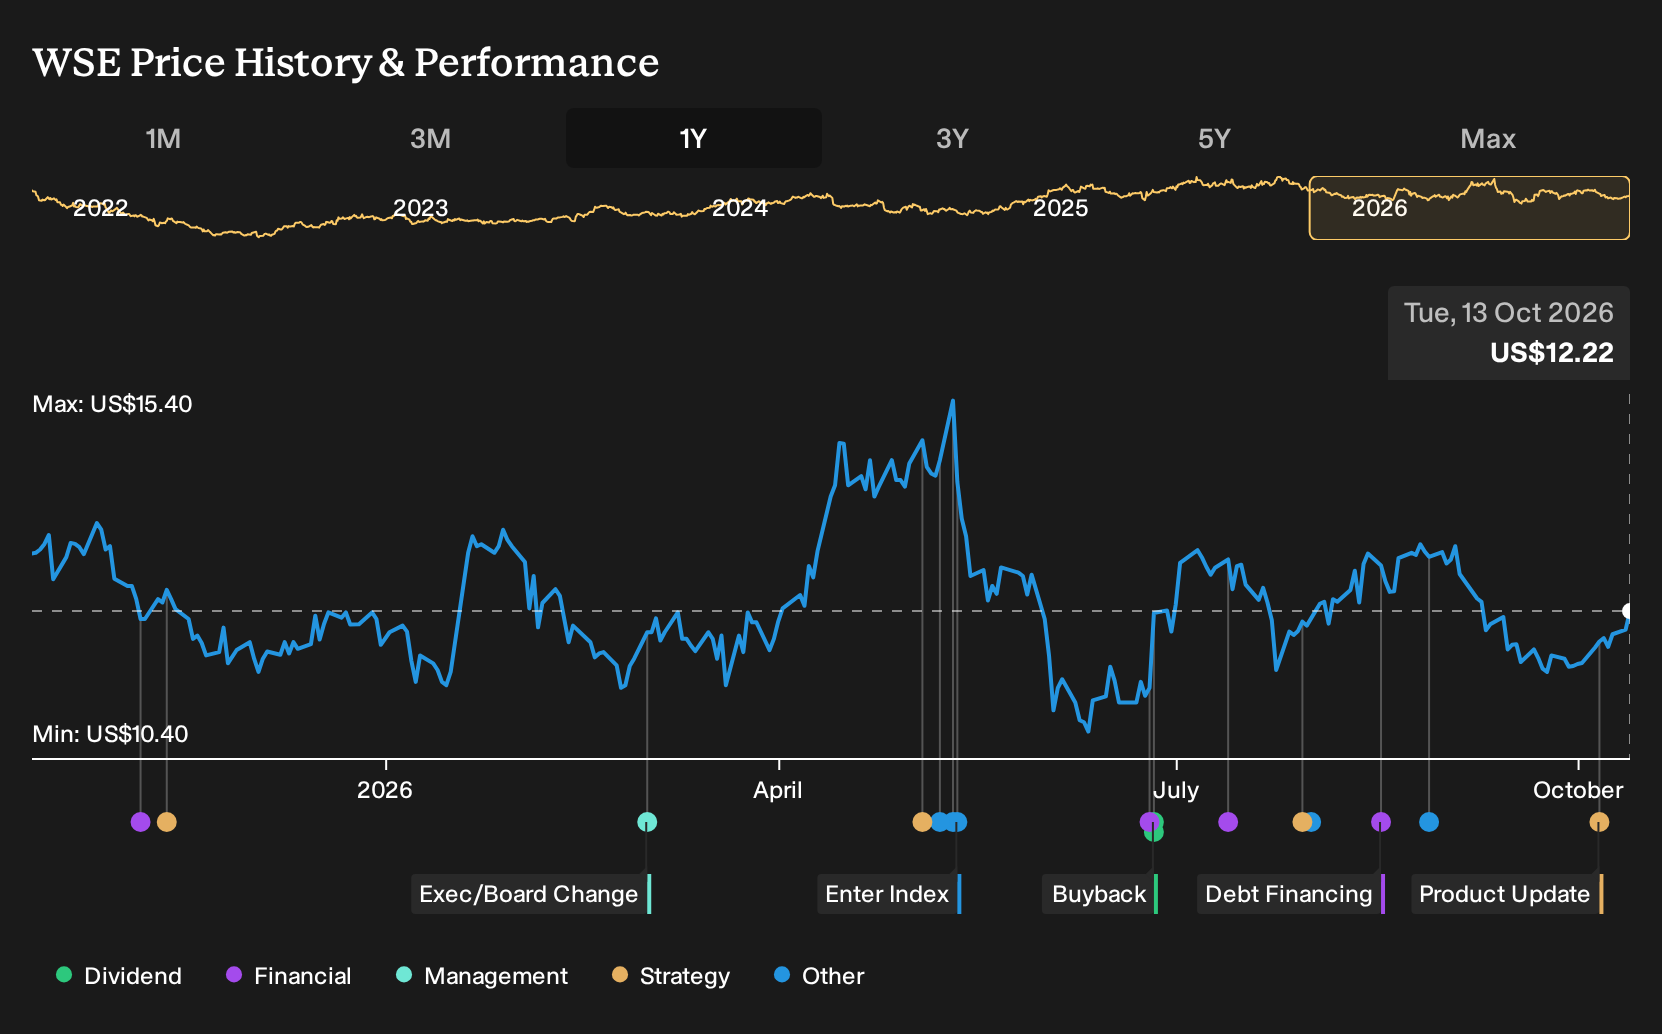
- This article examines how Wise Group's investment narrative is influenced by its eSIM and QR travel product expansion and the appointment of the new Chair.
Wise Group Investment Narrative Recap
To own Wise Group, you need to believe its cross border payments and account products can keep scaling while price cuts, heavier marketing and higher tech spend still leave room for solid profitability. The most important near term swing factor remains execution on volumes through Wise Account, Wise Business and Wise Platform, rather than any single product launch.
The biggest operational risk still sits in margin pressure from lower take rates and dependence on interest income from US$39b of customer balances. The Barak Eilam appointment looks more like medium term governance and execution support, rather than a material shift to short term catalysts or risk.
The launch of the travel focused eSIM and QR bundle is the clearest operational link to Wise Group’s growth drivers today. It plugs straight into the existing account, card and local payment connections across regions such as Singapore, Brazil and Thailand, and could push more everyday spending into Wise rather than traditional banks while customers are abroad.
For catalysts, this product suite gives Wise another way to deepen engagement and potentially increase non cross border revenue per user, which matters if transaction take rates continue to trend lower. The key execution watchpoints sit around customer adoption, servicing costs on travel heavy usage and any added regulatory complexity from effectively stepping closer to telco territory.
Wise Group's narrative ties analyst forecasts to a revenue line of US$4.1b and earnings of US$775.2m by 2029, built on an assumed 18.3% yearly revenue growth rate and an earnings move of roughly US$276.5m from earnings today of US$498.7m.
Uncover how Wise Group's fair value indicates a 39% potential upside to its current price before the valuation gap starts to close.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$12.97 and US$17.04 per share, so you are seeing a fairly tight band rather than a single consensus. That range now meets fresh information. The travel eSIM launch and Barak Eilam’s appointment could reshape how you think about Wise Group’s earnings risk, execution and governance. Opinions clearly differ, so explore several of these community viewpoints before deciding where you stand.
Explore 2 other Wise Group fair value estimates, including one that suggests it could be worth just $12.97.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Wise Group research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Wise Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wise Group's overall financial health at a glance.
Looking for more Wise Group style investment ideas?
Once you have a view on Wise Group, it can help to line it up against other listed opportunities that share similar qualities, whether you care more about value, resilience or balance sheet strength.
- If you want potential value combined with quality fundamentals, run Wise Group next to 32 high quality undervalued stocks and see which businesses also offer a mix of strong cash flows and supportive balance sheets.
- For investors who put capital preservation first, compare Wise Group with 32 resilient stocks with low risk scores so you can focus on companies that our models rate as more resilient.
- If financial robustness matters most to you, anchor Wise Group alongside a list of solid balance sheet and fundamentals (25 results) and look for businesses that keep leverage and funding risk in tighter check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com