


Tsakos Energy Navigation (TEN) is back ordering container capacity, with Tsakos Group signing a deal for two 3,200-TEU vessels at China’s Hengli Heavy Industries, expanding an already busy newbuild pipeline.
Recent moves help explain why momentum in Tsakos Energy Navigation has been strong, with a 30 day share price return of 17.75% and a 90 day gain of 42.21%. The 1 year total shareholder return of 184.86% and 5 year figure of about 6.6x highlight how long term holders have been rewarded as the orderbook and preferred dividend announcements keep the story in focus.
Scan how Tsakos Energy Navigation compares with other shipping and infrastructure plays already screened for balance sheet strength and fundamentals in our list of solid balance sheet and fundamentals (25 results).
Bulls see Tsakos Energy Navigation using the fresh orderbook and preferred payouts as fuel for further upside. Bears point to falling annual revenue and net income. Which story does the current valuation actually support next?
Most Popular Narrative: 23% Overvalued
Tsakos Energy Navigation closed at $56.40, while the most followed narrative anchors fair value at $46.00, so the market price currently sits well above that reference point and raises the bar for what needs to go right.
The plan to sell 18 to 20 older tankers and replace them with 34 to 35 larger, younger vessels averaging under one year of age raises the fleet’s operational leverage to freight markets and can encourage investors to assume higher long term net margins and asset values.
See why 12 investors see Tsakos Energy Navigation as 23% overvalued.
Result: Fair Value of $46 (OVERVALUED)
Still, shrinking annual revenue and net income, alongside analyst forecasts for sharply lower margins and earnings by 2029, could change the Tsakos Energy Navigation story more quickly than bulls expect.
Find out about the key risks to this Tsakos Energy Navigation narrative.
Another View: Tsakos Energy Navigation On Earnings Multiples
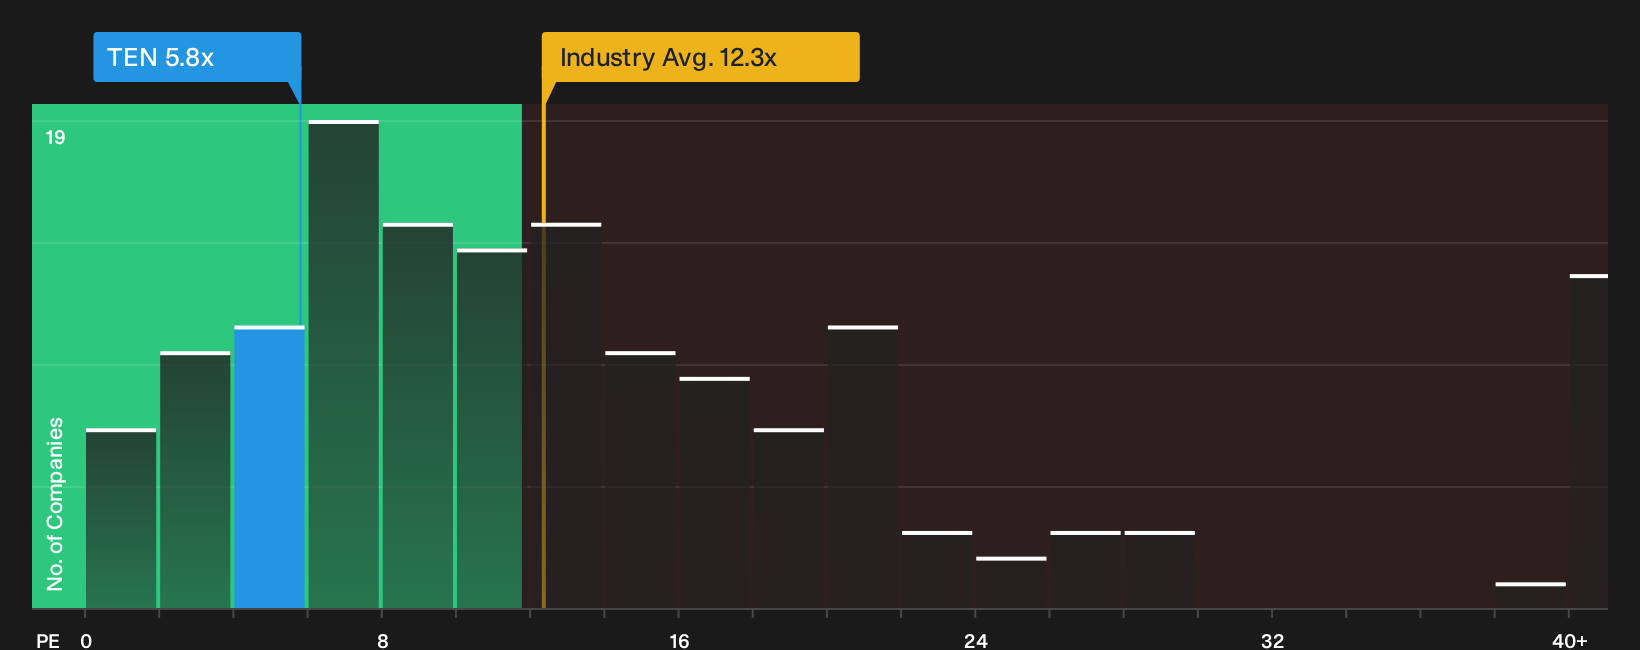
The first lens paints Tsakos Energy Navigation as 23% overvalued against a $46 fair value. A different angle comes from its P/E of 5.8x, which is far below peers at 16.5x, the US Oil and Gas group at 12.2x, and even the 10.7x fair ratio that the market could move toward. Is the share price expensive, or are earnings being priced cautiously?
See what the numbers say about this price in the valuation breakdown in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed opinions on Tsakos Energy Navigation are clear, with bulls and bears both armed with data. Act while the debate is fresh and review the 3 key rewards and 4 important warning signs.
Looking For More Investment Ideas Beyond Tsakos Energy Navigation?
You have the Tsakos Energy Navigation story in front of you. Now widen your opportunity set using focused screeners that surface clear, data backed ideas fast.
- Target potential mispricings by scanning companies flagged as strong value candidates through the 32 high quality undervalued stocks.
- Prioritise resilience by reviewing businesses highlighted as having sturdier balance sheets and fundamentals in the list of solid balance sheet and fundamentals (25 results).
- Spot overlooked opportunities by checking companies tagged as higher quality outliers inside the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com