


GE Vernova (GEV) is back in focus after its board declared a US$0.50 per share quarterly dividend for the fourth quarter of 2026, setting fresh terms for income focused investors.
GE Vernova’s share price has climbed strongly this year, with a year-to-date share price return of 47.75% and a 1-year total shareholder return of 56.16%. This puts recent short-term pullbacks, including a 7-day share price decline of 2.45%, into context as investors weigh raised revenue guidance, a US$176b backlog tied to AI-driven data center demand, and the newly declared dividend.
Explore the broader AI infrastructure landscape beyond GE Vernova by evaluating peers connected to data centers, grid upgrades, and electrification through our curated 92 AI infrastructure stocks
Some investors see GE Vernova’s AI fueled backlog and new dividend as the start of a durable earnings story. Others see a hot stock and frothy expectations. Which side does the valuation support next?
Most Popular Narrative: 20.9% Undervalued
On the latest narrative view, GE Vernova’s fair value of $1,269.77 sits well above the last close at $1,004.04, which points to meaningful upside in that framework and emphasizes how durable its electricity infrastructure positioning can be.
GE Vernova sits at the center of one of the most important industrial shifts of this decade: the explosive growth in electricity demand driven by AI data centers, electrification, and grid modernization. While many investors focus on semiconductor companies benefiting from AI, GE Vernova is effectively the “power infrastructure backbone” enabling the entire ecosystem. Every hyperscale AI data center needs massive amounts of reliable electricity, and GE Vernova supplies the gas turbines, transformers, switchgear, and grid systems that generate and deliver that power.
See why 59 investors see GE Vernova as 21% undervalued.
Result: Fair Value of $1,269.77 (UNDERVALUED)
Still, this upbeat GE Vernova story can crack if offshore wind losses deepen, or if AI related data center orders cool from recent levels.
Find out about the key risks to this GE Vernova narrative.
Another View: SWS DCF Model Flags Overvaluation
The narrative crowd sees GE Vernova as 20.9% undervalued at a fair value of $1,269.77, yet the SWS DCF model points the other way. On that framework, an estimated future cash flow value of $858.39 sits below the current $1,004.04 share price, which implies a premium. Which story do you trust more?
Look into how the SWS DCF model arrives at its fair value.
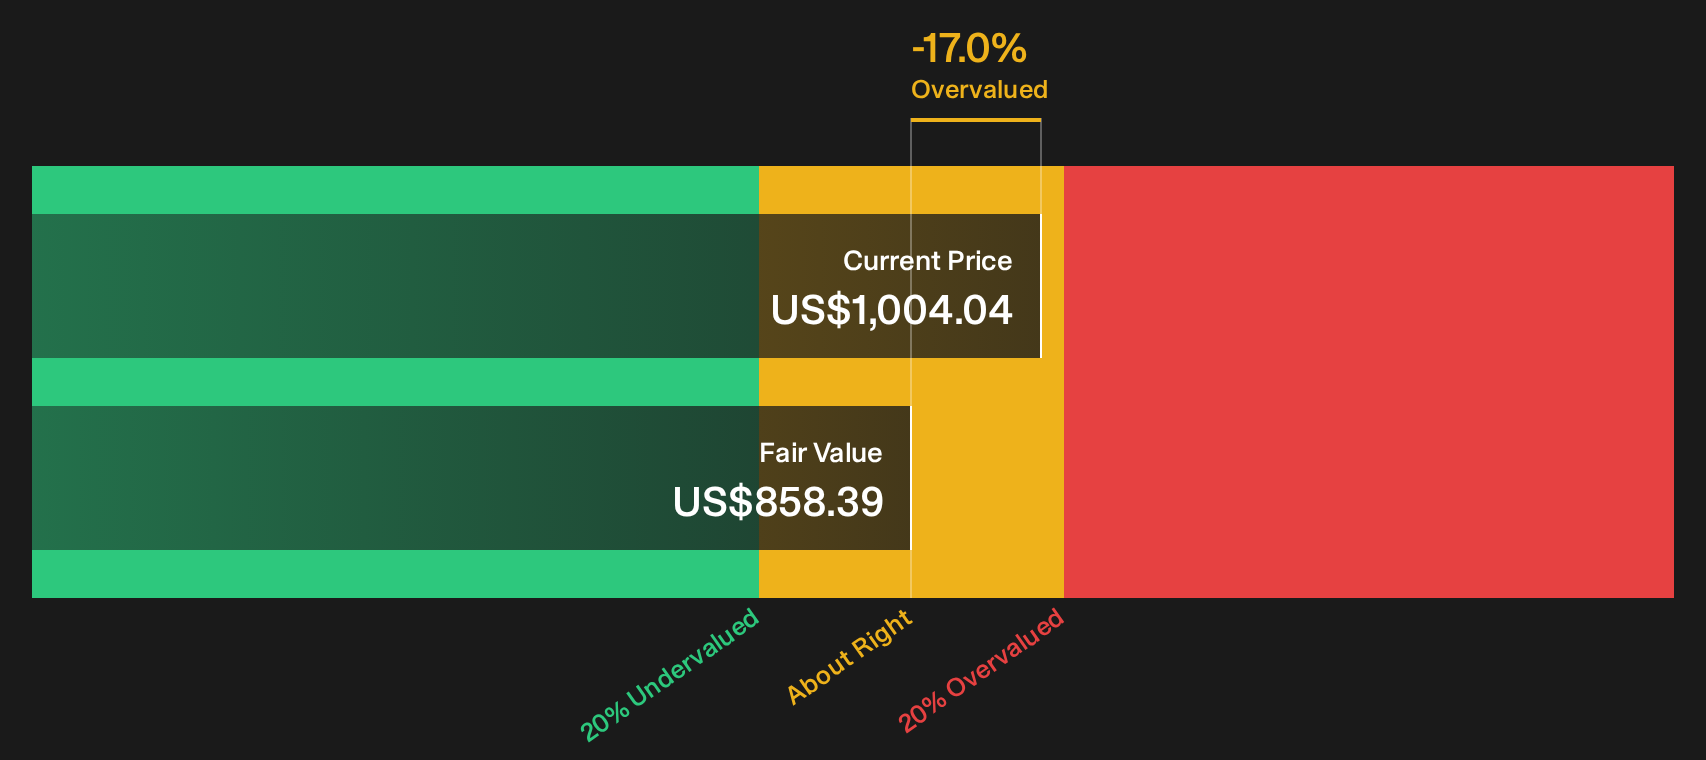
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out GE Vernova for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Does this mix of enthusiasm and caution around GE Vernova match your own read, or feel out of step with it? Act while the debate is fresh, weigh the upside against the red flags, and stress test your thesis with the 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond GE Vernova?
If GE Vernova has sharpened your thinking, broaden your opportunity set now by scanning other potential winners before the crowd gets there first.
- Target steadier compounding by reviewing companies with strong balance sheets and resilient fundamentals through our list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a discount by checking businesses that our metrics flag as attractively priced in the 32 high quality undervalued stocks.
- Secure potential income streams by focusing on shares that combine higher yields with robust profiles in the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com