


Eleven of the 30 current members of the Dow Jones Industrial Average ($DOWI) have produced less than a 5% annualized return over the past five years. You see them below the purple line.
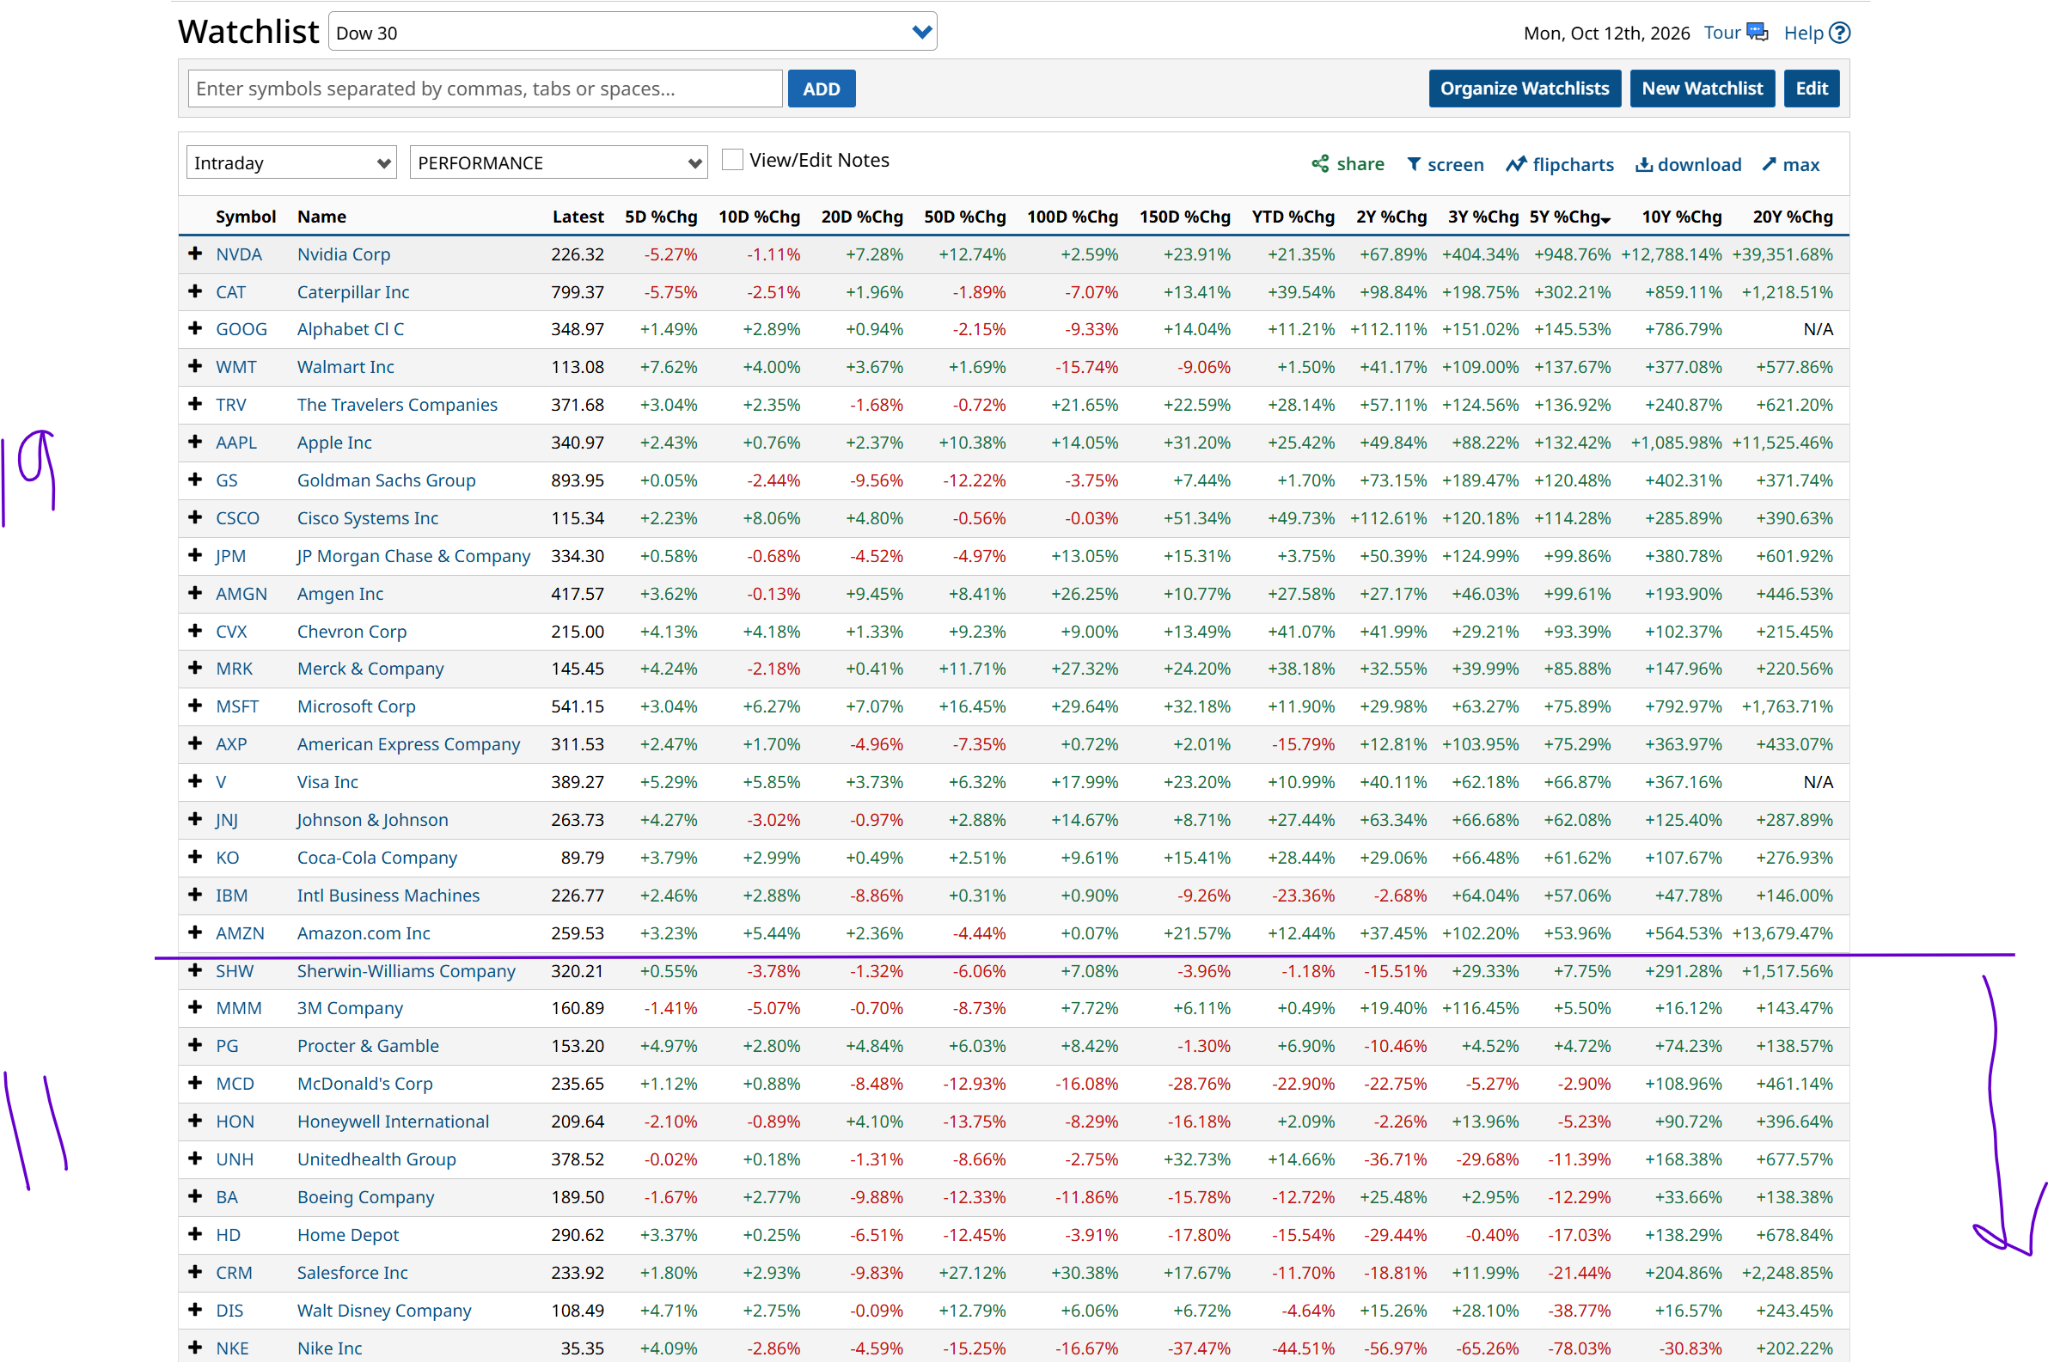
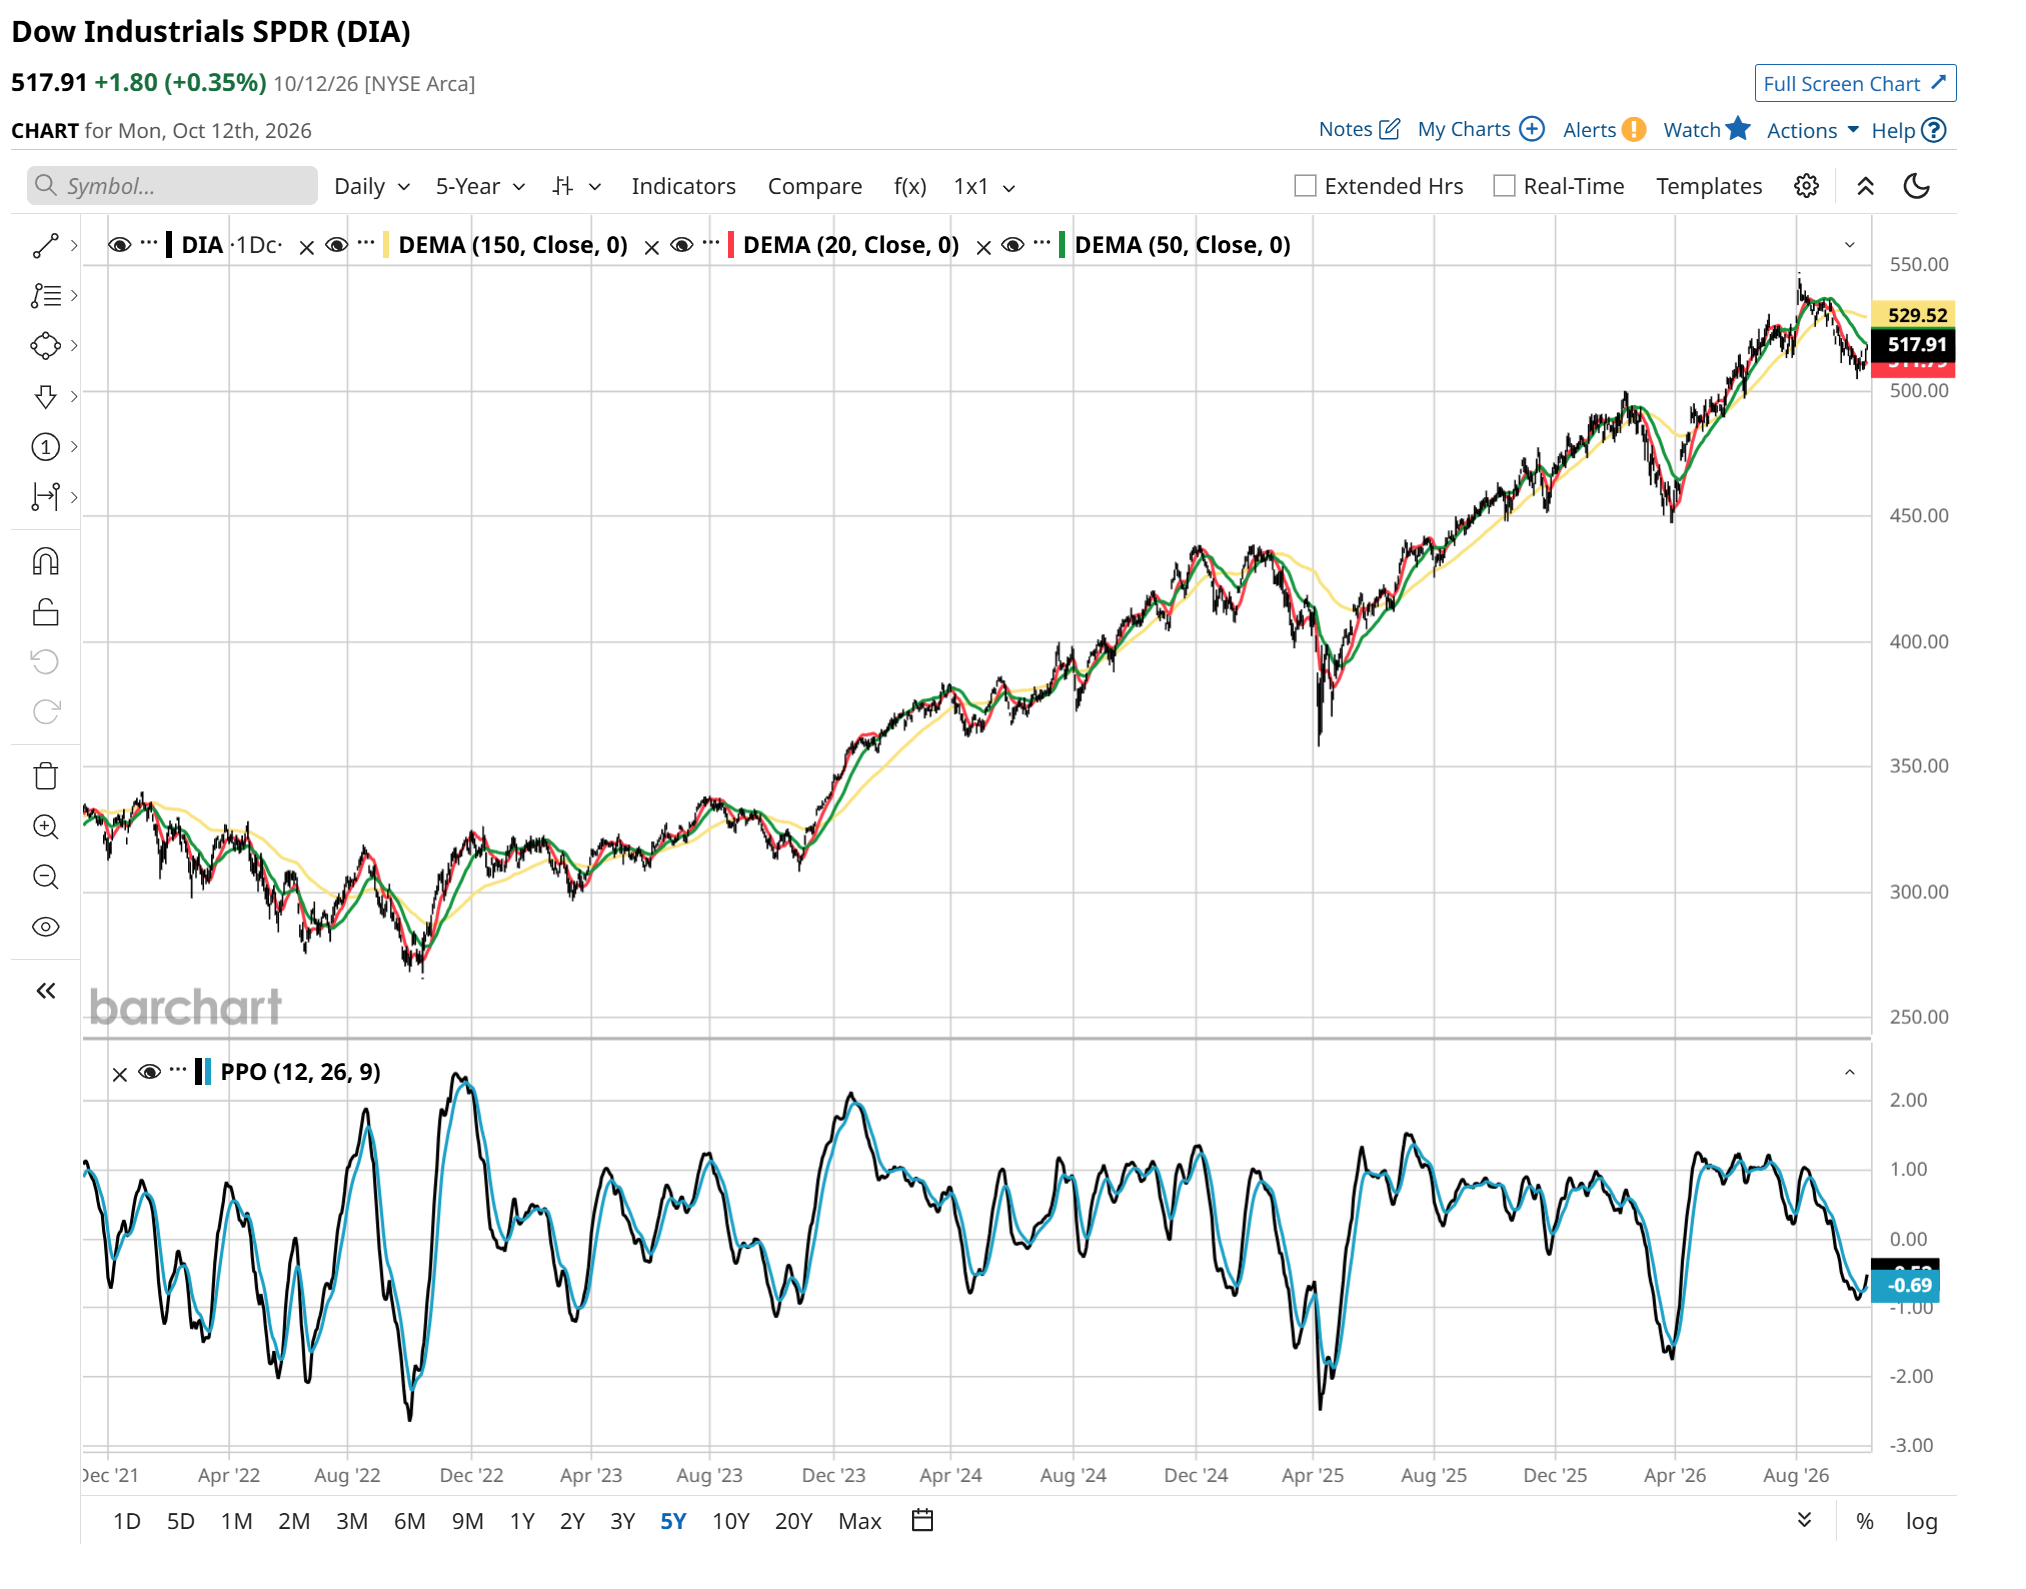
The Dow Jones Industrial Average itself gained more than 50% over this time. Yet 11 of its 30 stocks returned less than 8% in total over that time. T-bills made several times that. What’s going on?
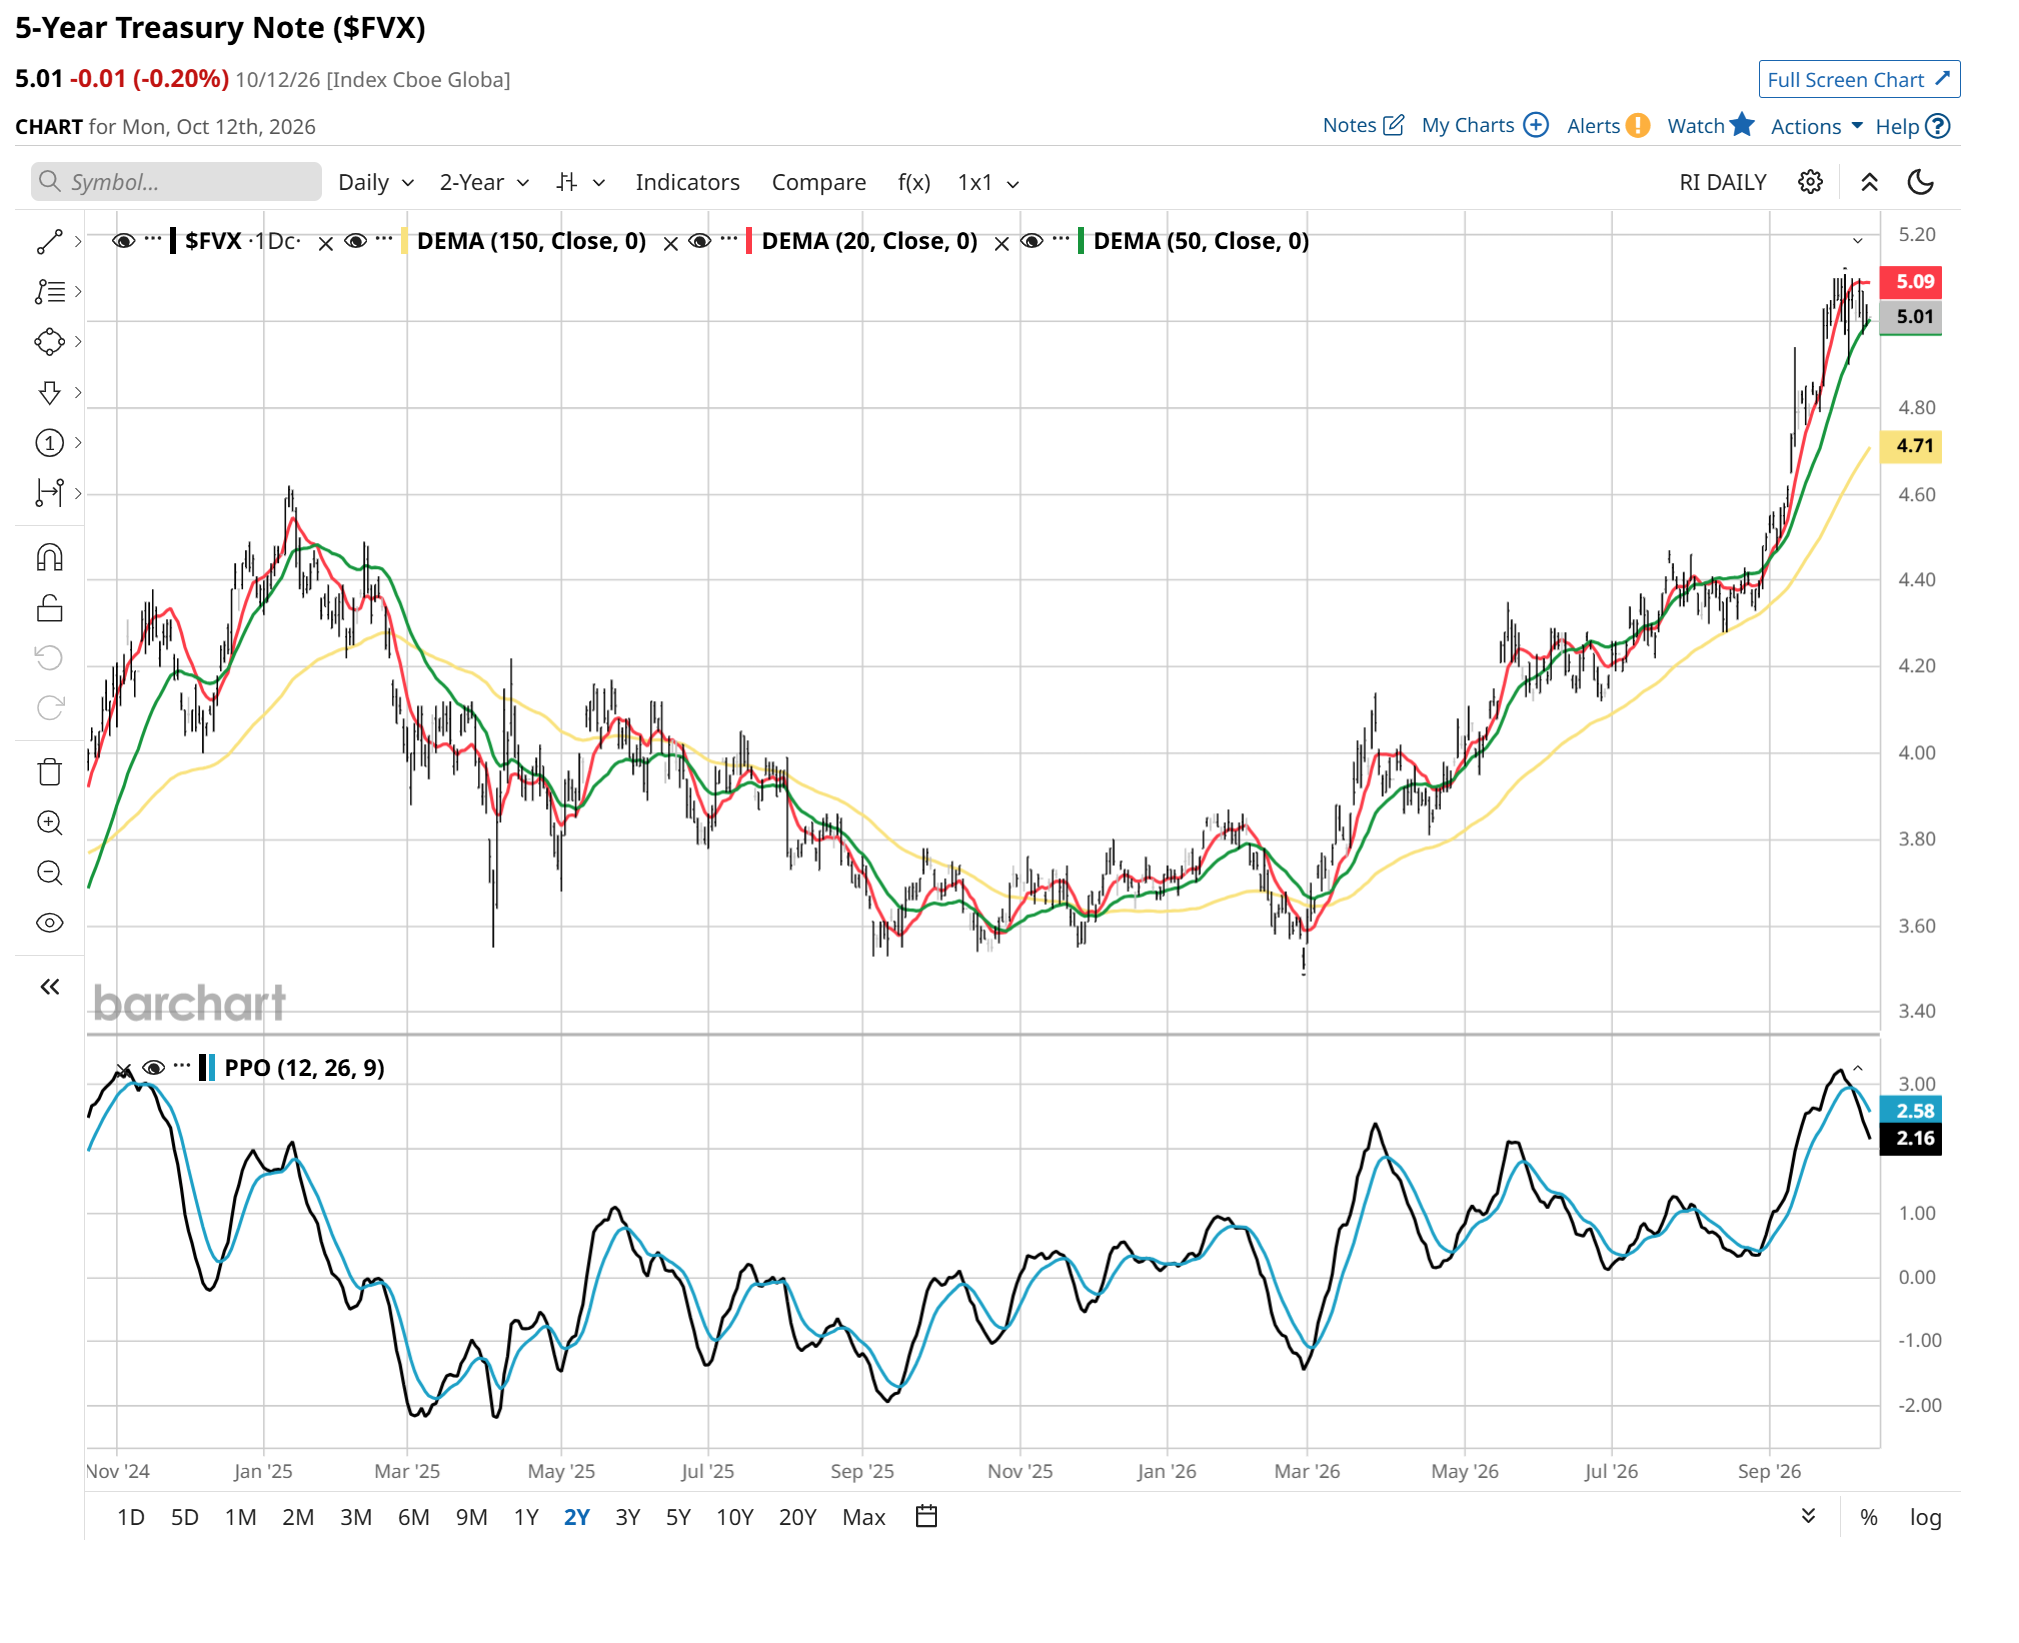
As I see it, we are at a point in the stock market cycle where hopeful energy comes not from expecting the stock market to move up in unison forever. Instead, it comes from knowing you can get paid 5% or more just for holding five-year Treasury bonds.
5% does not sound very sexy. Until you realize just how hard it is to beat when you take AI stocks out of the picture. I think sooner rather than later, the AI mania will fail to live up to expectations.
In part because those expectations are so fueled by lofty ideas of what’s to come. There’s a good chance that the return-on-investment predictions Wall Street is making now won’t come true. Just too many things have to go right for that to happen.
So take the 5% return for five years. Just take it!!
I am doing that with a lot of my portfolio, as part of a ladder of bonds that stretches from just a couple of years out to 20 years from now.
I’ll be 82 then. And Lord willing, I’ll still be educating investors and analyzing the market, to the extent I can see my keyboard. If you’ll be 50, 60, or 70 in 20 years from now, 5% is 5%.
You can decide how much you want to allocate to Treasurys. Just know that this is a gift from the markets.
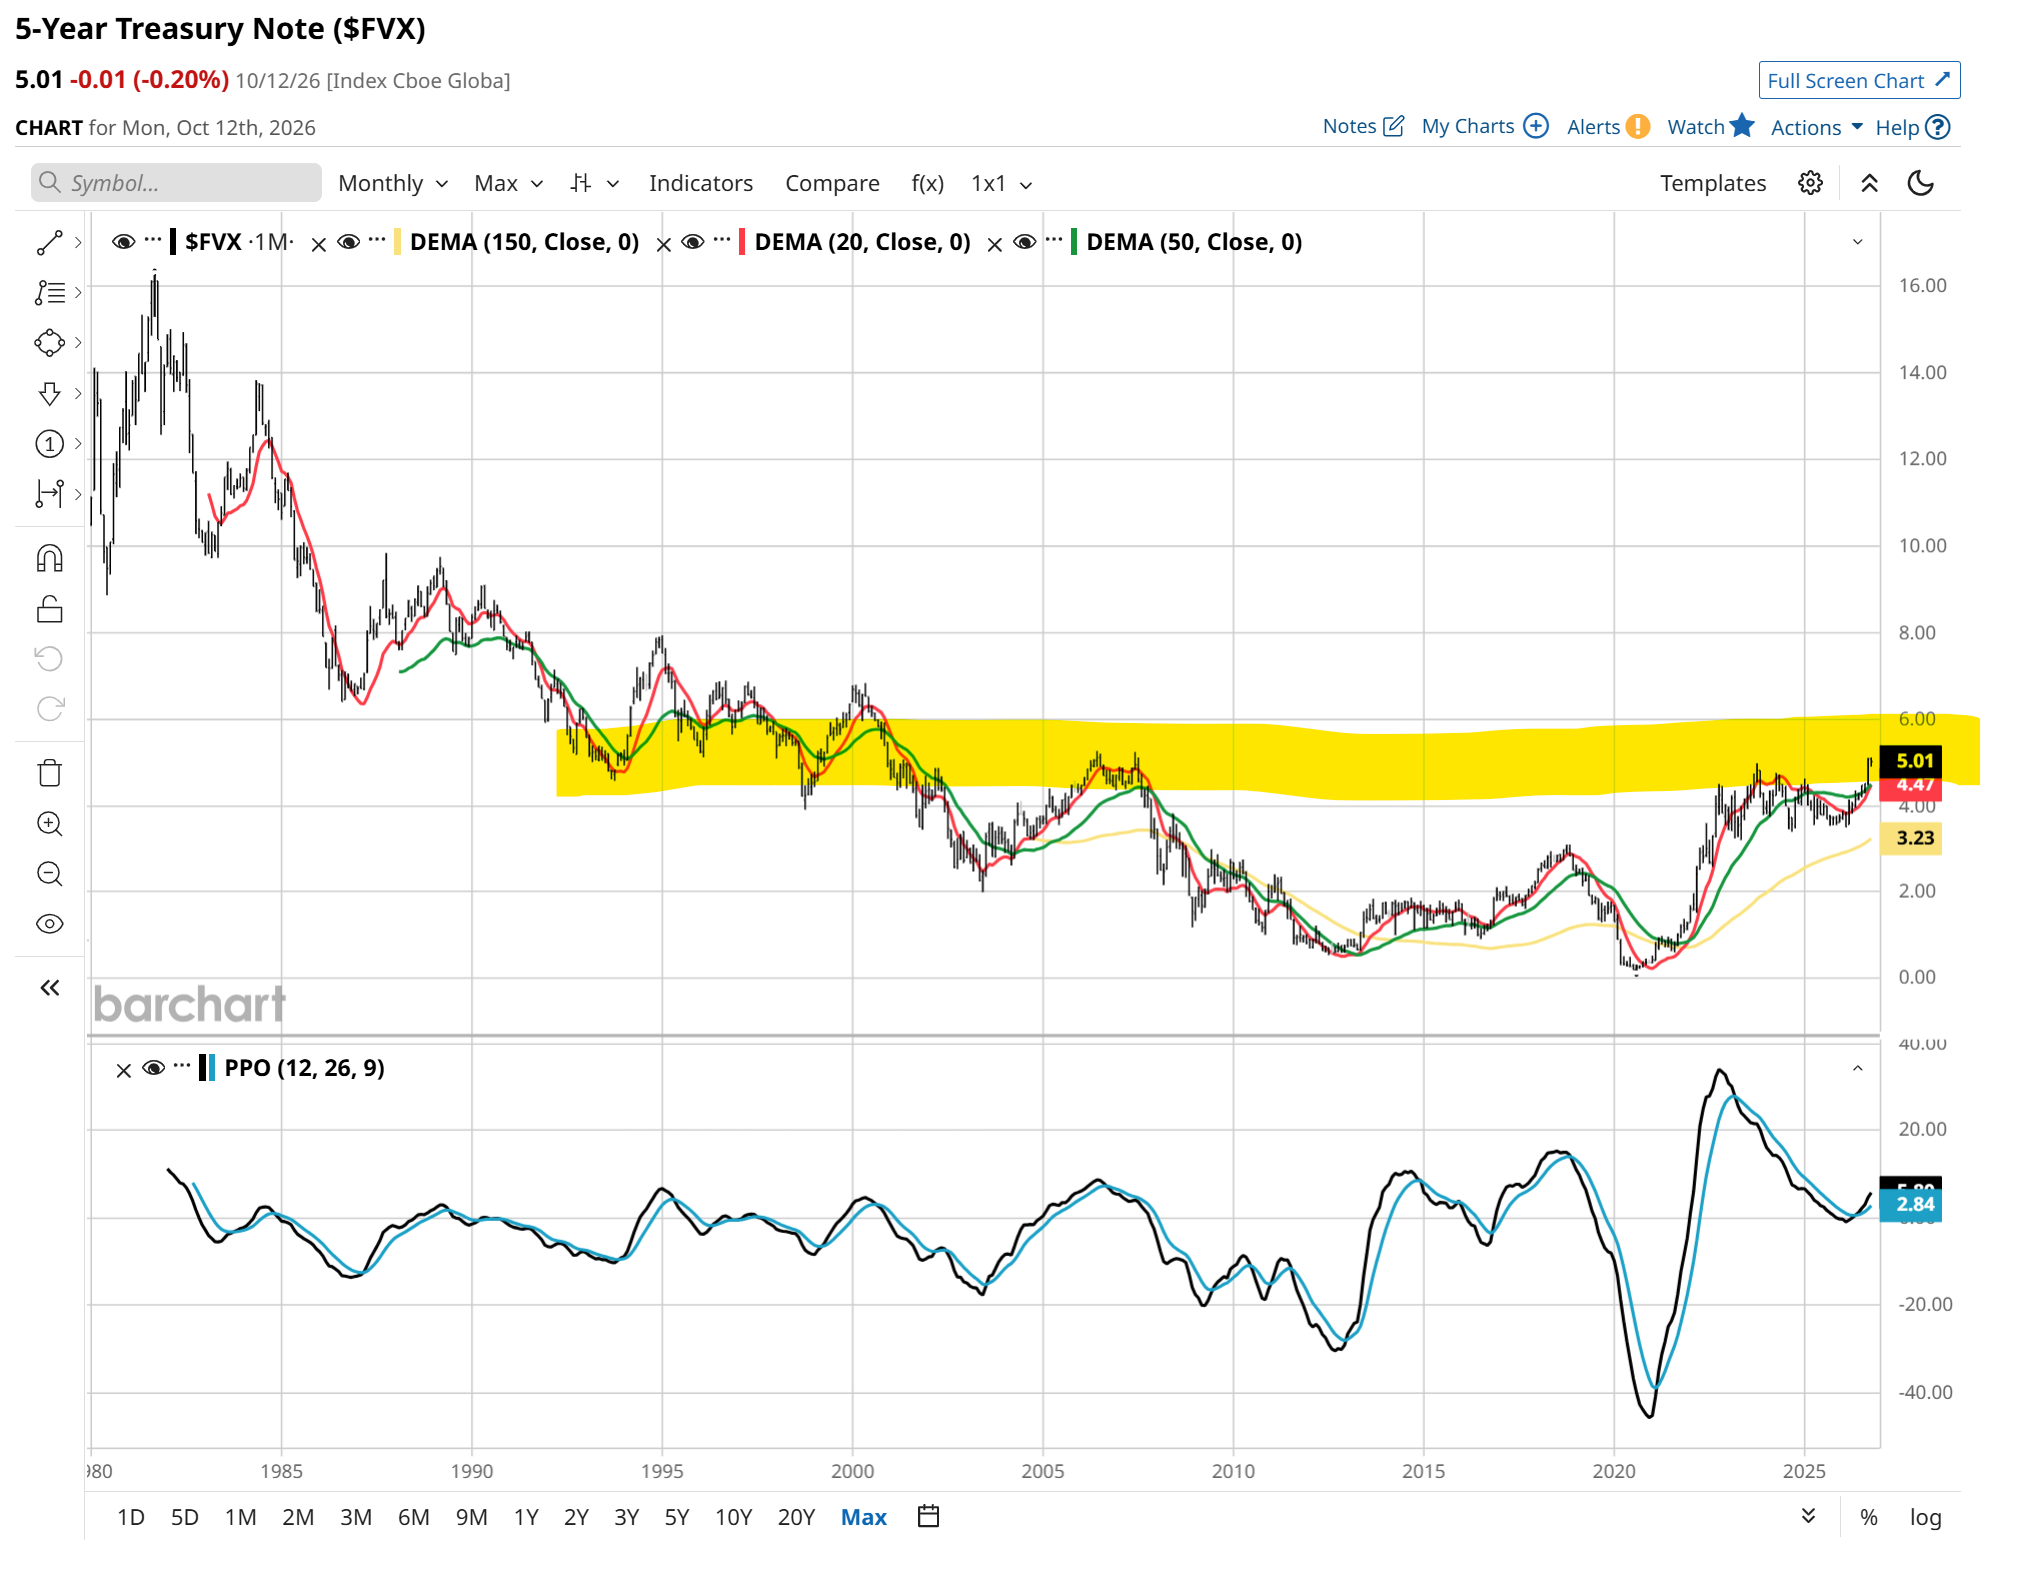
I say that because, as seen above, the 5-year bond has not been this high since back to the early 1990s!
More importantly, if so many blue-chip stocks can’t earn close to 5% a year in a bull market, doesn’t 5% look intriguing? At least worth a look? I looked, and decided yes.
Now, I hedge my bond portfolio, as I’ve discussed here and will write about again and again. But one thing about bonds well under 10 years to maturity is that they are not nearly as volatile. And even if rates do go up, five years is not a very long-term commitment. This perspective is built for investors who have arrived at the stage where capital preservation is just as vital as capital appreciation.
I am not a financial planner by trade. I spent four decades as an investment manager and CIO. Throughout that career, one fundamental rule of active risk management has never wavered: if you can secure an annualized return of 5% or higher without subjecting your principal to major drawdown risk, taking that deal is common sense.
I am not suggesting an investor must allocate 100% of their liquid net worth into fixed income. But 30%? 50%? 70%? 90%? That framing shifts the entire conversation.
Rob Isbitts is a semi-retired CIO, former fiduciary investment advisor, Barchart columnist, and straight-talker. Download his new free e-book on hedged bond investing for retirement at ETFYourself.com. His research and model portfolios are at ROAR.PiTrade.com.
On the date of publication, Rob Isbitts did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.