


Shift4 Payments (FOUR) is back in focus after investors reacted sharply to strong quarterly revenue that beat forecasts, followed by full-year guidance that landed well below what the market had been expecting.
The sharp reaction to guidance has come on top of already weak momentum in Shift4 Payments, with the share price down 16.17% over the past month and 39.39% year to date. The 1-year total shareholder return has declined 49.69%, signaling that investors have been steadily marking down the stock as they reassess both growth potential and risk.
Scan beyond Shift4 Payments and see how other payment and fintech stocks with compressed sentiment but solid fundamentals stack up using our curated 32 high quality undervalued stocks.
So is Shift4 Payments being repriced because the business outlook genuinely reset with that softer full-year guide, or has sentiment simply swung too far after a 26.9% drop? The valuation now has to carry that answer.
Most Popular Narrative: 31% Undervalued
Against the last close at $37.99, the most followed narrative for Shift4 Payments is anchored on a fair value of $55.05. This frames the recent selloff as a discount that hinges on whether execution and cash generation line up with expectations.
Ongoing consolidation in the payments industry, coupled with Shift4 Payments three part capital allocation approach that includes tuck in M&A and a planned roughly $300 million account to account payments acquisition that is not yet in guidance, supports further scale benefits on top of a 46% adjusted EBITDA margin in Q2 2026 and a stated aim for roughly 60% incremental EBITDA to free cash flow conversion. This can increase free cash flow per share as integration progresses.
See why 69 investors see Shift4 Payments as 31% undervalued.
Result: Fair Value of $55.05 (UNDERVALUED)
Still, the narrative around Shift4 Payments can crack if international travel remains weak for tax free shopping, or if higher interest costs keep leverage pinned near management’s ceiling.
Find out about the key risks to this Shift4 Payments narrative.
Another View: What Multiples Say About Shift4 Payments
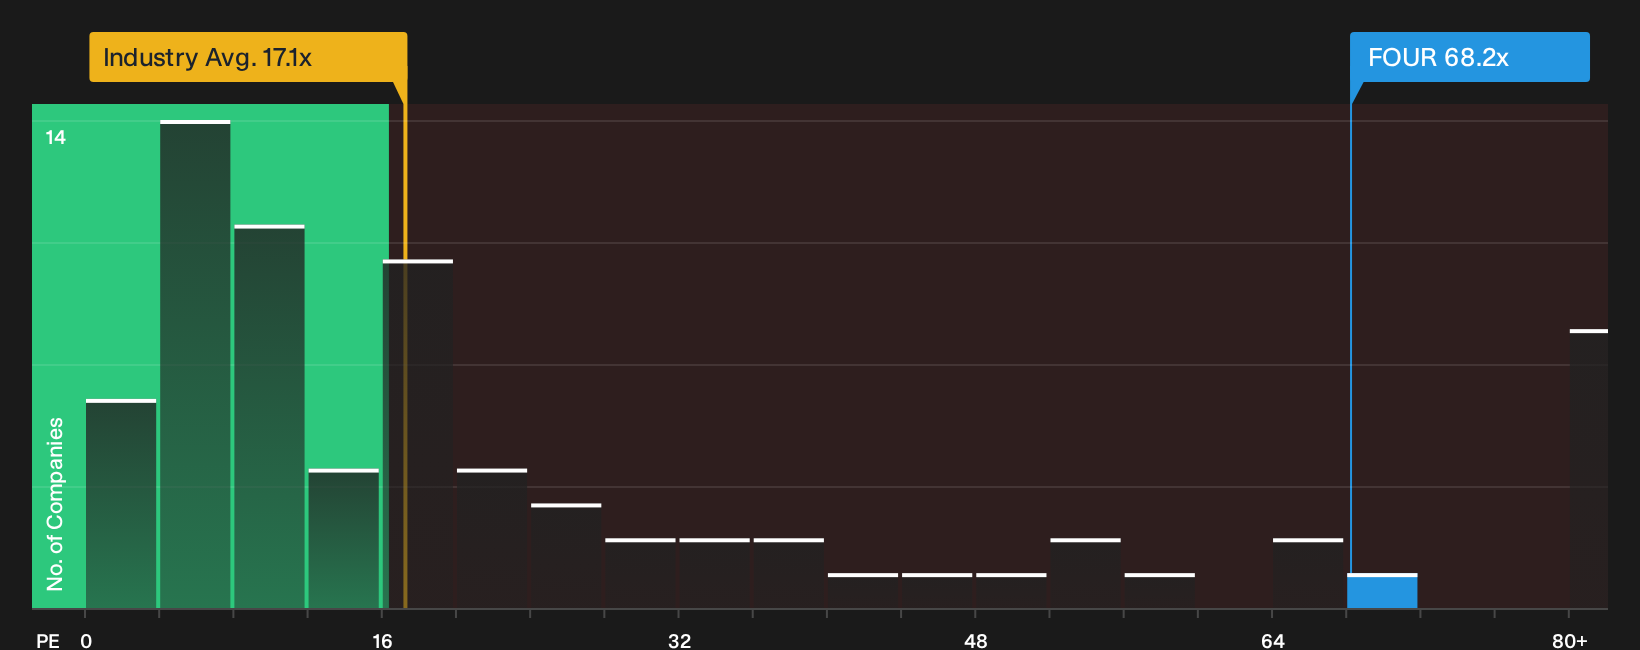
The story looks different when you stop focusing on fair value estimates and look at what the market is actually paying for Shift4 Payments earnings today. The stock trades on a P/E of 68.2x, while the US Diversified Financial industry sits near 17x and direct peers average 30.9x. The fair ratio sits at 29.9x, which is less than half the current level and suggests investors are paying a rich premium that could compress if expectations cool.
That gap raises a simple question for anyone following FOUR. Are you comfortable owning a payments processor where the valuation leaves little room for execution slip ups, or do you prefer to wait for the P/E to drift closer to that fair ratio level before taking a view on the turnaround in sentiment.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Shift4 Payments is clearly split, with sharp recent losses on one side and a valuation bull case on the other. If you want to move past the headlines and weigh that balance for yourself, start by checking the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Shift4 Payments?
If Shift4 Payments has sharpened your focus on valuation and risk, you can use the Simply Wall St Screener to uncover other opportunities that fit your checklist before they move.
- Target resilience first by zeroing in on companies with strong finances using our list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a discount by scanning the market for mispriced opportunities through the 20 high quality undiscovered gems.
- Prioritize sleep-at-night holdings by filtering for companies with historically lower risk profiles using the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com