


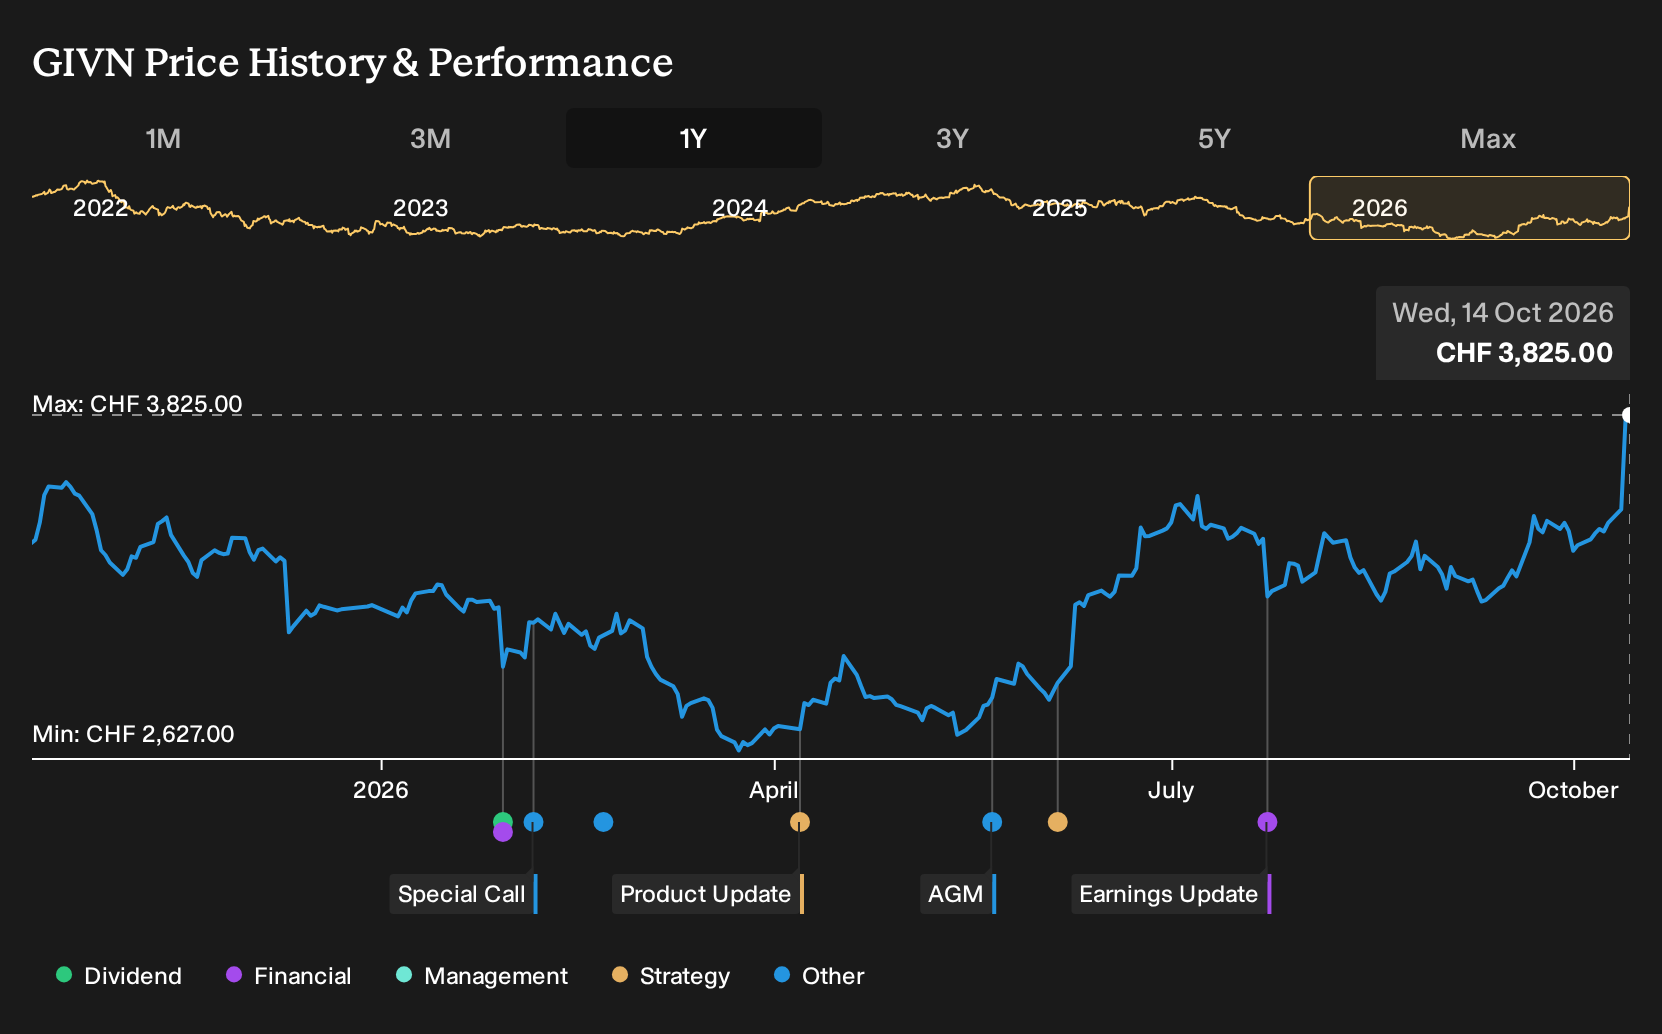
- Givaudan reported third quarter sales that surpassed analyst expectations, with Fragrance & Beauty sales rising 13.5% and Taste & Wellbeing also ahead of forecasts, and confirmed its longer term revenue and cash flow targets.
- The firm indicated that recent price increases are intended to fully offset higher input costs, which highlights management focus on protecting profitability while sustaining demand across its fragrance and taste portfolios.
- We will look at how Givaudan's stronger than expected Fragrance & Beauty performance influences the investment narrative around growth and pricing power.
Givaudan Investment Narrative Recap
To own Givaudan, you need to believe that its fragrance and taste franchises can keep attracting consumer goods clients while pricing offsets cost pressure without eroding demand. The latest quarter supports that belief on the top line, with Fragrance & Beauty and Taste & Wellbeing both ahead of expectations and price increases presented as cost coverage rather than pure margin grab.
The key short term swing factor is still margin resilience and cash generation after earlier periods of negative free cash flow. Stronger sales and pricing help, but high debt and softer demand in fragrance ingredients remain live risks, especially if input costs stay elevated or antitrust cases crystallise into fines that hit earnings and balance sheet flexibility.
The most relevant recent announcement for this update is Givaudan confirming that price increases are intended to fully offset higher input costs, alongside a reaffirmation of longer term revenue and cash flow targets. That message matters because the latest quarter shows solid volume and mix in fine fragrances, which gives pricing more support than if growth were weak.
If you view the current share price reaction as primarily about restored confidence in pricing power, then the focus naturally shifts to execution on costs, working capital and capex. Any slip that keeps free cash flow subdued or widens the gap between reported profitability and cash conversion could quickly put the spotlight back on leverage and the risk that future investment options become more constrained.
Givaudan's current analyst narrative points to CHF 8.7b revenue and CHF 1.3b earnings by 2029, based on 5.7% yearly revenue growth and an earnings increase of about CHF 346m from CHF 954.0m today.
Uncover why Givaudan's fair value indicates a 6% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate view focuses on Givaudan’s exposure to tighter chemical rules and higher compliance costs, rather than just pricing power. The most optimistic analysts still pencilled in revenue of about CHF 9.3b and earnings around CHF 1.5b by 2029 before this quarter. You can use this surprise to test which story you find more convincing.
Explore 3 other Givaudan fair value estimates, including one that suggests the potential for as much as 16% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Givaudan research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Givaudan. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Givaudan's overall financial health at a glance.
Looking for more investment ideas beyond Givaudan?
Once you have a view on Givaudan, it can help to line it up against other opportunities and see where the trade offs really are. The Simply Wall St Screener lets you filter for the kind of businesses that fit your style rather than chasing whatever is in the headlines.
- If you care about balance sheet strength and steady fundamentals, start with a list of solid balance sheet and fundamentals (202 results) that can handle tougher conditions without stretching leverage.
- For those hunting for mispriced quality, compare Givaudan with a 616 high quality undiscovered gems that combine robust financials with limited market attention.
- When capital preservation comes first, narrow the field to a 224 resilient stocks with low risk scores and see which companies match your comfort level.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com