


- Furuno Electric increased its second quarter cash dividend to ¥115 per share from ¥75 a year earlier and raised both interim and full year fiscal 2027 forecasts after second quarter performance exceeded prior expectations, particularly in the Marine Business.
- Management highlighted stronger demand from the merchant vessel market, supported by Chinese shipbuilders bringing forward construction schedules, which contributed to higher expected net sales of ¥158,000 million and operating profit of ¥21,000 million for the year ending February 28, 2027.
- We will examine how Furuno Electric’s investment narrative evolves as higher Marine Business guidance reframes the balance between growth and income.
Scan how Furuno Electric’s upgraded dividend and guidance compare with other income and quality plays by reviewing our hand picked 28 dividend fortresses in similar yield driven stories.
What Is Furuno Electric's Investment Narrative?
To stay in Furuno Electric for the long haul, you need to buy into a fairly simple idea. This is a marine focused electronics business that lives and dies by execution in its core segments, not by financial engineering. The raised guidance ties directly to real demand from merchant vessels and earlier build schedules at Chinese shipyards, which speaks to order timing and pricing power rather than one off gains. The higher full year outlook for net sales of ¥158,000 million and operating profit of ¥21,000 million keeps the near term catalyst squarely on how fast the Marine Business can convert that pipeline into shipped systems.
The richer interim dividend and modest lift to the full year payout target signal confidence, but they also interact with an already capital intensive hardware model and an unstable dividend track record. Rising component costs are explicitly flagged by management and sit alongside issues like recent earnings pressure versus the prior year, volatile trading in the share price and a P/E of 16.4x that screens as reasonable compared with Japanese electronics peers. For an investor, the real test is whether Furuno Electric can keep balancing reinvestment needs with this sharper income pitch without stretching its financial flexibility.
That said, there is a less comfortable angle to this story that only really becomes clear when you look at how those richer payouts sit next to ...
There's only one way to know the right time to buy, sell or hold Furuno Electric. Head to Simply Wall St's company report for the latest analysis of Furuno Electric's Fair Value.
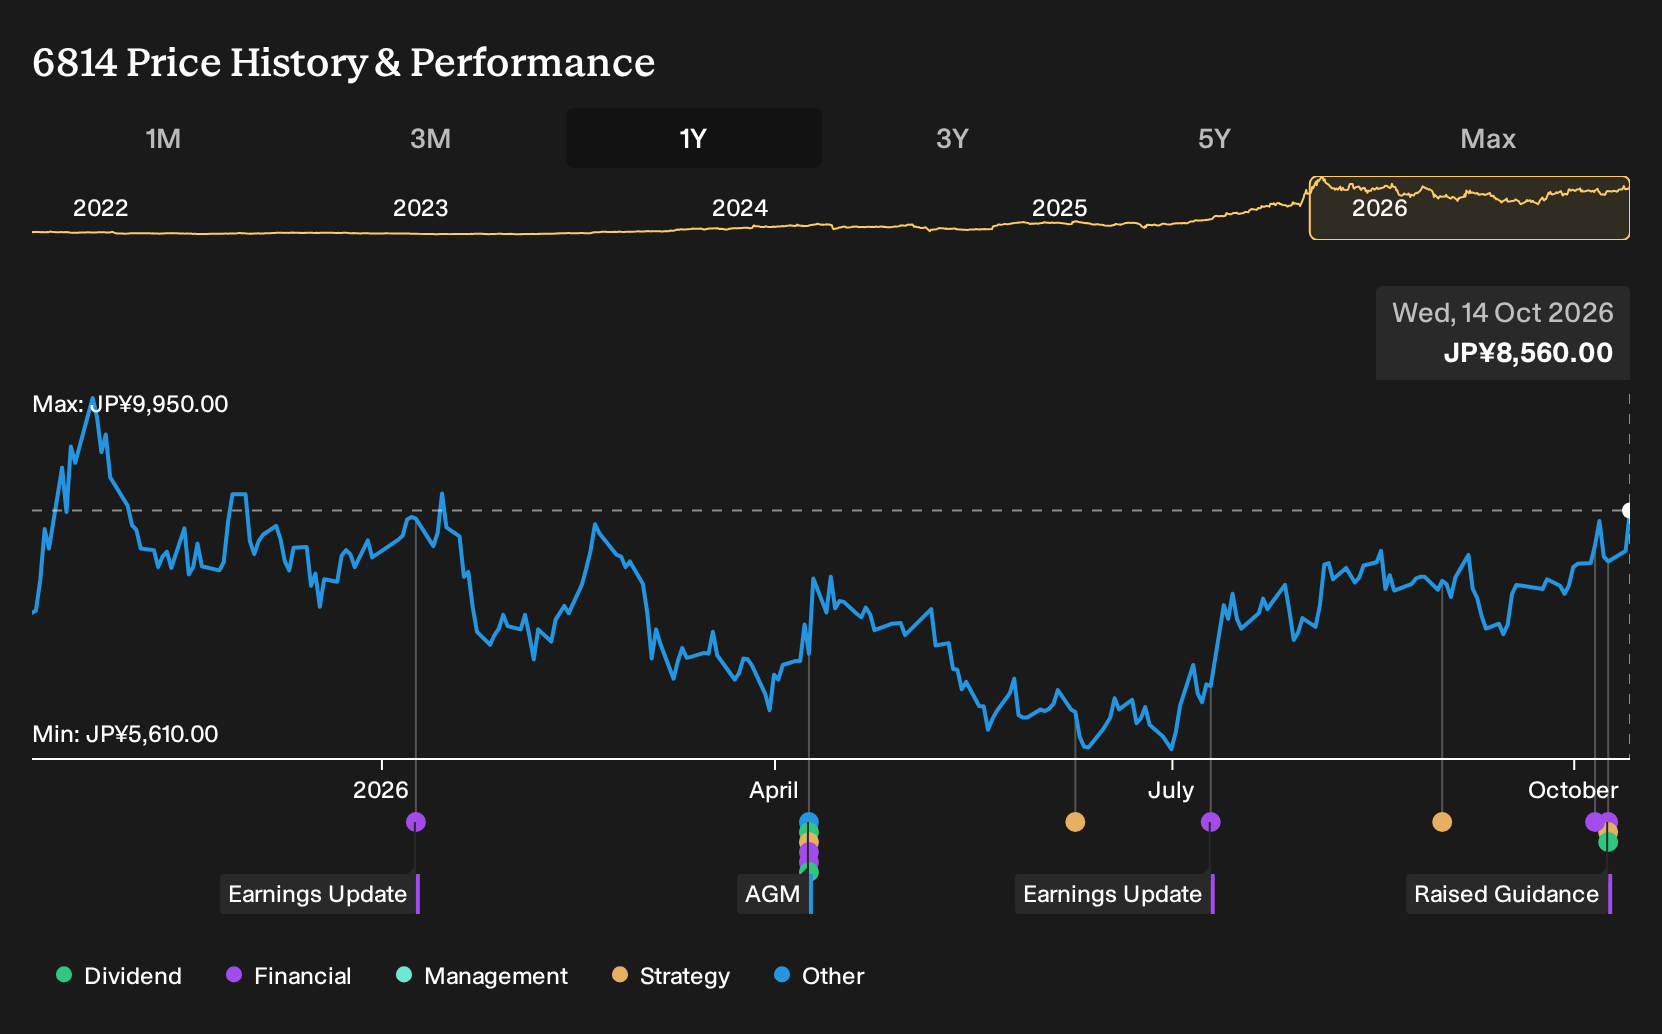
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Furuno Electric research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Furuno Electric. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Furuno Electric's overall financial health at a glance.
Looking For More Furuno Electric Style Ideas?
If Furuno Electric has you thinking about how to balance income, quality and risk in your portfolio, it can help to line it up against a wider set of opportunities with similar traits.
- For investors hunting for income without completely sacrificing balance sheet strength, scan a curated 28 dividend fortresses that share a similar yield focused profile.
- If valuation discipline is your anchor, compare Furuno Electric with a broader pool of companies through a focused set of 15 high quality undervalued stocks that pass tighter quality and pricing filters.
- When capital preservation sits higher on your priority list than headline yield, widen your research to a carefully selected 23 resilient stocks with low risk scores that aim to keep downside risk in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com