


- Hilton Grand Vacations has opened Ka Haku, a Hilton Club in central Waikiki, adding a 205 unit, amenities rich resort as its 14th Hawaii property and first Hilton Club branded site in the state.
- The resort leans heavily on sustainability features, culturally informed design and a Japanese style bathhouse concept, which deepens Hilton Grand Vacations' ability to target higher end, experience driven vacation ownership demand in Hawaii.
- This development provides a new reference point for understanding how Hilton Grand Vacations' investment narrative is shaped by Ka Haku's boutique, sustainability focused Hilton Club launch.
Scan beyond Hilton Grand Vacations and Ka Haku by reviewing a hand picked group of hospitality and travel operators with resilient fundamentals in our list of solid balance sheet and fundamentals (25 results).
Hilton Grand Vacations Investment Narrative Recap
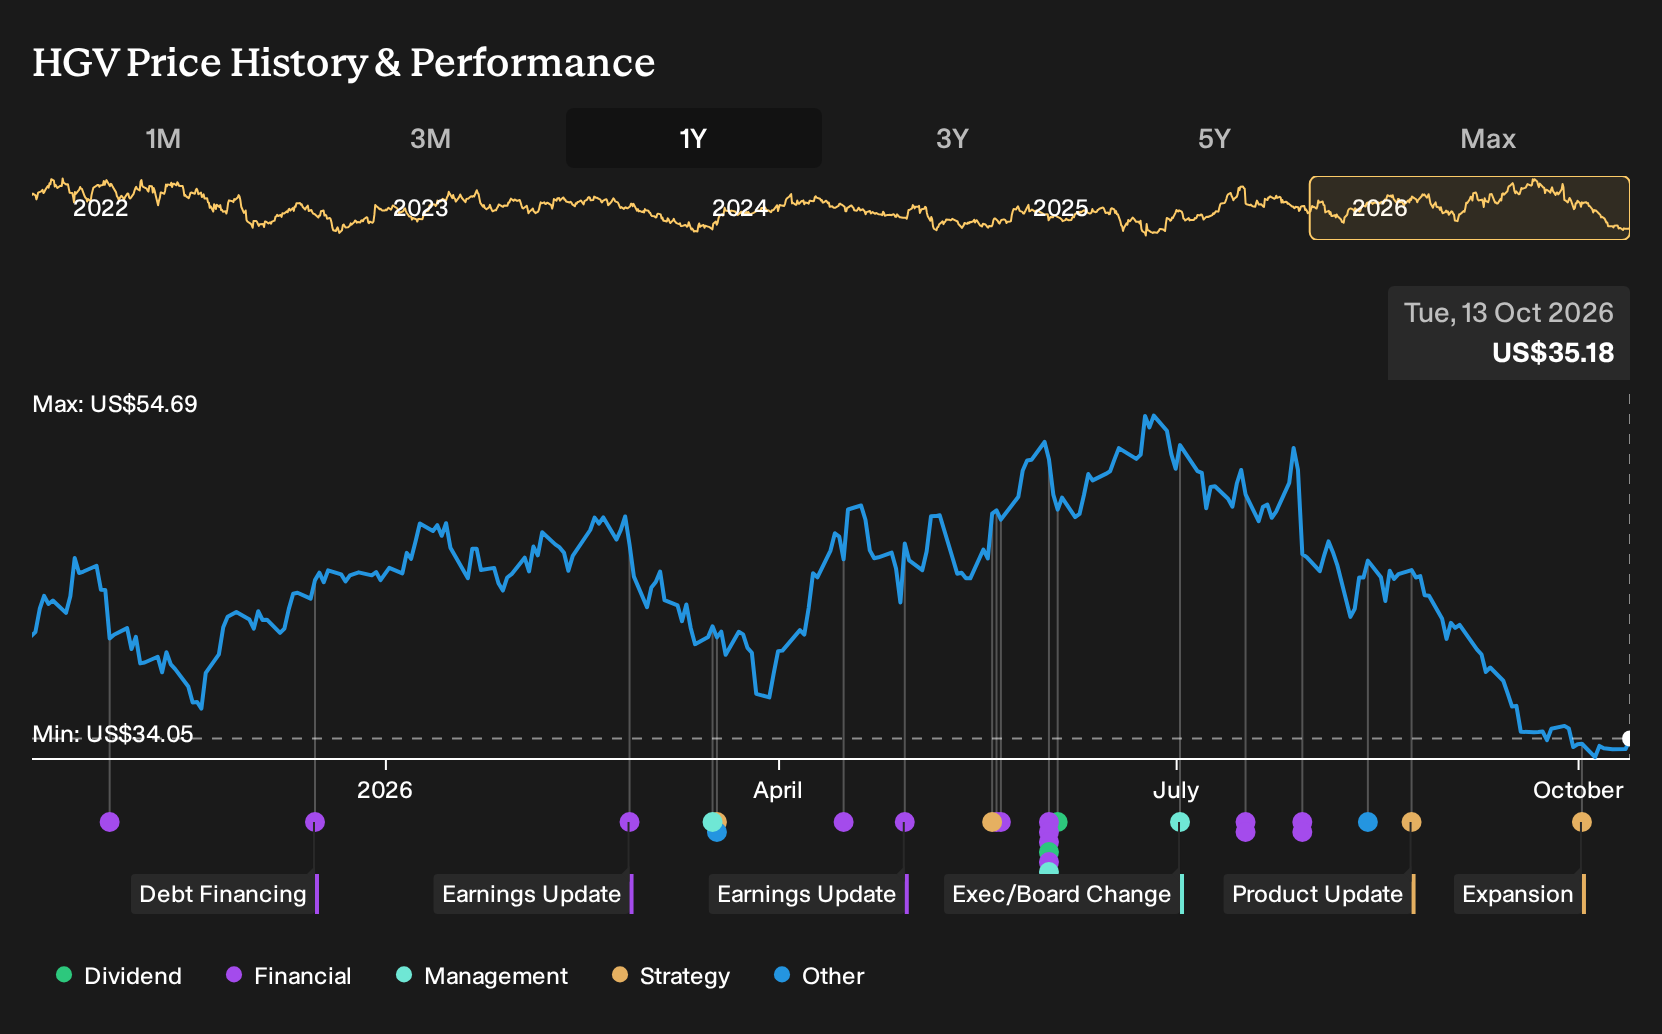
For Hilton Grand Vacations, the core belief is that a scaled, three tier platform can support vacation ownership demand while the firm works to convert more of its US$4.7b in revenue into free cash flow. The Ka Haku opening supports that idea, but does not change the near term focus on stabilizing tours, VPG and contract sales after recent softness.
The biggest near term swing factor remains whether management can keep loan loss provisions in check after they reached 17% of owned contract sales in Q2 2026. Elevated leverage of 3.8x net and meaningful interest costs leave less room for operational misses if sales trends or credit quality weaken.
The Ka Haku launch matters most because it leans into the Hilton Club tier, which analysts already viewed as a key part of the broader platform of more than 200 properties. A boutique, amenities heavy resort in central Waikiki gives Hilton Grand Vacations another way to segment higher spending guests and potentially support VPG over time.
Ka Haku also highlights how new openings intersect with the push to lower inventory cash spend and improve free cash flow conversion. Investors watching catalysts may track whether this resort, built with sustainability features and a differentiated bathhouse and lounge concept, drives efficient contract sales without putting fresh pressure on receivables quality or inventory capital needs.
Hilton Grand Vacations' narrative projects US$6.3b revenue and US$554.9 million earnings by 2029. This assumes 10.2% yearly revenue growth and an earnings increase of roughly US$404 million from US$151.0 million today.
Uncover why Hilton Grand Vacations' fair value indicates a 61% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view around Hilton Grand Vacations focuses on earnings power rather than VPG pressure. The most cautious analysts were only modeling about US$5.9b of revenue and roughly US$475.8 million of earnings by 2029, which is well below the consensus path. That gap shows how far opinions can differ and why you may want to compare several pre Ka Haku forecasts and decide which assumptions feel more realistic to you as new information arrives.
Explore 3 other Hilton Grand Vacations fair value estimates, including one that suggests as much as 99% downside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Hilton Grand Vacations research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Hilton Grand Vacations. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hilton Grand Vacations' overall financial health at a glance.
Looking For More Investment Ideas Beyond Hilton Grand Vacations?
If the Ka Haku story has sharpened how you think about Hilton Grand Vacations, use that same lens across the wider market. The Simply Wall St Screener lets you quickly filter for balance sheets, income profiles and risk levels that match your own checklist rather than someone else's model.
- If capital preservation sits high on your priority list, start with a focus on resilience and see which businesses make it into the 32 resilient stocks with low risk scores.
- Income focused investors who want yield backed by fundamentals can zero in on companies that look more like dependable cash machines by reviewing the 8 dividend fortresses.
- If you prefer to look where fewer eyes are currently focused, broaden your watchlist with the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com