


Swiss Re (SWX:SREN) came under fresh scrutiny after Jefferies downgraded the stock, pointing to faster declines in reinsurance pricing since 2025 and questioning the group’s revenue and earnings assumptions.
Swiss Re’s recent downgrade coincides with strengthening share price momentum, with the stock posting a 30-day share price return of 6.14% and a year-to-date gain of 12.91% at a latest share price of CHF146.95.
Pressure test the Jefferies downgrade on Swiss Re against peers by scanning insurers with steadier pricing power and earnings support using our curated list of list of solid balance sheet and fundamentals (202 results).
For Swiss Re, a rising share price set against cautious broker views creates a fork in the road. Are investors paying up for sturdier fundamentals, or just leaning into a sentiment rebound that the current valuation needs to justify next?
Most Popular Narrative: 13% Overvalued
Swiss Re’s most followed valuation storyline currently pegs fair value at CHF130.24, which sits below the latest CHF146.95 closing price and frames today’s optimism as relatively full.
Shift in business mix away from volatile casualty exposure toward higher-margin property and specialty lines, combined with disciplined capacity deployment in attractive geographies and product segments, is expected to improve risk-adjusted returns, bolster portfolio resilience, and support stable or improving combined ratios and bottom line profitability. Swiss Re's strategic focus on cost optimization, on track to deliver over $300 million in cost reductions by 2027 together with robust capital buffers, positions the company to navigate cyclical downturns and regulatory changes. This combination is viewed as increasing the potential for sustained earnings growth and improved return on equity.
See why 69 investors see Swiss Re as 13% overvalued.
Result: Fair Value of CHF130.24 (OVERVALUED)
Still, softer pricing in Corporate Solutions and cuts to casualty reinsurance volumes leave Swiss Re exposed to thinner margins and bumpier earnings than this narrative assumes.
Find out about the key risks to this Swiss Re narrative.
Another View: What Swiss Re’s P/E Is Saying
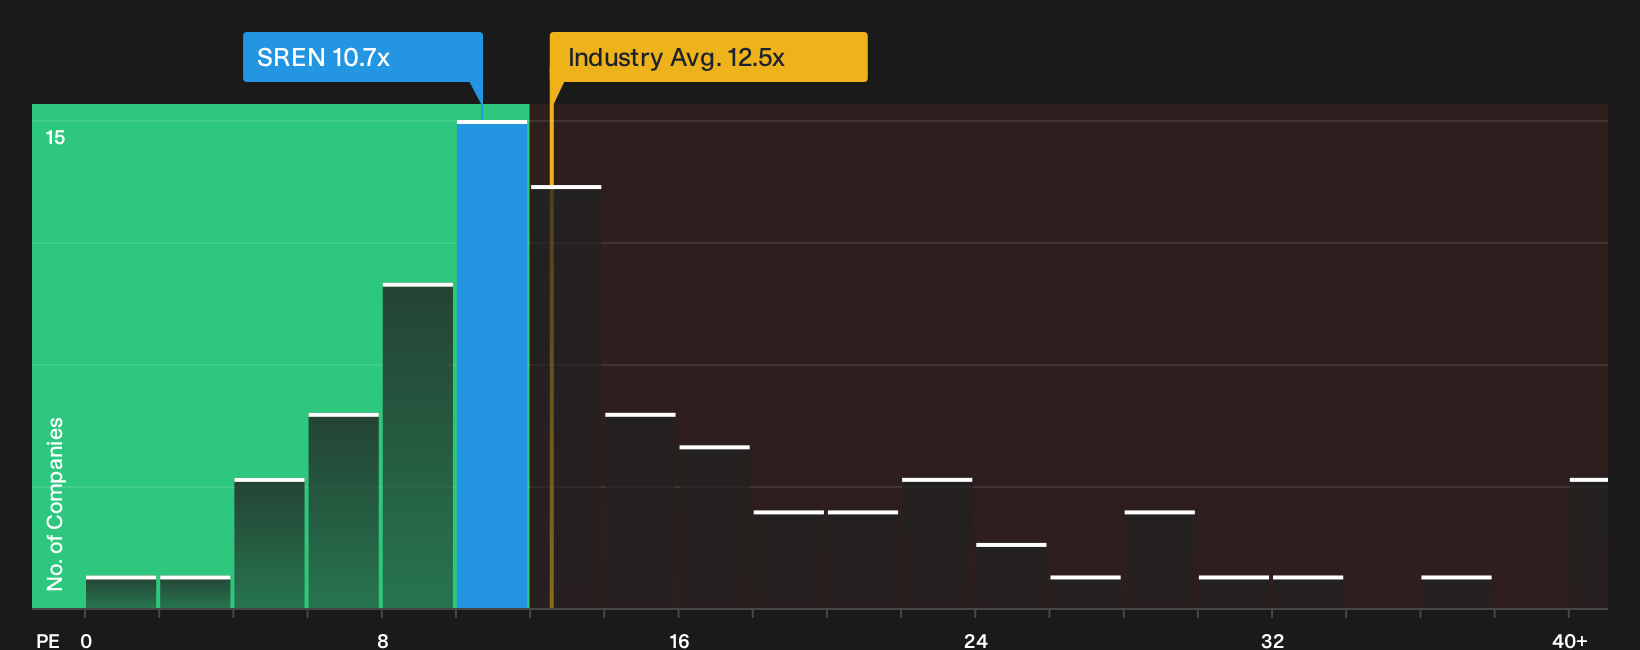
Analysts frame Swiss Re as 13% overvalued on their CHF130.24 fair value, yet its valuation ratio tells a different story. The shares trade on a P/E of 10.7x, compared with 12.5x for the European insurance sector and a fair ratio of 17.7x that the market could move towards. That kind of gap can either flag upside potential if earnings hold up or signal that investors still want a discount for softer growth and pricing risk. Which explanation fits your own expectations best?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Swiss Re only matter if you translate them into your own plan. Weigh the concerns and the upside by reviewing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Swiss Re?
Do not stop your research with Swiss Re. A few minutes spent scanning other high quality setups can often reveal opportunities that fit your style even better.
- Target sturdier businesses with healthy finances and consistent support by running your filters through our list of solid balance sheet and fundamentals (202 results).
- Zero in on potential value opportunities that pair strong fundamentals with pricing that still looks reasonable using the 187 high quality undervalued stocks.
- Build a cash flow focused plan around dependable income candidates by checking the 217 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com