


Global debt strains, stubborn inflation and pressure from the IMF for tighter government budgets are reshaping where capital flows and how risk is priced. That shift can reward investors who understand which asset managers and private-credit specialists are positioned for sovereign and emerging-market debt stress, and which are not. This article walks through 3 stocks from our screener that appear well placed against this backdrop and explains why the current news matters for each one.
The three stocks covered next are only a sample from this idea. The full screen surfaced 42 more listed asset managers and private-credit specialists with similarly detailed stories around sovereign and emerging-market debt.
To size up that broader opportunity set quickly, head straight into the Global Asset Managers and Private-Credit Firms Positioned for Sovereign and EM Debt Restructuring screener to identify, filter and analyze the higher conviction potential plays.
Brookfield Asset Management (TSX:BAM)
Brookfield Asset Management sits near the center of this screener’s story, with a broad private markets platform and sizeable credit arm that can plug into complex sovereign and emerging market restructurings while still leaning on diversified fee income.
Brookfield Asset Management runs a global alternatives platform across real assets and private credit, with Credit generating US$1.8b in revenue alongside sizeable Infrastructure, Real Estate and Energy fee streams, and a market value of about CA$102.9b anchoring its scale.
"Growing allocations from institutional, insurance and individual investors into private markets are supporting the expansion of fee-bearing capital, which is already at US$603b and directly tied to future fee-related revenue and distributable earnings."
What matters next is how one quiet pressure on this fee engine reshapes the balance between headline growth and the profitability investors care about.
That trade off is where the real story sits, and the full narrative for Brookfield Asset Management unpacks how Brookfield Asset Management’s fee engine, payout capacity and credit ambitions intersect.

Partners Group Holding (SWX:PGHN)
Partners Group Holding plugs neatly into this theme as a global private-markets platform, where private credit and special situations investing can intersect with complex sovereign and emerging market restructurings when institutional clients seek bespoke capital solutions rather than traditional bond market exposure.
Partners Group Holding runs a multi-asset private markets platform, with revenue anchored in Private Equity at CHF 1.3b, followed by Infrastructure at CHF 634 million, Real Estate at CHF 226 million and Private Credit at CHF 259 million, and the stock is valued at about CHF 15.5b.
"Expansion into private credit, infrastructure, royalties, and real estate, alongside a multi-region distribution network and solutions-based offerings, provides operational diversification that can stabilize and gradually lift management fee income and realized performance fees, supporting margin resilience and reducing segment-specific shocks."
What really matters from here is how one less visible funding pressure resolves, because that could meaningfully sway how much of those future fees fall through to profits.
If that pressure point has your attention, the full narrative for Partners Group Holding shows how Partners Group Holding’s funding mix, fee momentum and risk-sharing structures could be quietly decoupling.

CVC Capital Partners (ENXTAM:CVC)
CVC Capital Partners taps directly into this screener’s theme through its global alternatives platform, where private equity, credit and infrastructure strategies can be pointed at complex, often stressed borrowers that sit close to sovereign and emerging market debt issues.
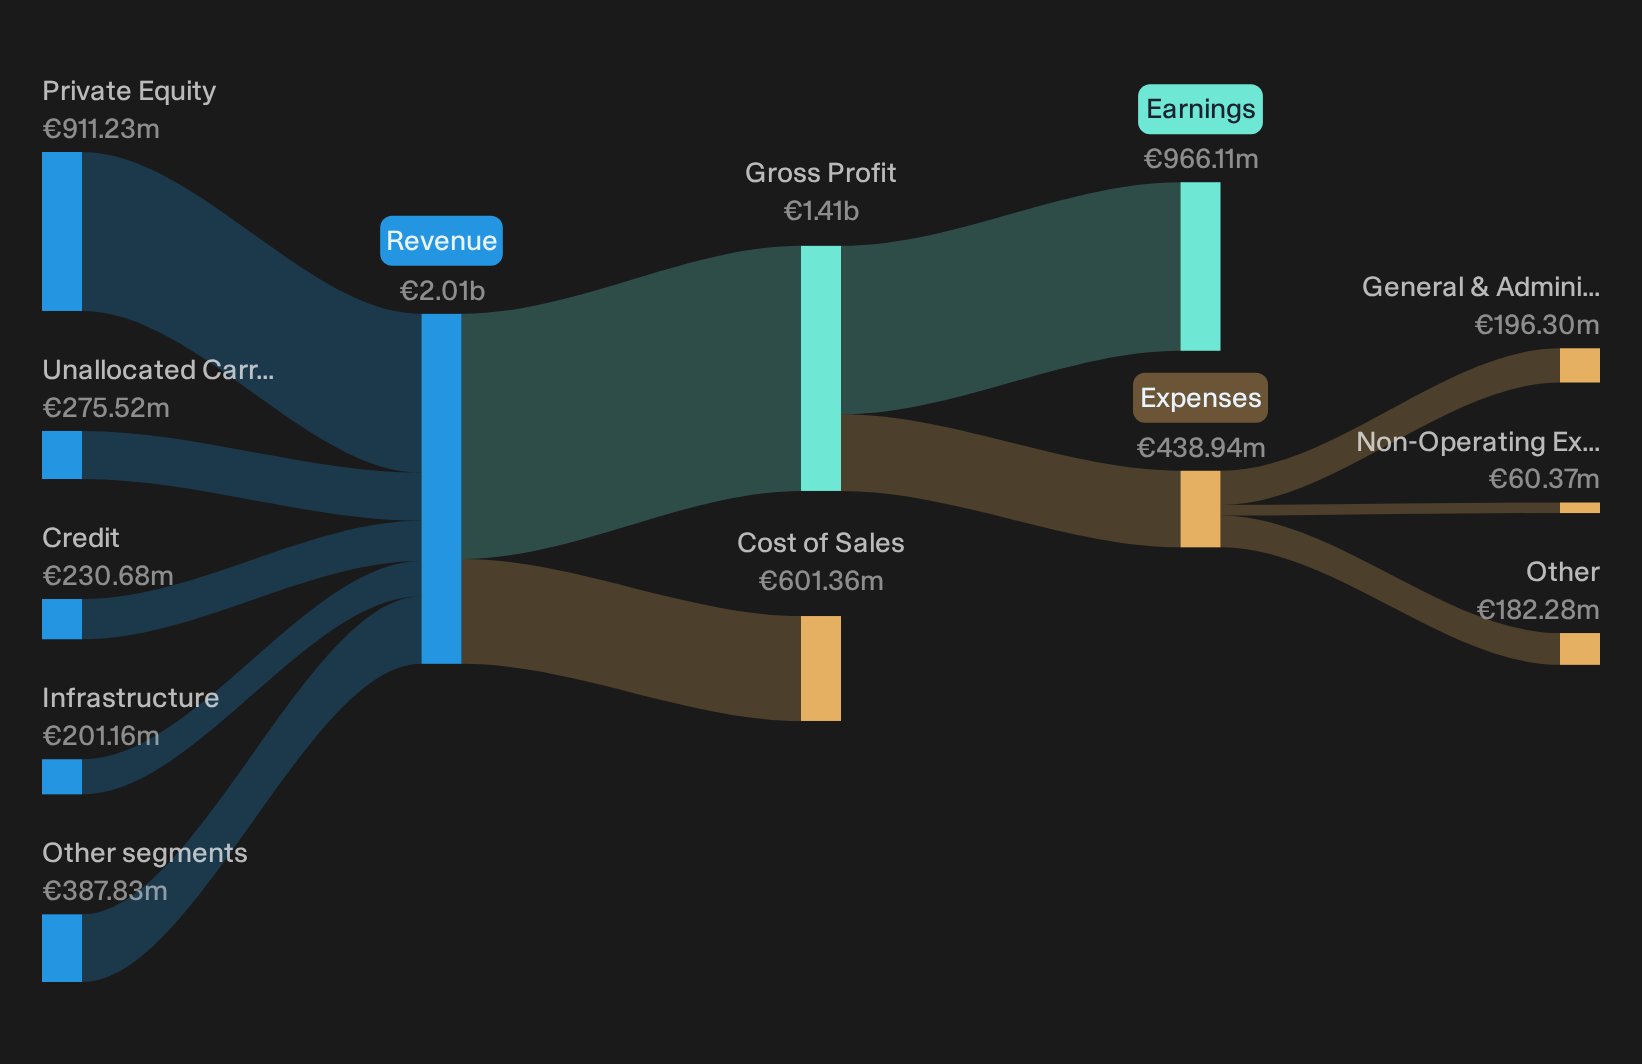
CVC Capital Partners runs a broad alternatives platform, with Private Equity generating about €911 million of revenue, Credit €231 million, Infrastructure €201 million and Secondaries €174 million, plus unallocated income lines, and the stock carries a market value around €12.7b.
"Strategic expansion into Private Wealth and insurance, with initiatives like CVC CRED and CVC PE, highlights a focus on long term revenue growth and diversification of fee income sources."
What could really shift the story is how one funding and governance pressure affects the returns investors eventually see from those higher risk credit opportunities.
If that tension between funding pressure and eventual returns has your attention, the full narrative for CVC Capital Partners shows whether CVC Capital Partners’ expanding platform is quietly accelerating or masking risk.
Seeking Alternatives Beyond Your Current Watchlist?
Fresh ideas often move first. By the time momentum builds and prices move quickly, early entry points may no longer be available and spreads may widen. Review these focused stock lists ahead of the wider market.
- Spot potential income opportunities by targeting companies in the 2 dividend fortresses that aim to maintain their dividend payments while prices and yields may still be less widely followed.
- Follow structural demand shifts by examining the 43 power grid technology and infrastructure stocks where spending on grid upgrades, electrification and reliability may influence which suppliers secure new orders.
- Identify under-followed growth stories by reviewing the 10 high quality undiscovered gems before they attract broader attention, when entry points may still appear accessible and liquidity may have room to develop.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com