


As the Asian markets navigate a landscape marked by geopolitical tensions and fluctuating energy prices, investors are increasingly looking towards niche opportunities that offer potential growth. Penny stocks, though often seen as remnants of earlier market eras, continue to capture interest due to their affordability and potential for significant returns. These smaller or newer companies can provide a unique blend of value and growth when they possess strong financials, making them intriguing prospects for those seeking under-the-radar investments with promising outlooks.
Let's review some notable picks from our screened stocks.
Fufeng Group (SEHK:546)
Simply Wall St Financial Health Rating: ★★★★☆☆
Overview: Fufeng Group Limited is an investment holding company that manufactures and sells fermentation-based food additives, biochemical, and starch-based products in China and internationally, with a market cap of HK$11 billion.
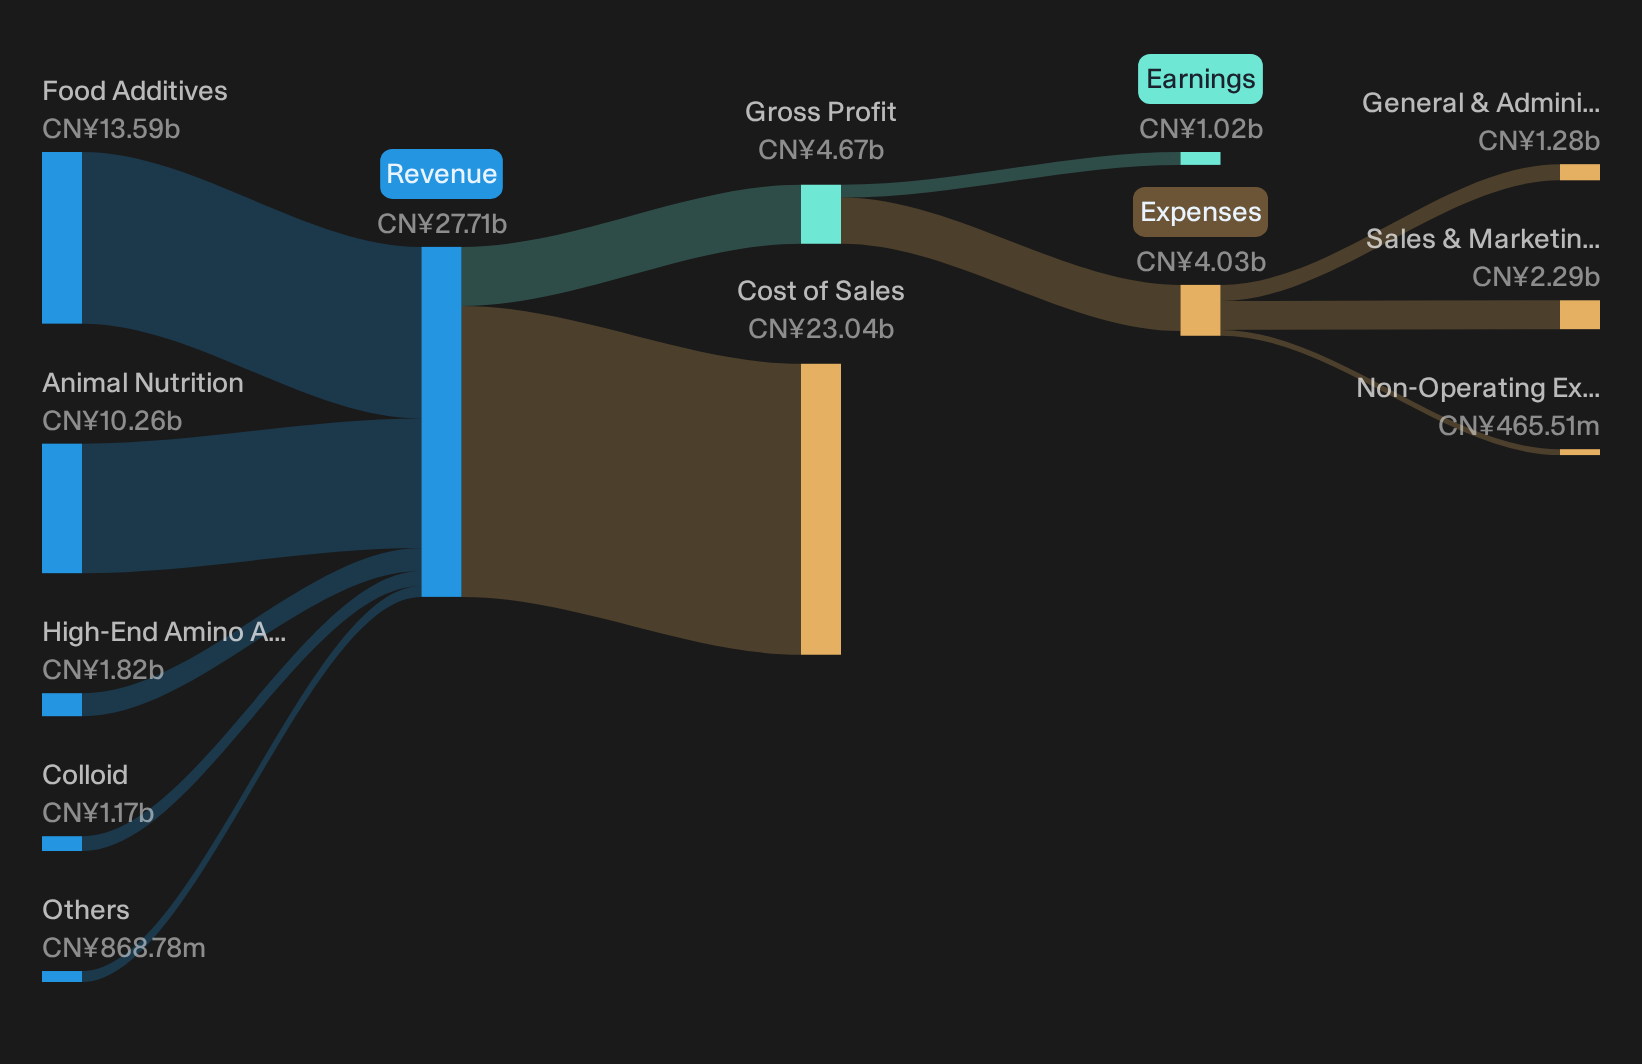
Operations: The company's revenue is primarily derived from its Food Additives segment at CN¥13.59 billion, followed by Animal Nutrition at CN¥10.26 billion, High-End Amino Acid at CN¥1.82 billion, and Colloid products contributing CN¥1.17 billion.
Market Cap: HK$11B
Fufeng Group Limited, with a market cap of HK$11 billion, faces challenges typical of penny stocks. Its recent financials show declining net income from CN¥1.79 billion to CN¥346.56 million year-over-year, impacted by a significant one-off gain. Despite trading at 40% below estimated fair value and having stable short-term asset coverage, its debt-to-equity ratio has risen sharply over five years to 108.5%. The company's dividend yield is high but not well-supported by free cash flow, raising sustainability concerns. Recent actions include share buybacks and dividend announcements, reflecting efforts to manage shareholder value amidst volatile earnings growth forecasts.
- Click here and access our complete financial health analysis report to understand the dynamics of Fufeng Group.
- Gain insights into Fufeng Group's future direction by reviewing our growth report.
DongGuan Winnerway Industry Zone (SZSE:000573)
Simply Wall St Financial Health Rating: ★★★★☆☆
Overview: DongGuan Winnerway Industry Zone LTD. operates in the real estate development sector in China with a market capitalization of CN¥2.76 billion.
Operations: The company generates its revenue primarily from operations within China, amounting to CN¥626.09 million.
Market Cap: CN¥2.76B
DongGuan Winnerway Industry Zone LTD., with a market cap of CN¥2.76 billion, presents a mixed picture for investors. Recent earnings show sales growth to CN¥319.03 million for H1 2026, yet net income declined to CN¥45.24 million from the previous year. The company's profit margins have dropped significantly from 12.7% to 2%, and its return on equity is low at 0.7%. While short-term assets cover liabilities comfortably and debt levels are reduced, operating cash flow remains negative, indicating potential liquidity challenges despite having more cash than total debt. The management team is experienced but faces hurdles in reversing negative earnings trends.
- Take a closer look at DongGuan Winnerway Industry Zone's potential here in our financial health report.
- Review our historical performance report to gain insights into DongGuan Winnerway Industry Zone's track record.

Beijing Watertek Information Technology (SZSE:300324)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: Beijing Watertek Information Technology Co., Ltd. operates in the information technology sector with a market cap of approximately CN¥6.60 billion.
Operations: The company generates revenue primarily from its Software and Information Technology Services Industry segment, amounting to CN¥1.65 billion.
Market Cap: CN¥6.6B
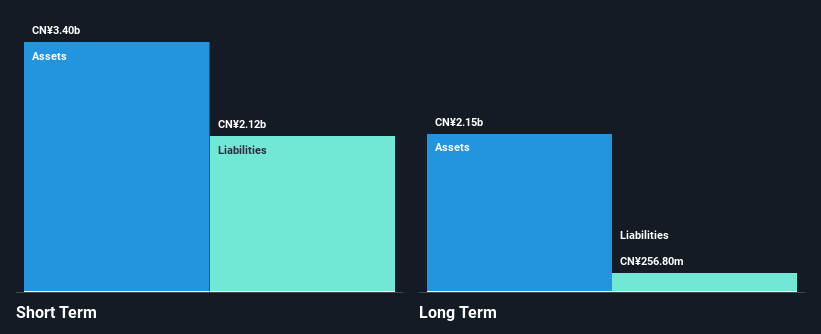
Beijing Watertek Information Technology Co., Ltd., with a market cap of CN¥6.60 billion, remains unprofitable but has reduced losses by 16.4% annually over five years. Despite a negative return on equity of -19.19%, its seasoned management and board offer stability, with average tenures exceeding industry norms. The company's short-term assets cover both short- and long-term liabilities comfortably, and it maintains a cash runway exceeding three years even as free cash flow declines. Recent earnings reveal declining revenue from CN¥1.05 billion to CN¥610 million year-over-year, alongside an increased net loss, highlighting ongoing financial challenges amidst stable shareholder equity levels.
- Unlock comprehensive insights into our analysis of Beijing Watertek Information Technology stock in this financial health report.
- Evaluate Beijing Watertek Information Technology's historical performance by accessing our past performance report.
Key Takeaways
- Access the full spectrum of 1,047 Asian Penny Stocks by clicking on this link.
- Searching for a Fresh Perspective? Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com