


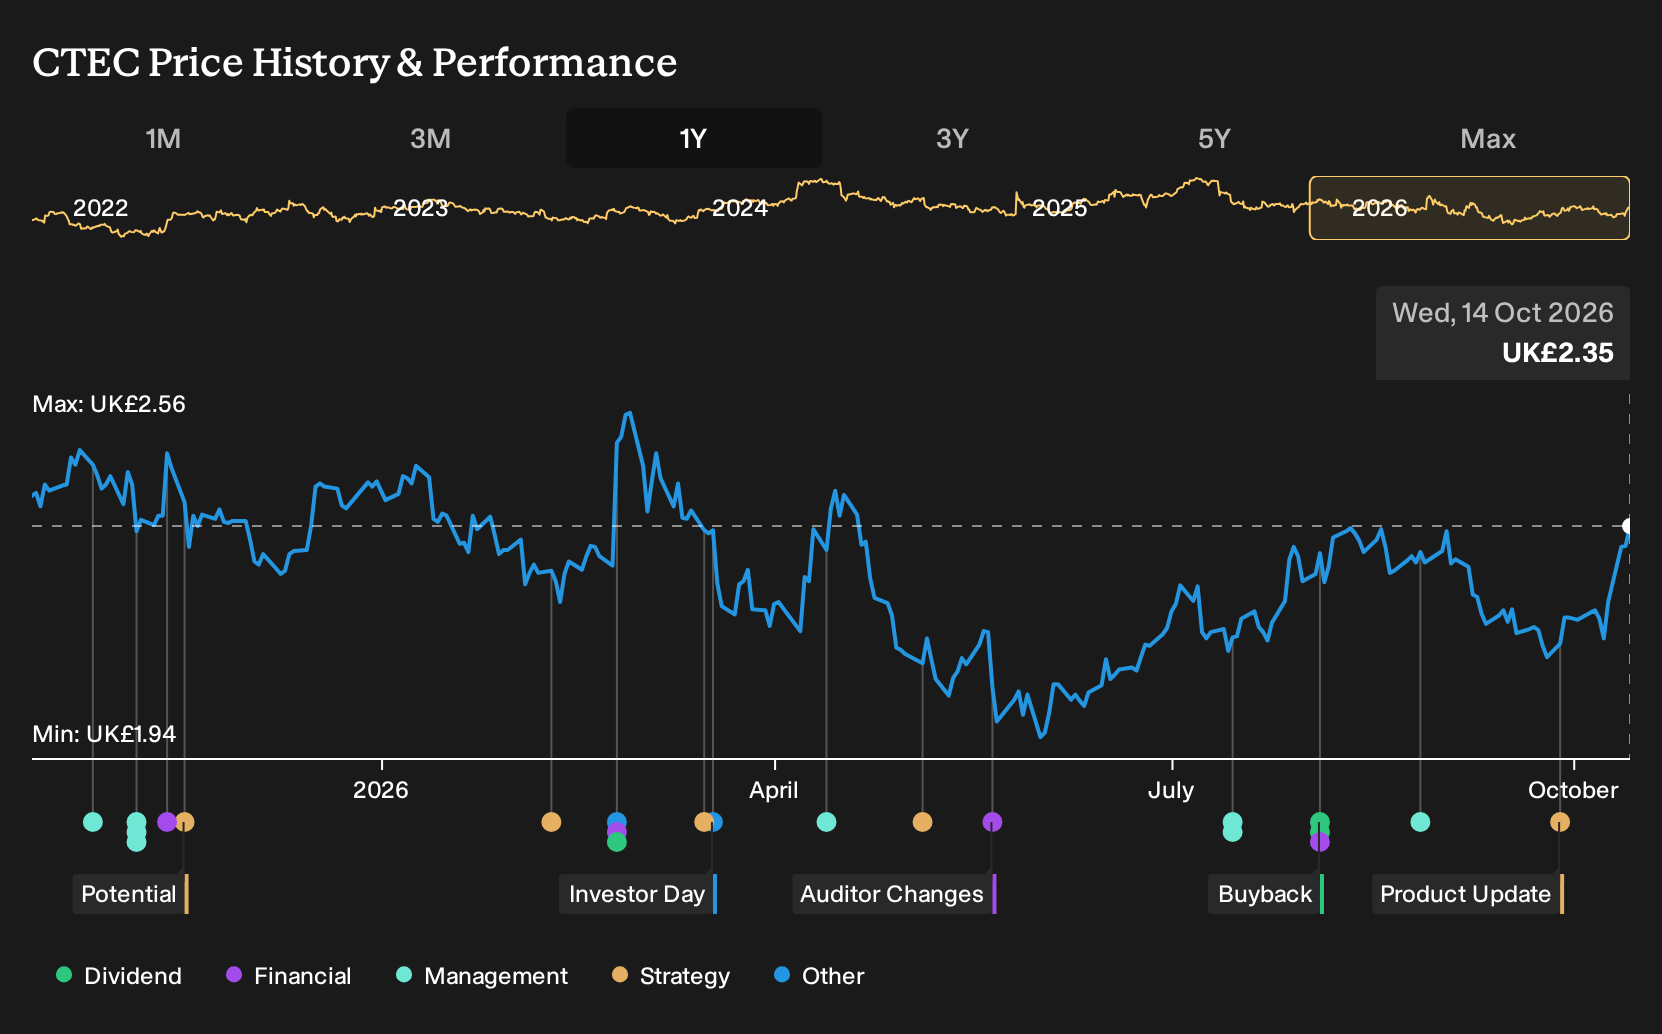
- Convatec Group recently emerged as the strongest performer on the FTSE 100 on a day when London markets were lifted by gains in banks and defence stocks, alongside rising Brent crude prices following supply concerns.
- The move highlighted how Convatec Group’s medical devices profile can benefit from shifts in macro expectations around energy inflation and Bank of England policy, even without company specific news.
- We will now explore how Convatec Group’s investment narrative could be influenced by this macro driven rally tied to softer energy inflation.
See how Convatec Group’s move fits into the wider defensives theme by comparing it with hand picked healthcare and resilient operators on the 4 resilient stocks with low risk scores
Convatec Group Investment Narrative Recap
To own Convatec Group, you need to be comfortable with a story that leans on steady demand for chronic care products, ongoing product development and execution on cost programs. The short term focus is whether management can turn that pipeline and efficiency work into cleaner earnings after a period of one off items and thinner margins. The latest macro driven share price move does not materially change that operating challenge.
The biggest swing factor right now is reimbursement and pricing, especially in the U.S., where proposed CMS changes could pressure up to 12% of revenue and squeeze margins if price cuts bite harder than any volume uplift. A key risk for shareholders is that mature product lines and rising competition meet tougher reimbursement at the same time, which would make it harder for Convatec Group to translate revenue growth into free cash flow and cover its dividend comfortably.
Recent communication around reimbursement risk is the most relevant backdrop for this kind of macro led rally. The market move came on the day banks and defence stocks climbed, with Convatec Group riding that risk sentiment rather than releasing fresh operating news. For an investor, the interesting link is that lower expectations for energy driven inflation could ease rate pressures without doing anything to change CMS proposals or competitive bidding.
That disconnect matters. The catalysts investors are watching, such as product rollouts in wound and ostomy care, biologics adoption and cost efficiency programs, all sit alongside the risk of sustained price cuts in key U.S. categories. Any future update on CMS decisions or pricing terms in ostomy, continence or biologics is likely to carry more weight for the business than another risk on day in London trading.
What The Current Convatec Group Forecasts Assume
Analyst models for Convatec Group line up around a relatively clear set of numbers, even if opinions differ on how generous those figures are. Revenue is projected to grow by 6.1% a year over the next three years, which, if achieved, would reflect steady expansion rather than a rapid step change. Profitability assumptions are more ambitious, with margins expected to move from 7.2% today to 14.7% by around 2029, effectively doubling the share of sales that drops through to the bottom line.
On earnings, consensus sits at US$175.0 million today and points to US$428.9 million by about 2029, with the most optimistic forecasts stretching as high as US$510.2 million. That central view implies earnings a little over 2.4x higher than current levels, driven by both modest top line growth and much fatter margins. These projections also bake in a shrinking share count, with analysts assuming outstanding shares decline by roughly 4.39% per year for the next three years, which would mechanically lift earnings per share if profits track the forecasts.
Valuation work then ties those operating projections back to what investors are paying for Convatec Group today. To match the analyst fair value framework, the stock would need to trade on a P/E of 20.3x those 2029 earnings, down from 30.6x currently and below the cited 31.9x for the wider GB medical equipment peer group. Discount rates around 8.4% feature in these models, which is one way of reflecting the risk analysts see around reimbursement, execution on the product pipeline and the wider macro backdrop.
Convatec Group's narrative projects US$2.9b revenue and US$428.9 million earnings by 2029. This rests on 6.1% yearly revenue growth and an earnings increase of about US$253.9 million from US$175.0 million today.
Uncover why Convatec Group's fair value indicates a 29% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between 3.02 and 4.25, which already shows how far retail opinions on Convatec Group can stretch. Those views were set before the recent energy shock and renewed focus on CMS reimbursement risk, so treat them as starting points and explore multiple angles before deciding how this story fits your portfolio.
Explore another Convatec Group fair value estimate, including one that suggests as much as 81% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Convatec Group research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Convatec Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Convatec Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Convatec Group?
If Convatec Group has put healthcare on your radar, it can help to compare it with other opportunities that fit different goals, from balance sheet strength to income or potential mispricing. The Simply Wall St Screener lets you scan the market quickly so you can build a watchlist that reflects your own risk tolerance and return expectations.
- If resilience and financial strength are high on your checklist, start with a list of solid balance sheet and fundamentals (9 results) that can help you focus on companies with room to handle shocks and still fund growth.
- For readers aiming to build a future income stream, filter for potential yield opportunities by running through a 2 dividend fortresses that may suit a long term, cash flow focused portfolio.
- If you are hunting for ideas the market might be overlooking, broaden your opportunity set with a 5 high quality undiscovered gems that pairs strong fundamentals with lower investor attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com