


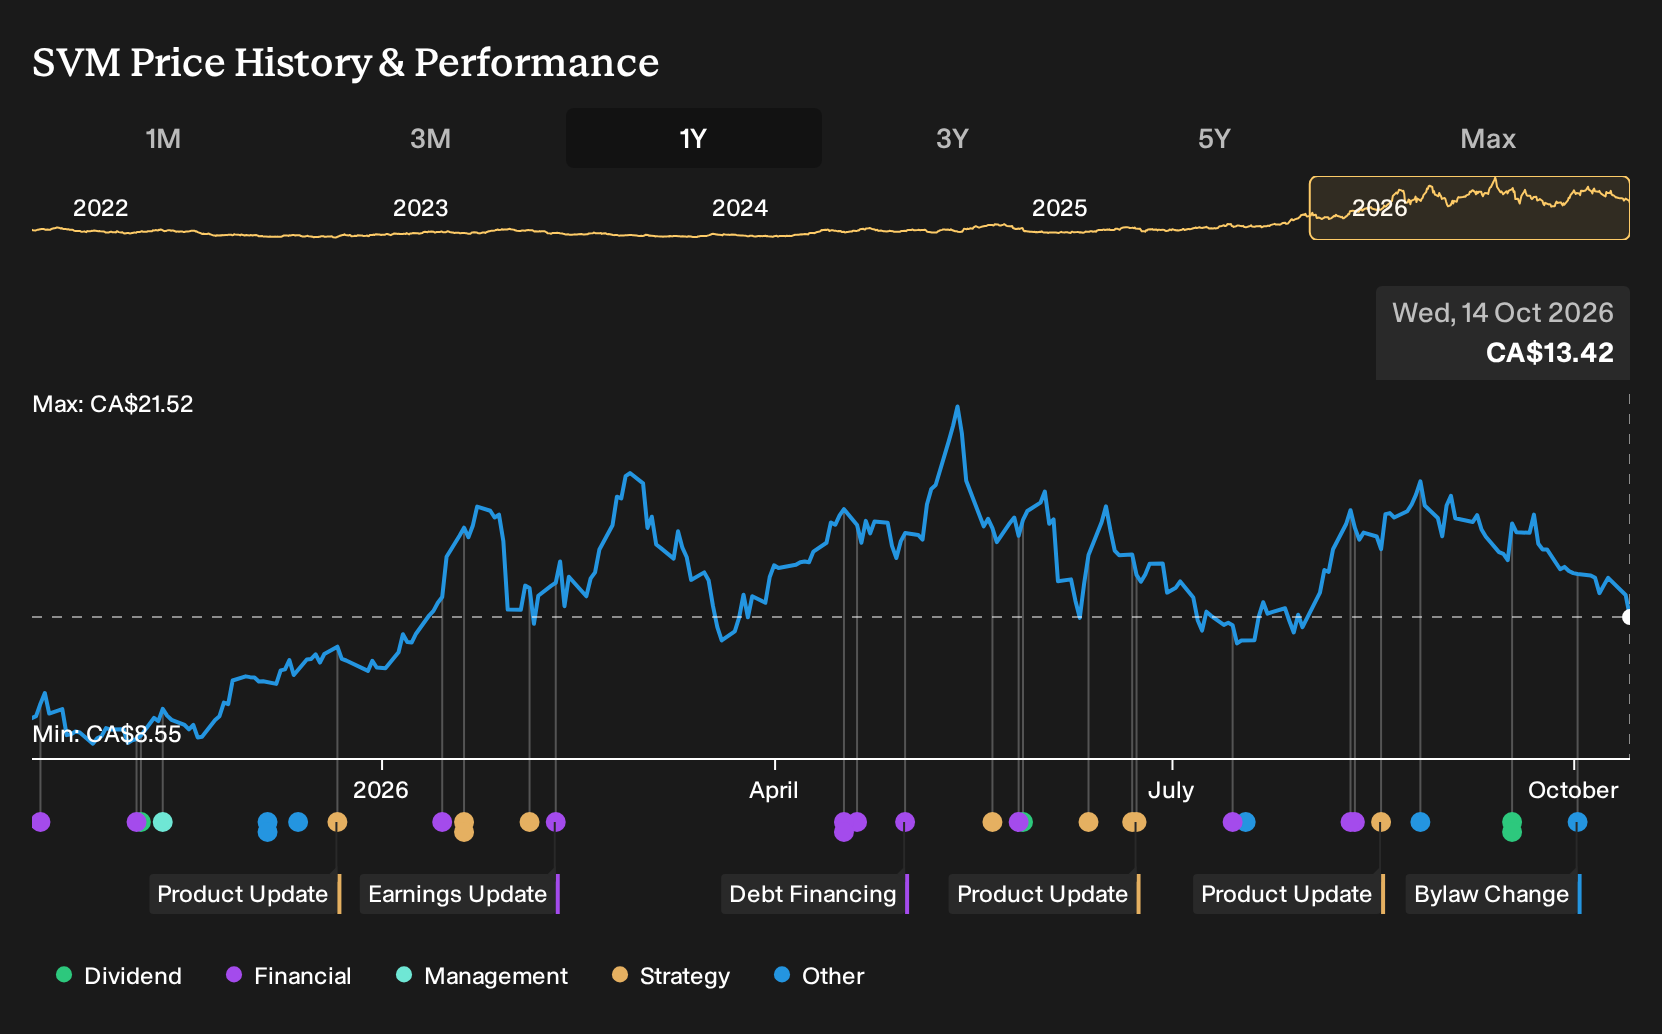
If you only glanced at the headlines about Silvercorp Metals pausing parts of its China operations for safety upgrades and pouring money into Kyrgyz and Ecuadorian projects, you might not expect a payoff. Investors who held Silvercorp Metals over the past year are up 33.4%, including dividends. If you had been weighing those political, regulatory and cost risks back on 2025-10-14, what did the available information really suggest you were being paid to accept?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Silvercorp Metals. Zero in on 7 high quality undervalued stocks for companies trading below our estimates.
What Investors Had To Weigh Up On Silvercorp Metals
The shares cost CA$9.61 at the start of the period, and anyone looking at Silvercorp Metals then was choosing between two very different reward for risk stories.
The bullish narrative argued for a Fair Value of CA$28.58, built on Silvercorp Metals growing revenue 91.6% and lifting profit margin to 23.1% over five years, supported by large silver resources and low stated cash costs.
The more cautious case pointed to a Fair Value of CA$8.76, assuming 27.4% revenue growth and a 38.1% margin, while stressing regulatory and operational risks in China and Ecuador.
What The Evidence Did To The Silvercorp Metals Argument
Silvercorp Metals reported Q1 2027 revenue of US$138.665m and net income of US$59.375m, with net margin rising from 22.3% to 42.8% versus Q1 2026. That profitability profile leans toward the bullish case that assumed higher earnings power, although the temporary China safety shutdowns kept the operational risk flagged in the cautious view in clear sight. Overall, the evidence cut both ways.
The key lesson is simple. When a thesis hinges on margins, track the reported net margin against the original assumption and see whether returns are coming from better economics or just a changing P/E.
What Silvercorp Metals' Price Already Assumes
Today Silvercorp Metals trades at CA$13.42. The selected Narrative argues that Fair Value sits above that level and leans heavily on fresh projects in Kyrgyzstan and Ecuador plus a larger silver footprint to justify the gap.
Anyone buying now is effectively judging whether multi country expansion and higher silver driven output can materialise without margin damage from higher costs or disruptions.
"Silvercorp is poised to benefit from sustained global growth in demand for silver driven by the ongoing transition toward renewables and electrification (notably solar, EVs, and battery storage), which should support higher realized prices and revenue growth, especially given that 66% of its Q1 revenue was generated from silver."
One Narrative disagrees with today's price. → See where this Narrative says Silvercorp Metals should trade
Before The Next Story Makes Headlines
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 47% below our estimate - accelerates higher grade ore feed at multiple operations to improve unit economics.
- Company 2 - 28% below our estimate - uses a high margin core mine to reinvest in adjacent deposits and processing.
- Company 3 - 42% below our estimate - rides increasing hyperscaler demand for advanced networking and AI systems to extend contracts.
That is three of the list. See all 8 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com