


- Mirvac Group’s Mirvac Wholesale Office Fund has purchased a half stake in Sydney’s 5 Martin Place from Cbus Property for A$394 million, alongside contracts to acquire a 50% interest in 171 Collins Street in Melbourne, extending its exposure to premium office assets.
- The transactions highlight Mirvac’s ongoing capital allocation into high quality office properties at a time when Cbus Property is reweighting toward large regional retail centres. This underlines different views on risk, income mix, and future leasing demand.
- We will now look at how Mirvac Group’s broader investment narrative could be shaped by the Wholesale Office Fund’s sizeable 5 Martin Place acquisition.
Mirvac Group Investment Narrative Recap
To own Mirvac Group, you need to be comfortable with a property platform that leans heavily on development earnings and capital partnering, alongside a large office and residential footprint. The key near term swing factor remains execution on the development pipeline, where any repeat of past project issues or cost pressure would quickly feed through to earnings and margins.
The fresh exposure to prime CBD offices through 5 Martin Place and 171 Collins Street does not materially change that near term story. The bigger immediate risk still sits with project delivery, housing demand and asset sale timing. The main opportunity is cleaner execution on already committed projects rather than this single office acquisition.
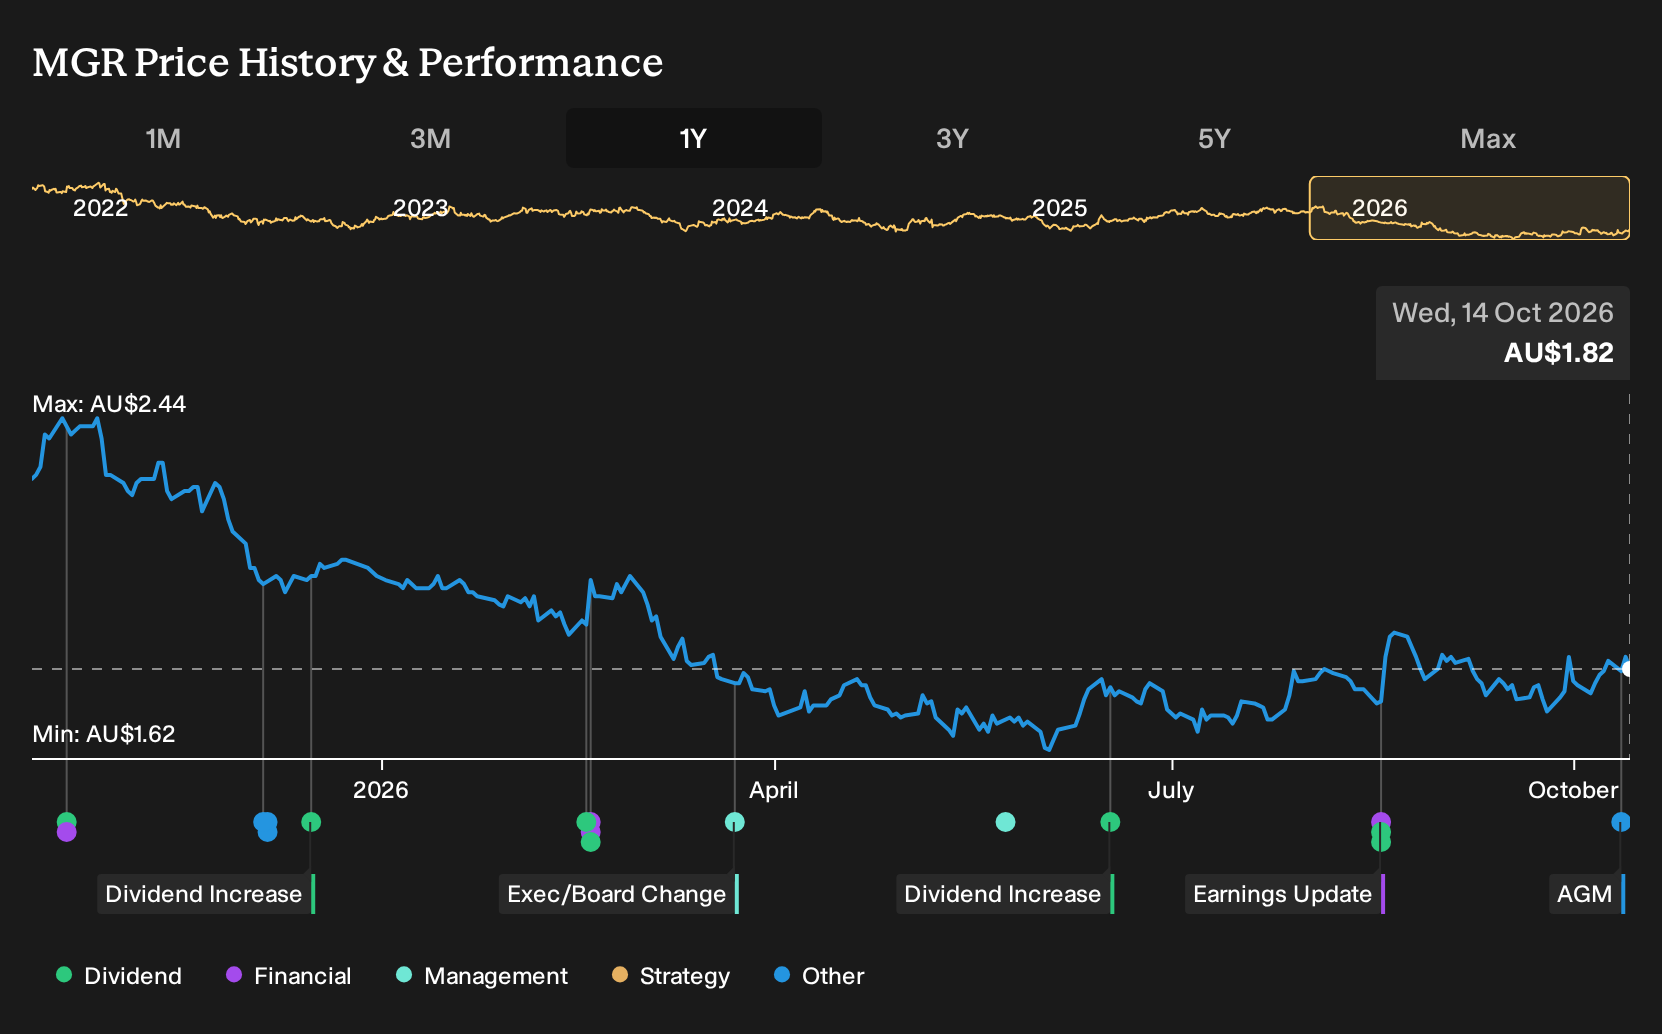
The most relevant fresh datapoint for this office transaction is not financial; it is governance. Mirvac Group’s 2026 AGM and General Meetings on 17 November are framed around engagement, with detailed materials and a dedicated AGM website in place. That sets up a live forum for investors to test management on capital allocation into premium offices and the broader shift toward industrial and living assets.
For you, the AGM matters because it is the venue where management can clarify how these office buys sit alongside a forecast revenue decline, modest expected earnings growth, and reliance on external borrowing. Questions on funding mix, dividend reliability, future disposals and construction risk will be central to assessing whether current catalysts outweigh the well flagged project and cycle risks.
What The Mirvac Group Consensus Is Really Pricing In
Mirvac Group's consensus story asks you to accept a sharp reset in revenue alongside a big lift in profitability. Analysts are building their models on the view that reported revenue falls by 26.1% a year over the next three years while profit margins step up from 2.5% today to 59.5% around 2028. That combination creates a very different earnings mix to the Mirvac investors have been used to, with a heavier skew toward higher margin activities if the forecasts are met.
On those numbers, earnings are expected to move from A$68.0 million today to A$640.2 million by around 2028, which is roughly 9x higher in absolute terms. Mirvac Group would still, on this view, be booking materially lower revenue but converting a much larger slice of every dollar into profit. For you, that kind of shift puts even more focus on how reliably the group can deliver its development pipeline and how disciplined it is in using external capital, because those are the levers that tend to drive margin volatility for a property platform of this size.
Valuation assumptions line up with this earnings reset. To agree with the analyst consensus, you would need to accept that by 2028 Mirvac is generating about A$1.1b of revenue and A$640.2 million of earnings, and that the stock trades on a P/E of 18.2x rather than the current 132.3x. That implies the market pays much less for each dollar of profit than it does today, even as those profits are projected to be materially larger. Analysts frame this as leaving Mirvac roughly fairly priced around a consensus target of A$2.41 compared with a current share price of A$2.28, which gives you only a modest pricing gap to weigh against execution, funding and development risks.
Mirvac Group's narrative projects A$1.1b revenue and A$640.2 million earnings by 2028. This assumes revenue declines at 26.1% a year and earnings rise by about 9x from A$68.0 million today.
Uncover how Mirvac Group's fair value indicates a 36% potential upside to its current price that may not be available for long.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between A$2.35 and A$3.41, which leaves Mirvac Group looking cheap to some retail modellers and far richer to others. You are weighing those gaps against live risks around project impairments, residential demand and execution across a large development pipeline. Investor opinions can differ sharply, so use the AGM disclosures and these community views as starting points to test your own assumptions.
Explore 2 other Mirvac Group fair value estimates, including one that suggests as much as 87% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Instead, dig into the data and build a conviction that's truly your own.
- A great starting point for your Mirvac Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Mirvac Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Mirvac Group's overall financial health at a glance.
Looking for more Mirvac Group style investment ideas?
If Mirvac Group has you thinking about where capital structure, balance sheet strength and income potential line up, it can help to compare this story with other listed property and non property stocks on the Simply Wall St Screener.
- For investors who want potential upside but still care about financial resilience, start with a 4 high quality undervalued stocks that combine strong fundamentals with room for re rating.
- If capital preservation comes first for you, filter for businesses with lower risk scores and steadier profiles through our 6 resilient stocks with low risk scores that can help anchor a portfolio.
- When the focus is on quality over hype, scan a 15 high quality undiscovered gems that pair robust balance sheets with solid underlying metrics before they attract broad attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com