


Morgan Stanley stock took a 2.8% hit today, sliding to about US$181, even though the quarter delivered a powerful headline. Revenue landed near US$20.2b and earnings per share came in just above US$3, backed by a return on tangible common equity of 22.6% that kept the high teens Wall Street crowd on notice.
Short term traders saw a down day. Long horizon investors saw a global broker still printing mid 20s net profit margins and trading near a P/E in the mid teens.
Like the profitability at Morgan Stanley but want a broader set of highly efficient businesses on your radar that line up strong balance sheets with solid earnings power? Scan our hand picked list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs Q3 2025): US$20,190m vs. US$18,224m (up about 10.8%)
- Net Income ex. Extra Items (Q3 2026 vs Q3 2025): US$4,751m vs. US$4,450m (up about 6.8%)
- Basic EPS (Q3 2026 vs Q3 2025): US$3.02 vs. US$2.83 (up about 6.7%)
- Net Profit Margin, trailing 12 months (Q3 2026 vs prior year): 24.9% vs. 22.7% (margin higher year over year)
Prefer clean charts rather than a dense wall of earnings tables and footnotes? See Morgan Stanley's full financial picture, including how the valuation compares with recent results, in our company report for Morgan Stanley.
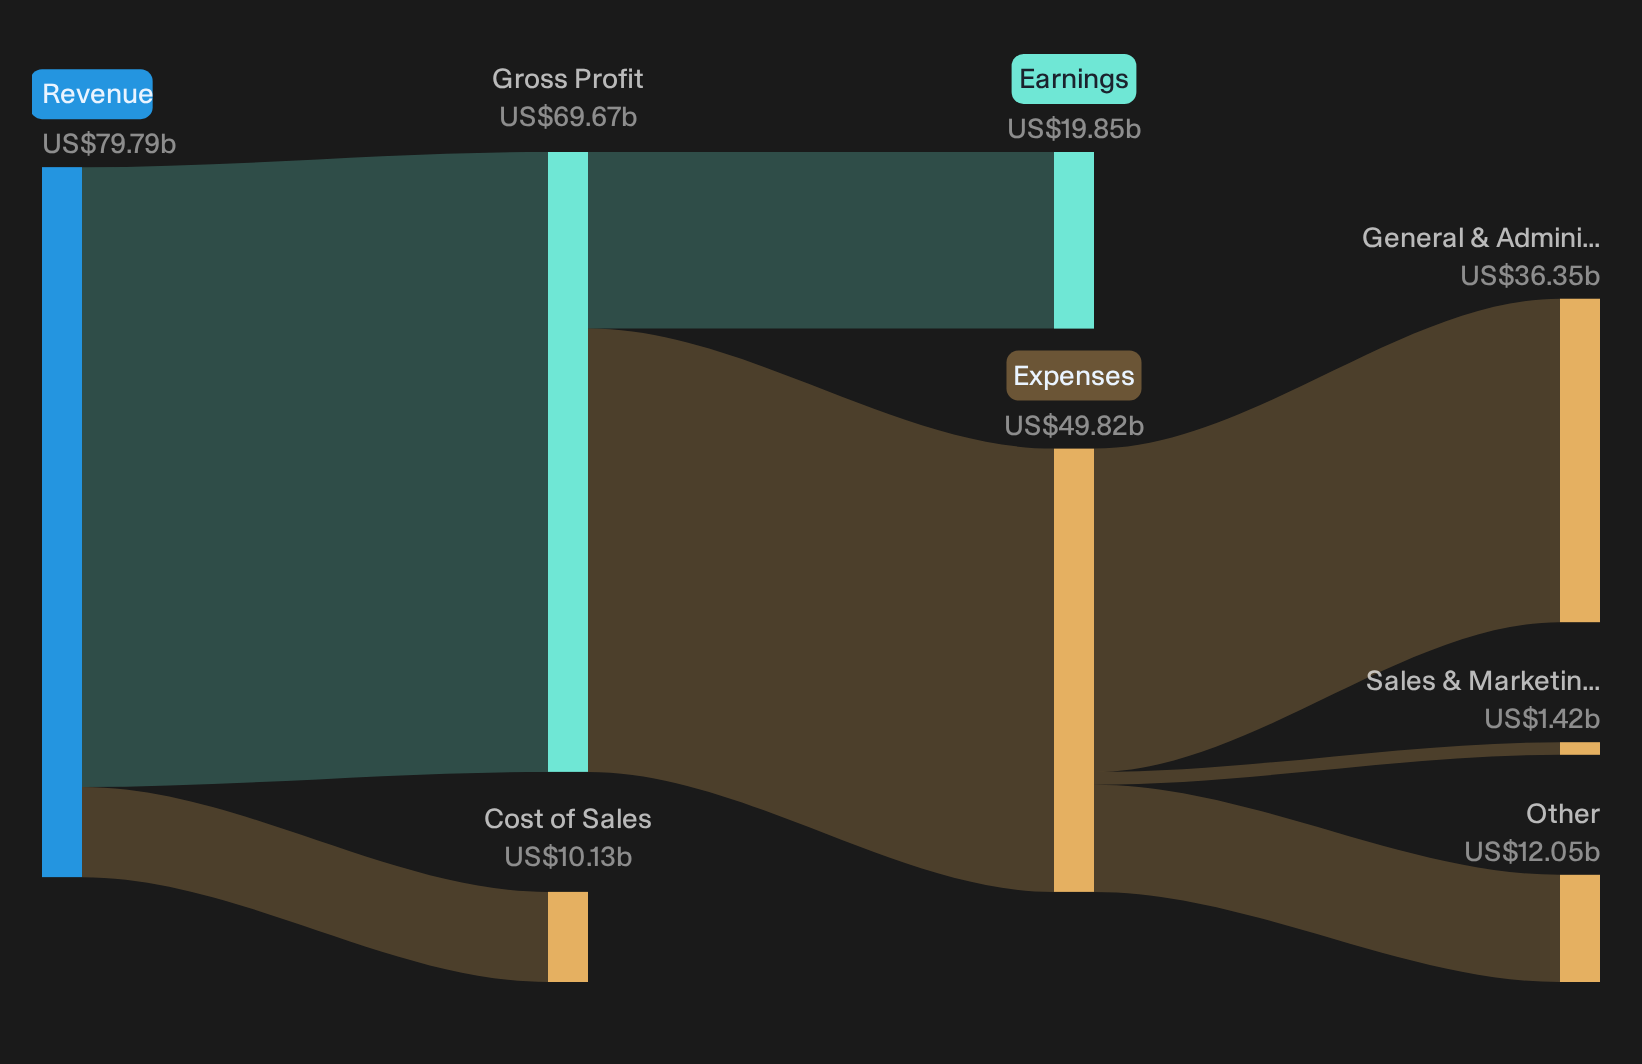
Morgan Stanley’s Platform Story Meets Hard Numbers
Bulls argue Morgan Stanley is turning its huge workplace funnel and wealth platform into steadier, higher quality fees. Q3 gives that claim some heft. Wealth Management posted US$9.1b of revenue and a 30.4% pretax margin, while net new assets of US$232b and US$80b of fee based flows show clients actually moving into managed solutions, not just parking cash.
The thesis that private markets and advisory can feed each other also finds support. Institutional Securities revenue reached US$10b with equities up strongly and advisory leading investment banking fees, helped by a healthy roster of AI, infrastructure and flagship IPO mandates flagged around the quarter. Asset Management adds a quieter proof point. Long term inflows of US$15.8b, with Parametric contributing, indicate custom indexing and related strategies are gaining traction. Together, these milestones show the platform engine working, even if the share price reaction today is cooler.
Compare Morgan Stanley’s hefty wealth and institutional flows with how the street is recalibrating its expectations after today’s 2.8% slide. See the consensus price target analysis for Morgan StanleyMorgan Stanley Bears Still Question Durability Of Flows
Bears argue Morgan Stanley leans on fee pools that are vulnerable to passive products, digital competitors and aging clients who add assets more slowly. This quarter does not fully close that argument. Wealth pretax margin at 30.4% looks healthy, yet the firm is still spending heavily on AI and technology, which keeps the path to structurally higher efficiency unproven. Net new assets of US$232b and US$80b of fee based flows are strong, although the recent North Haven Private Income Fund redemption pressure shows parts of the platform can face concentrated outflow stress.
Critics also worry that complex integrations and tighter rules could blunt operating leverage. Investment Management revenue of US$1.5b with carry reversals from two private holdings fits that caution. The stock’s decline of about 17% over 90 days suggests investors continue to price in execution and regulatory risk rather than treating this as a clean victory over the bearish narrative.
After a quarter where Morgan Stanley is juggling tech spend, complex products and regulatory pressure, you may want to review whether these issues are early warning signs or isolated bumps by reading our risk analysis for Morgan Stanley which shows 2 important warning signs.Stay Ahead Of Your Next Move
Morgan Stanley’s mix of strong profitability metrics and a share price that just fell 2.8% gives you a clear reason to register free with Simply Wall St and add it to your Watchlist so you can track price against fair value and wait for your preferred entry point. Once you own it or any other holding, use the Portfolio Command Center to cut through noise and focus on the key developments that actually matter to your long term thesis. To pressure test your thinking and spot blind spots early, tap into the Community and see how other investors are framing the same data. That way you can spot hidden catalysts and emerging risks sooner and give yourself a better chance of staying ahead of the market.
Seeking Alternatives Before Momentum Runs Away
Fresh ideas move first. Breakout stories are often caught early while they are still under the radar for now. Screens update quickly, information ages fast, act now.
- Spot strong balance sheets that might help companies navigate the next volatility spike by checking the curated list of solid balance sheet and fundamentals stocks (25 results) before prices start flying.
- Focus on structural themes instead of chasing yesterday’s winners by scanning the hand picked 43 power grid technology and infrastructure stocks while these ideas are still appearing in only a few portfolios.
- Look for potential compounders at the crossroads of automation and AI by reviewing the focused 90 robotics and automation stocks before broader market interest increases.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com