


- Diageo is reporting early progress in a turnaround under new CEO Sir Dave Lewis, with organic operating income and margins moving in the right direction. Brands like Smirnoff are pushing new pregame focused product drops and influencer partnerships to stay front of mind with consumers.
- The combination of cost discipline, portfolio mix work, and culturally tuned marketing signals that Diageo is trying to tighten execution across both the P&L and the front line, where its labels meet shifting drinking habits and moderation trends.
- We will look at how Diageo's investment narrative could be influenced by early turnaround traction and Smirnoff's pregame product push.
Diageo Investment Narrative Recap
To own Diageo, you need to be comfortable with a slow top line, a focus on premium spirits, and management leaning hard on margins and mix rather than chasing volume at any cost. The near term story rests on the early turnaround under Sir Dave Lewis translating into cleaner earnings after recent one off items and restoring confidence in profitability.
The key near term catalyst is execution on cost savings and portfolio mix, while keeping core labels relevant as moderation trends build. The biggest risk remains softer volumes, especially if younger drinkers pull back further or trade down. In that scenario, today’s marketing wins would not materially shift the volume picture.
The Smirnoff pregame product drops sit right in the middle of that operational tension. Diageo is using a mass brand to test new formats and occasion-led marketing at a football-focused moment, backed by an influencer partnership, while broader consumption patterns continue to evolve.
For readers, a useful question is whether this type of campaign can help Diageo stabilise or reallocate volumes into higher value occasions in ready to drink and flavored spirits. If execution is patchy or consumer interest fades quickly, it would highlight how much work remains to offset moderation risk and limited traction so far in alternative beverages.
What The Analyst Case Implies For Diageo
Diageo's analyst playbook is built on relatively flat projected sales over the next few years, paired with a sharp improvement in profitability. Forecasts point to profit margins moving from 8.8% today to 21.2% in roughly three years, which is a big shift in how much of each dollar of revenue would drop through to the bottom line.
On earnings, the consensus view centers on profit reaching about US$4.2b by 2029, compared with US$1.7b today, with the most optimistic forecasts closer to US$4.6b. That implies earnings would need to climb roughly US$2.5b from current levels, mostly through higher margins rather than stronger top line growth. Analysts are effectively assuming that Diageo can convert its cost work, portfolio clean up, and more focused marketing, including campaigns like Smirnoff's pregame push, into a much richer profit pool without relying on rapid revenue expansion.
Diageo's narrative projects US$19.9b revenue and US$4.2b earnings by 2029. This requires broadly flat yearly revenue movement and about US$2.5b earnings increase from US$1.7b today.
Valuation assumptions then hinge on what investors are willing to pay for those forecast profits. The analyst case uses a forward P/E of 17.7x on the US$4.2b earnings estimate in 2029, compared with about 27.8x today and an industry P/E reference of 23.7x for US beverages. In plain terms, the story only lines up if Diageo grows earnings meaningfully while the multiple investors are prepared to pay on each dollar of profit steps down over time.
Layered over this is a very modest expected increase in share count, with forecasts calling for outstanding shares to creep up by around 0.06% a year over the next three years. That is a tiny dilution assumption, yet it still matters because any extra shares slightly spread out the earnings pool that each shareholder effectively owns.
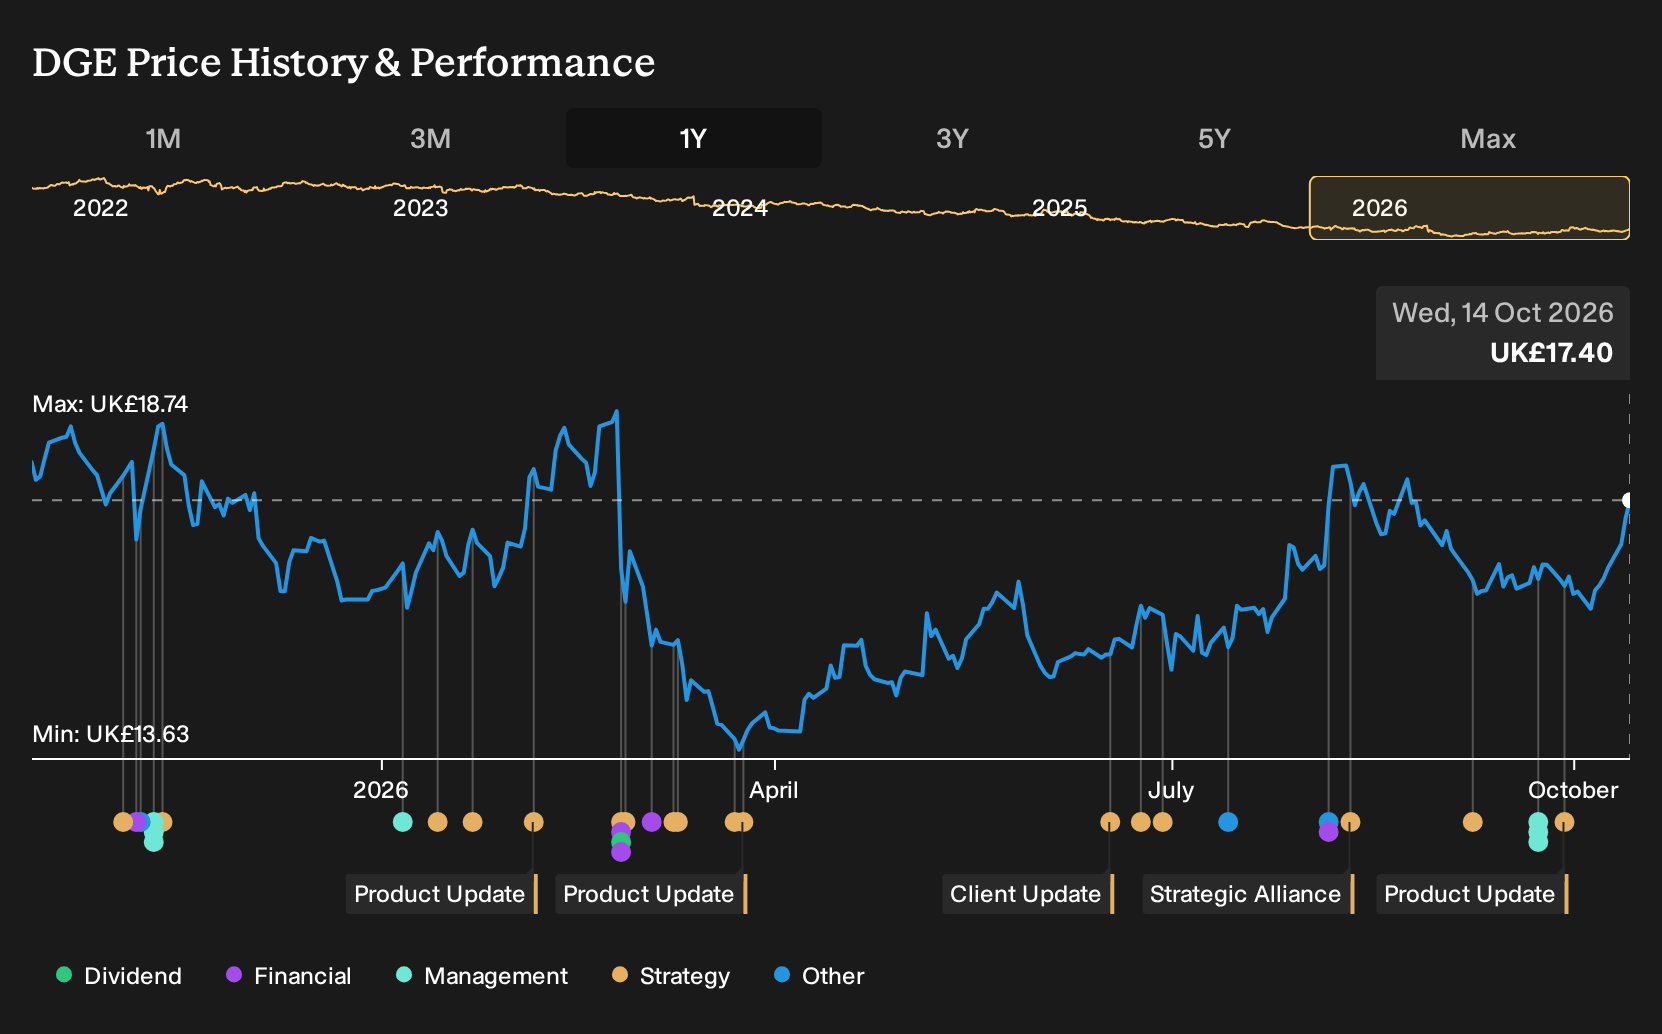
The consensus price target of £20.07, against a recent share price of £16.23, reflects those revenue and earnings expectations plus a discount rate of roughly 7.6% to bring future cash flows back to today. A spread between bullish and bearish targets, from £15.31 to £25.11, signals that analysts do not agree on how securely Diageo can deliver that margin step up while facing moderation trends, regulatory pressures, and competition in low and no alcohol formats.
Discover how Diageo's fair value indicates a 15% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts frame Diageo’s cost restructuring as the real swing factor, not just moderation risk. They were already modeling revenue of about US$21.3b and earnings of roughly US$4.7b by 2029, versus the US$19.9b and US$4.2b consensus. Smirnoff’s pregame push could nudge those views, so treat this as a moment to compare several narratives rather than adopt one by default.
Explore 5 other Diageo fair value estimates, including one that suggests as much as 84% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Diageo research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Diageo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Diageo's overall financial health at a glance.
Looking For More Investment Ideas Beyond Diageo?
Once you have a view on Diageo, it often helps to cross check that thesis against other opportunities that match your risk tolerance, income needs, or preference for balance sheet strength. The Simply Wall St Screener can surface a range of stocks that fit different priorities, so you are not relying on a single story to carry your entire portfolio.
- If capital preservation matters most to you when markets turn risk averse, consider scanning a basket of 4 resilient stocks with low risk scores that aim to keep volatility and financial stress in check.
- If you want potential mispricing plus quality, look across a focused group of 8 high quality undervalued stocks where cash flows and balance sheets do more of the heavy lifting than sentiment alone.
- If your goal is to find less crowded ideas with solid fundamentals, filter for a set of 5 high quality undiscovered gems that may not yet be widely followed by the broader market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com