


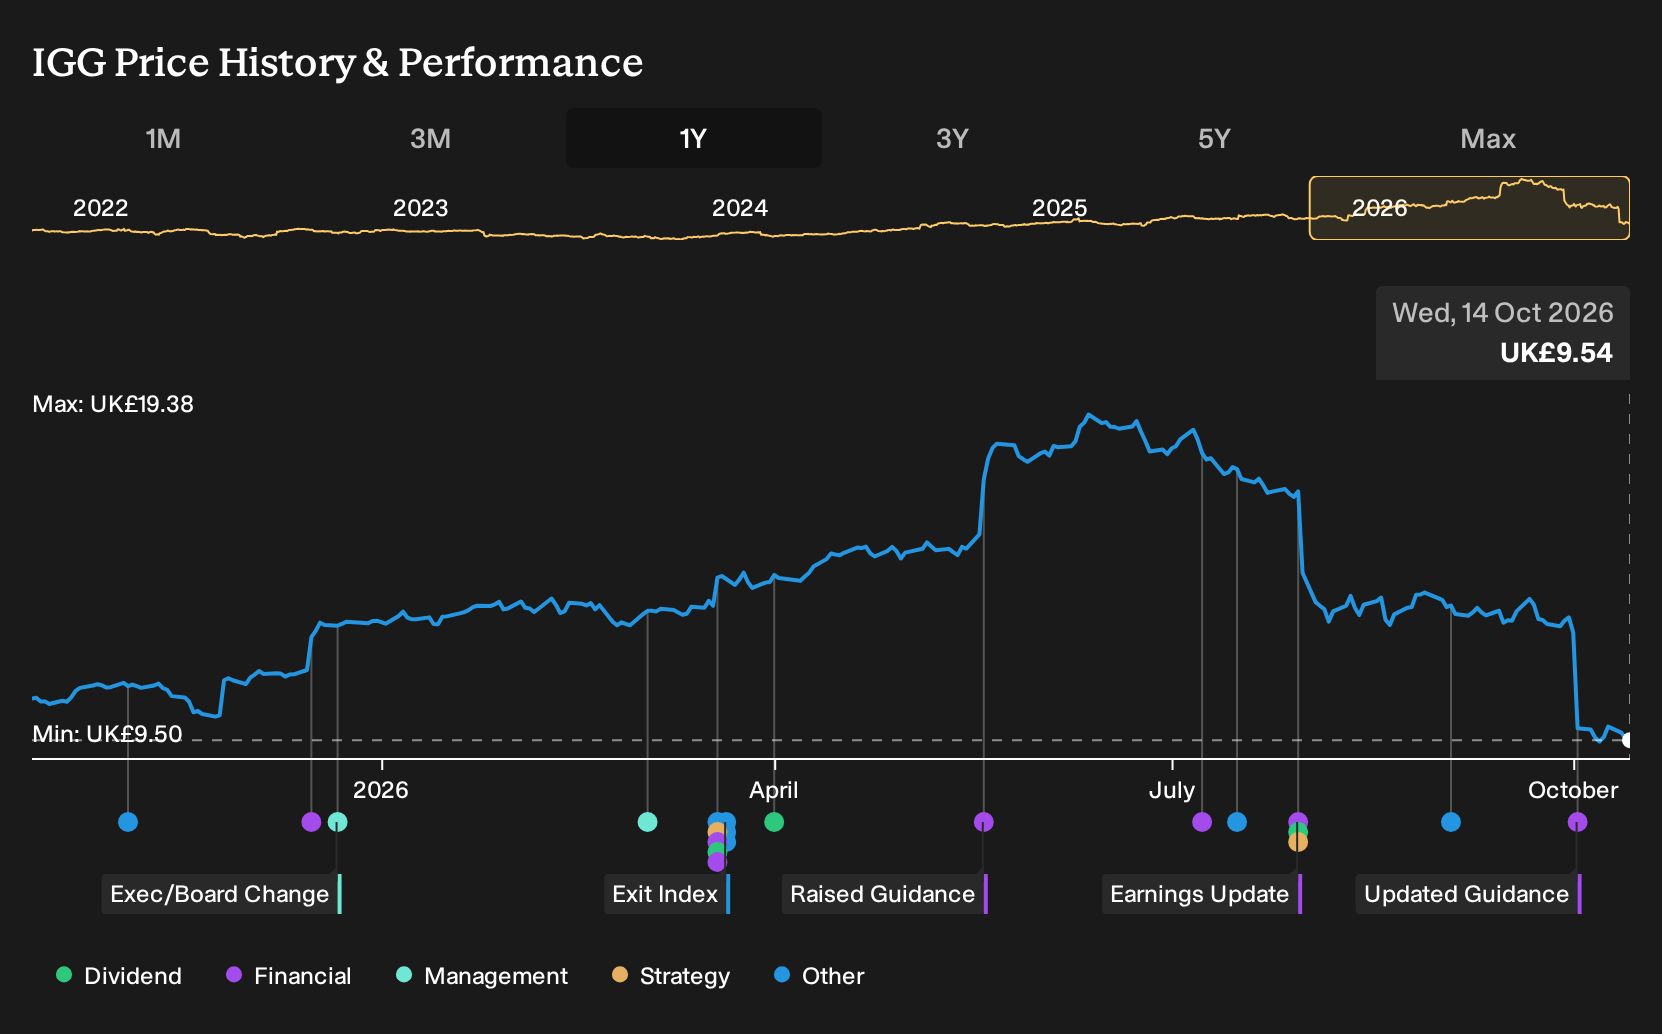
- IG Group Holdings updated guidance for the quarter to 30 September 2026, flagging around £240 million in revenue, which would be roughly 14% lower year-on-year, mainly due to weaker OTC revenue retention, while still guiding to mid single digit percentage revenue growth for the full 2026 fiscal year.
- The mix of a softer third quarter alongside an unchanged full year growth outlook suggests IG Group Holdings expects underlying client activity and other revenue drivers to offset weaker OTC retention over the rest of the fiscal year.
- We will now look at how IG Group Holdings' investment narrative meshes with guidance for a 14% year-on-year third quarter revenue decline.
Scan how traders are pricing revenue resilience by comparing the outlook for IG Group Holdings with our curated list of 8 high quality undervalued stocks.
IG Group Holdings Investment Narrative Recap
To own IG Group Holdings, you need to be comfortable with a trading led business that leans on client activity and volatility, while investing heavily in platforms and product breadth. The key short term swing factor is whether client engagement and non OTC income can offset weaker OTC retention. Management keeping full year mid single digit revenue growth guidance suggests this update is not a thesis breaker on its own.
The more pressing risk is that softer revenue retention overlaps with ongoing regulatory scrutiny of complex products and rising competition from low cost fintech brokers. If those pressures coincide with quieter markets or execution missteps on technology and automation, earnings could become choppier and margin progress harder to sustain.
This latest guidance cut on third quarter revenue links directly to the broader narrative around IG Group Holdings and its growth profile. Management now expects about £240 million of revenue for the quarter, around 14% lower year on year, while still talking to mid single digit growth for the full 2026 year. That combination forces you to focus on how resilient the broader business mix really is when one income line softens.
The guidance update puts execution on product mix, platform quality and international expansion under the microscope because these are the areas that may need to carry more weight if OTC retention remains under pressure. For you as a shareholder, the practical question is whether the existing strengths, such as high return on equity and a history of profit growth, are enough to offset the near term drag that this revenue reset points to.
IG Group Holdings is tied to analyst projections that point to about £1.6b of revenue and £558.3 million of earnings by 2029, based on an assumed 10.6% yearly increase in sales and an earnings uplift of roughly £64.7 million from the current £493.6 million level.
Uncover why IG Group Holdings' fair value indicates a 64% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on IG Group Holdings focuses on marketing spend. The most pessimistic analysts already expected heavier marketing, with revenue projected at about £1.3b and earnings of £480.9 million by 2029, even before this guidance cut. That group paints a tougher story, so treat today’s update as a prompt to compare several viewpoints.
Explore 5 other IG Group Holdings fair value estimates, including one that suggests it could be worth just £15.27!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your IG Group Holdings research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for IG Group Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IG Group Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond IG Group Holdings?
If this IG Group Holdings update has sharpened your thinking, use that momentum to widen your watchlist with stocks that fit different risk and income profiles through the Simply Wall St Screener.
- If you want potential upside without stretching on quality, start with a shortlist of 8 high quality undervalued stocks that blend stronger fundamentals with more modest pricing.
- For investors who care most about capital resilience, filter for steadier businesses using a 4 resilient stocks with low risk scores so you can compare ideas that might better match your risk tolerance.
- If balance sheet strength is non negotiable for you, narrow your search to our list of solid balance sheet and fundamentals (9 results) and focus your time on companies with sturdier financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com