


- RS Group has rolled out its RS PRO Total Panel Integration portfolio, a broad suite of networking, switching, signaling and thermal management products designed to simplify industrial control panel design, protect electronics and support smart factory uptime across a wide range of sectors.
- The scale of the offering, with thousands of RS PRO branded cables, switches, indicators and cooling components under one ecosystem, points to a push for deeper customer standardisation on RS Group’s higher margin private label in core factory automation workflows.
- We will now look at how RS Group's investment narrative is affected by this expanded RS PRO smart factory panel ecosystem.
Scan how RS Group's smart factory push compares with peers by reviewing our hand picked 90 robotics and automation stocks that are also wiring up industrial automation and control infrastructure.
RS Group Investment Narrative Recap
To own RS Group, you need to buy into a fairly simple idea. The distributor is trying to shift more volume into higher margin RS PRO products and wrap that around better digital tools and services. The new RS PRO Total Panel Integration portfolio fits that story, but on its own it does not change the near term focus on execution in weaker regions and categories.
The key short term swing factor is whether recent operational spending in technology, logistics and M&A integration translates into firmer margins without relying on strong end market demand. The largest risk still sits in underperforming areas like Mexico and semiconductors, where prolonged softness or delayed projects could weigh on both revenue progress and group profitability.
Within that context, the RS PRO Total Panel Integration launch is probably the most relevant operational update. It expands the existing private label range, which already contributes more than £400m of revenue and over 14% of group sales, into a more complete control panel and smart factory offer that can be sold through existing channels and to current industrial customers.
For catalysts, this broadened RS PRO ecosystem ties directly into the push for higher margin private label mix, deeper account penetration and better use of digital platforms. Execution risk sits around how quickly engineers and plant operators standardise on RS PRO instead of third party brands and whether RS Group can maintain service quality while integrating acquisitions like Distrelec and BPX and supporting regions where demand has been weaker.
RS Group's current analyst narrative points to revenues of £3.3b and earnings of £234.3m by 2029, based on revenue growth of 4.6% per year and an earnings increase of about £72m from £162.0m today.
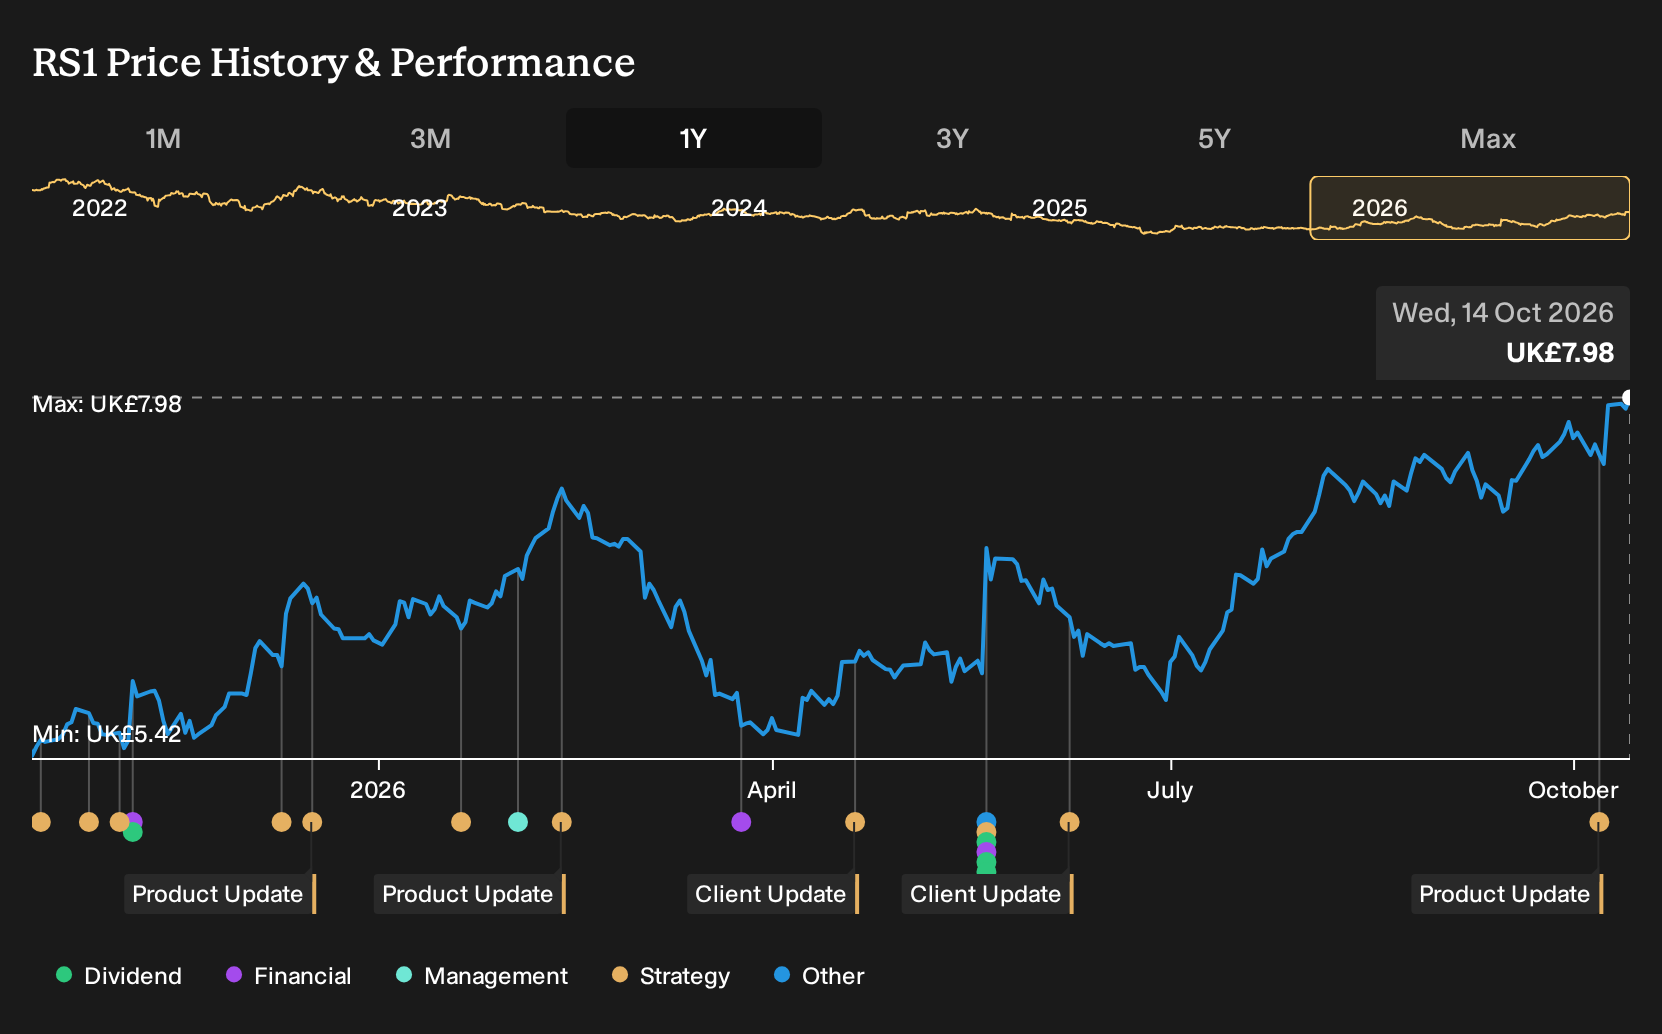
Discover why RS Group's fair value indicates a 7% potential downside to its current price, suggesting that the current premium may not be sustainable.
Exploring Other Perspectives
Some of the most optimistic analysts frame RS Group’s RS PRO push as proof that services and own label could matter far more. Before this news, the bullish camp was already working off revenue of £3.5b and earnings of £298.1m by 2029. You can test whether this more upbeat story still fits after the Total Panel Integration launch.
Explore 3 other RS Group fair value estimates, including one that suggests it could be worth as much as £7.99.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your RS Group research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for RS Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RS Group's overall financial health at a glance.
Looking For More Ideas Beyond RS Group?
If this RS Group story has sharpened your thinking, you can use that momentum to scan a wider field of listed businesses that might better match your risk tolerance, income goals or value focus.
- If you want potential value coupled with quality fundamentals, start by reviewing 8 high quality undervalued stocks that meet those criteria.
- For investors who care most about resilience and capital preservation, consider the 4 resilient stocks with low risk scores that screen well on stability metrics.
- When you are hunting for under-the-radar opportunities with solid numbers behind them, take a look at the 5 high quality undiscovered gems that might not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com