


The Zhitong Finance App learned that the US semiconductor sector is undergoing a profound market revaluation. As the September inflation data surpassed expectations and further strengthened expectations of the Federal Reserve's interest rate hike, compounding the rare warnings recently issued by the CEOs of Broadcom (AVGO.US) and Intel (INTC.US) about AI infrastructure financing bottlenecks, global AI-themed deals centered on semiconductors have been sold off on a large scale in the past week.
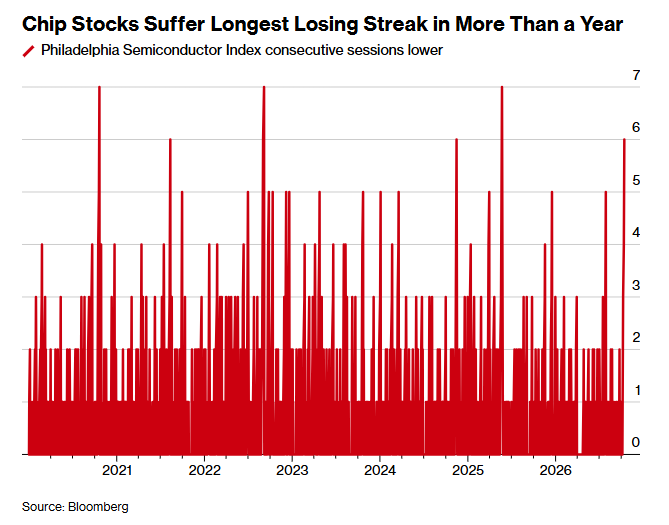
The Philadelphia Semiconductor Index (SOX) has accumulated a cumulative decline of about 12% over the past six trading days, and the market value evaporated by about 1.6 trillion US dollars, setting the record for the longest continuous decline since May 2025; the index plummeted 4.30% in a single day on Wednesday. This decline not only affected the US market, but also quickly spread to global semiconductor towns such as South Korea and Japan, triggering widespread discussions among investors about the sustainability of the AI investment cycle.
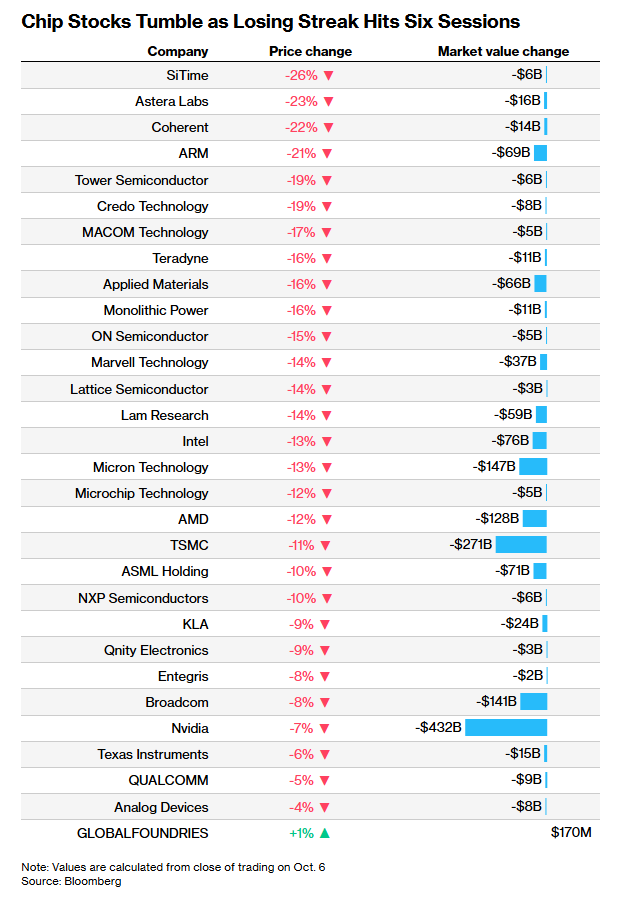
Among them, more than half of the constituent stocks in the index fell by at least 10% during this period. Arm Holdings Plc (ARM.US) plummeted 21%, Applied Materials (AMAT.US) fell 16%, and Intel (INTC.US) fell 13%. GFS.US (GFS.US) was the only stock that rose, outperforming its peers during this period.
The decline in the semiconductor sector echoed general market weakness — the tech-focused Nasdaq 100 index fell more than 2%, the worst single-day performance since the end of July, and the S&P 500 index fell 1.1%.
This round of sell-off was not limited to the US market. Global semiconductor stocks experienced simultaneous sell-off. Early trading in the Asian market on Thursday, the Korea Composite Stock Price Index (KOSPI) plummeted by more than 5% at the opening, continuing to hit a new low since the July low, and the Nikkei 225 Index plummeted more than 3%. The linked decline in global semiconductor stocks reflects deepening investors' systemic concerns about this sector.
“In recent days, the pressure on global chip stocks has continued to increase,” Ulrike Hoffmann-Burchardi of UBS's Chief Investment Office wrote in a research report on Wednesday. “Although increased competition in the AI sector, rising demand for financing, and higher interest rates may periodically increase volatility, we think this latest round of sell-offs is more like a recalibration of expectations than a fundamental break in AI investment logic.”
Inflationary pressure is heating up across the board, and the core CPI rebounded beyond expectations
The latest round of pressure came after September's inflation data was higher than expected, which further strengthened market expectations that the Federal Reserve would continue to raise interest rates, even if policymakers may stay on hold at the next meeting later this month.
According to data released by the US Department of Labor on October 14, the consumer price index (CPI) rose 0.6% month-on-month in September, the biggest increase since April this year; the year-on-year increase rose to 3.7%, up from 3.4% in August, and also exceeded economists' expectations of 3.6%. Excluding volatile food and energy prices, core CPI rose 0.3% month-on-month, the same as in August, but higher than market expectations of 0.2%; the year-on-year increase rose to 2.6% from 2.4% in August, exceeding expectations of 2.5%.
Specifically, energy prices are the main force driving up overall inflation. The energy price index rose 5.2% month-on-month in September. Among them, the gasoline price index rose 9.1% month-on-month, contributing more than half of the CPI increase in that month. The war in the Middle East continued to drive up fuel costs. Energy prices rose 20.4% in September this year, and the rise in fuel costs further boosted air ticket prices. In September, ticket prices rose 1.2% month-on-month, with a cumulative increase of 22.4% during the year.
It is worth noting that the price increase has gone beyond the energy sector and is spreading more widely. Analysts pointed out that prices for entertainment, used cars and trucks, education, air tickets, health care, and clothing have all risen. Some of these increases are due to tariffs and energy factors, but others indicate that inflation is more sticky.
Oulu Sonora, head of US economic research at Fitch Ratings, said that the latest inflation data “gave a red light” to the Federal Reserve, and that the spread of price increases to the wider service sector may increase the risk that inflation will continue to rise.
The deeper problem is that AI infrastructure construction itself is becoming a driver of inflation. The boom in data center construction is driving up the prices of commodities such as semiconductors, and is being transmitted to a wider range of economic sectors through channels such as labor costs in the construction industry.
Chicago Federal Reserve Chairman Goulsby clearly stated that inflationary pressure caused by the AI boom is going beyond directly related industries. “The field of price increases is no longer limited to data center components and directly related industries. I am increasingly concerned that this is typical aggregate demand overheating”.
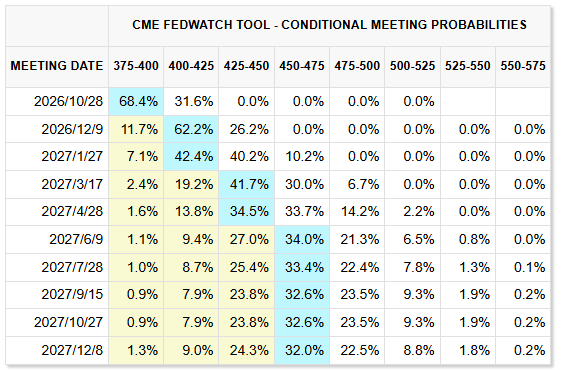
The higher-than-expected inflation data quickly reshaped the market's expectations of the Federal Reserve's interest rate path. According to the CME “Federal Reserve Watch” tool, after the CPI data was released, the probability of traders betting on the Federal Reserve's interest rate hike of 25 basis points in October once rose from about 18% before the data was released to 50%. The probability of interest rate hikes in December rose to close to 90%. Although market expectations have cooled down as of press time, the probability of interest rate hikes in December is still over 60%.
The Fed's decision makers intensively released hawkish signals before and after the inflation data was released. New York Federal Reserve Chairman Williams made it clear that he still believes it is appropriate to raise interest rates again this year, but he does not think it is necessary for the central bank to raise interest rates further in 2027. Williams revealed that the Iran conflict pushed up energy prices and widened the price spread of refined oil products, changed his judgment on short-term inflation prospects, and made him “firmly support” the September interest rate hike decision. Boston Federal Reserve Chairman Collins also said that she expects “moderate further interest rate hikes” before the end of the year to ensure that inflation returns to the Fed's 2% target in a timely manner.
The Cleveland Federal Reserve President also expressed a similar position, believing that monetary policy may need to be further tightened. Citigroup adjusted its forecast after the CPI data was released. The Federal Reserve is expected to raise interest rates by 25 basis points in December 2026. Previously, the bank predicted that the Federal Reserve would keep interest rates unchanged during this year.
In an exclusive interview, Williams specifically pointed out that the AI infrastructure frenzy, along with tariffs and energy prices, has become the three core variables currently affecting the US inflation path. He observed an upward trend in products and costs associated with AI construction: “We are indeed seeing an increase in products and other costs associated with AI construction: data centers, huge demand for chips. Prices in the AI-driven sub-sector have risen quite abruptly and drastically, and we are also seeing some signs of spillover into construction labor costs”.
But at the same time, he gave a relatively optimistic long-term judgment — as chip production capacity increases and productivity increases, the supply side may improve in the future and form a force to curb inflation.
Broadcom CEO's warning sparks a ripple effect: capital constraints on AI investment have surfaced
In addition to macro-level interest rate pressure, industry-level financing restraint warnings have become another important catalyst for this round of sell-offs. Earlier this week, Broadcom CEO Chen Fuyang compared some investors chasing the AI craze to “gamblers,” saying bluntly that many AI investors don't understand the technology they invest in at all, yet they have high expectations. He further warned that capital — not chip supply — will be the biggest constraint on the development of artificial intelligence.
Chen Fuyang also questioned the actual benefits of enterprises investing in AI, pointing out that AI model developers must find customers who can generate return on investment by introducing AI technology, rather than relying on users who are still in the trial stage and are constantly “wasting money” on tokens. He explained the problem with a vivid analogy: “It's like when you went to a video playground to play games when you were a kid, your parents gave you $10 worth of tokens, and you spent them all in 10 minutes, but you didn't learn anything. This is exactly what is happening in the corporate world today”.
Chen Fuyang also questioned the actual benefits of enterprises investing in AI, pointing out that AI model developers must find customers who can generate return on investment by introducing AI technology, rather than relying on users who are still in the trial stage and are constantly “wasting money” on tokens. He explained the problem with a vivid analogy: “It's like when you went to a video playground to play games when you were a kid, your parents gave you $10 worth of tokens, and you spent them all in 10 minutes, but you didn't learn anything. This is exactly what is happening in the corporate world today”.
This statement sparked widespread resonance and controversy in the market. Michael Berry, the prototype character of the movie “The Big Short” and a well-known investor, retweeted Chen Fuyang's conversation on social media platform X, highlighting in particular the problem that companies spend money to use AI tokens without necessarily creating actual value.
Broadcom's warning was confirmed by reality. AI cloud computing service provider Coreweave (CRWV.US)'s 2032 unsecured bond fell to less than 80% of face value on Wednesday, with a yield of more than 15%; its credit default swap rose to a record high, and market pricing indicates that the company's probability of default over the next five years is over 50%. CoreWeave shares closed down more than 15% on Wednesday.
Analyst D.A. Davidson previously referred to CoreWeave as a “subprime loan file” for the AI sector and warned that if the AI financing boom subsides, the company may not be able to repay the high debt.
Daniel O'Regan, executive director of Mizuho Securities's stock exchange department, pointed out that investors “have become increasingly unwilling to fund AI-related expenses at any cost” over the past few weeks. AI capital expenditure has surpassed the company's ability to generate free cash flow, meaning that companies must seek external financing to purchase the hardware they need. As external financing becomes more difficult, spending on chips and other AI infrastructure may be substantially affected.
J.P. Morgan's team of analysts led by Nikolaos Panigirtzoglou wrote in an October 14 report that although the current stock price trend is similar to the pullback at the end of July, the current background environment for AI infrastructure stocks is even more unfavorable.
Panigirtzoglou said that the reason is “although capital continues to flow into the overall stock fund, retail investors have so far lacked 'buying on diff' behavior, a cliff-style decline in repurchase capital outflows, insufficient bearish base, and higher asset management scale for leveraged stock ETFs.” “Despite the recent pullback, cyclical stocks do not appear to be oversold in terms of positions or capital flow.”
“We recommend investors focus on areas where AI spending is translating into sustainable profitable growth and wider corporate and consumer adoption,” said UBS's Hoffmann-Burchardi.