


- Unilever has expanded its use of artificial intelligence across operations and marketing, supported by a new five year partnership with Google Cloud and exploratory work with Microsoft, with early internal results including higher manufacturing capacity and faster content creation.
- The AI rollout signals a push to rewire Unilever’s cost base and product development cycle, as the group leans on data driven tools to sharpen execution, refine demand planning, and potentially support its focus on premium, science led personal care and beauty brands.
- We will look at how Unilever's push for an AI first technology foundation could reshape its existing investment narrative and risk balance.
Scan how Unilever’s AI push compares with other consumer-facing groups leaning into automation and data by reviewing our hand picked list of 92 AI infrastructure stocks.
Unilever Investment Narrative Recap
To own Unilever, you need to believe the company can keep turning a huge global footprint in everyday products into steady earnings, supported by its shift toward premium, science led beauty and personal care. The AI build out with Google Cloud and Microsoft points to an effort to get more out of that scale rather than change the core model.
The key near term swing factor is execution on portfolio simplification and cost savings while holding share against private label and local competitors. The AI push and Dermalogica leadership change appear incremental to this story. They matter for long run productivity and brand strength, but do not radically change the biggest current risk.
The Dermalogica CEO transition is the most relevant operational update around this theme. Aurelian Lis stepping down at the end of 2026, with Tim Bunch stepping in on an interim basis, matters because Dermalogica sits in Unilever’s Beauty & Wellbeing arm, where management is aiming for higher margin, science led growth.
For you as an investor, the question is whether that premium skin care unit can keep its momentum through a leadership change, while Unilever uses AI and data tools to improve marketing and demand planning. Any stumble in Dermalogica during the search for a permanent CEO would feed directly into the premium portfolio catalyst that many shareholders are watching closely.
Unilever's narrative projects €57.0b revenue and €7.7b earnings by 2029. This assumes 4.1% yearly revenue growth and an earnings increase of about €2.1b from €5.6b today.
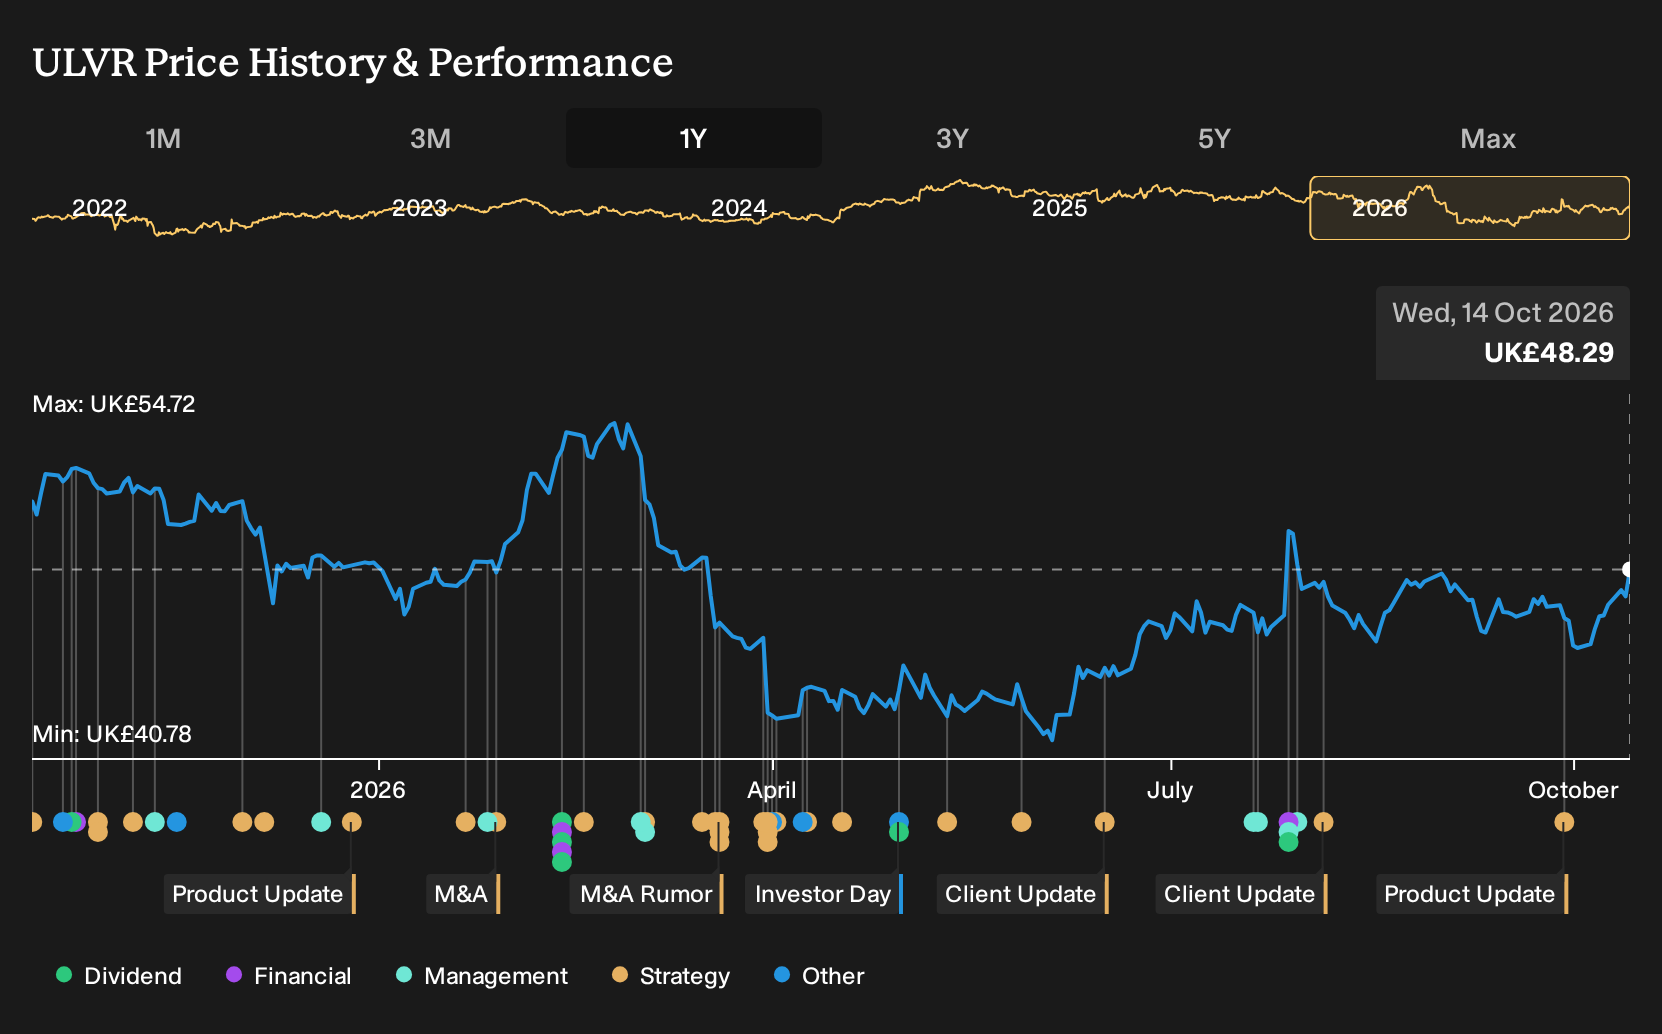
Uncover how Unilever's fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest Unilever analysts focus on McCormick deal execution risk rather than AI. They were pencilling in about €55.6b of revenue and €7.6b of earnings by 2029, along with a much lower implied P/E of 16.4x. You can consider the new AI push and the Dermalogica leadership change as potential reasons those cautious forecasts might shift, then compare several viewpoints before deciding what feels reasonable for you.
Explore 7 other Unilever fair value estimates, including one that suggests as much as 17% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Unilever research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Unilever. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Unilever's overall financial health at a glance.
Looking For More Investment Ideas Beyond Unilever?
If the Unilever story has you thinking about portfolio gaps, it can help to line it up against other companies with very different risk and reward profiles. The Simply Wall St Screener lets you scan broader markets quickly so you can test your thesis instead of relying on a single stock.
- If you prefer a focus on balance sheet strength and fundamentals over headline stories, then filter for a list of solid balance sheet and fundamentals (9 results) that may better fit a cautious approach.
- If you are hunting for mispriced quality where the market might be looking the other way, compare Unilever against a 5 high quality undiscovered gems that could offer a different kind of opportunity.
- If capital preservation matters most to you right now, narrow the field to a 4 resilient stocks with low risk scores and see how those profiles stack up against Unilever.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com