


Ventas guidance and acquisition plans draw investor focus
Ventas (VTR) drew fresh attention after management outlined guidance for 15% to 17% Net Operating Income growth and increased this year’s acquisition budget to US$3 billion, focused on senior housing and healthcare assets.
Recent trading reflects that guidance. Ventas shares are up 5.33% over the past week after a period in which the 30 day share price return declined 5.38% and the 90 day share price return fell 11.29%. The 3 year total shareholder return of 113.43% illustrates how strong long run compounding has been.
Capitalize on Ventas' momentum in senior housing by scanning a curated list of solid balance sheet and fundamentals (25 results) that also leans into aging demographics and healthcare demand.After a sharp weekly rebound but a wider gap to both analyst targets and intrinsic value estimates, the real tension around Ventas is simple: Are investors already paying close to fair value, or is there still clear upside left on the table?
Most Popular Narrative: 17% Undervalued
Ventas last closed at $84.31, while the most followed valuation narrative pegs fair value closer to $101.86. This estimate uses a 7.5% discount rate and a detailed earnings path out to 2029 to explain that gap.
Ventas is positioned to benefit from a rapidly growing aging population driving sustained demand for senior housing and healthcare facilities, combined with historically low new construction, supporting multi-year occupancy gains and net operating income growth as occupancy rates move toward the 90% level. This can add operating leverage and support higher margins and earnings.
See why 15 investors see Ventas as 17% undervalued.
Result: Fair Value of $101.86 (UNDERVALUED)
Still, the Ventas story can break if senior housing occupancy or pricing weakens, or if heavy equity issuance leaves future FFO per share underwhelming.
Find out about the key risks to this Ventas narrative.
Another View: Ventas on sales multiples
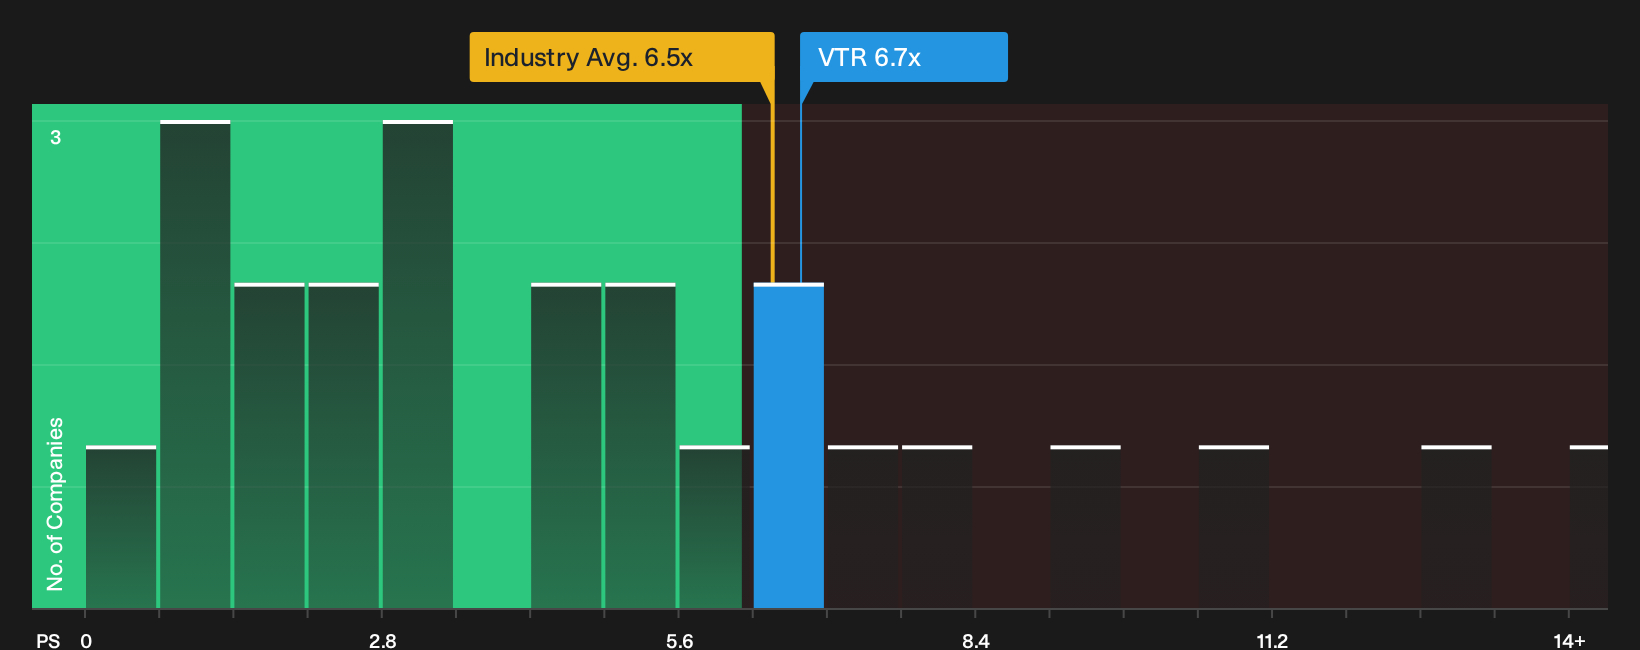
There is a different message when you look at Ventas through its P/S ratio. The stock trades at 6.7x sales, higher than the Global Health Care REITs average of 6.5x and above a fair ratio estimate of 5.6x. That gap points to some valuation risk if sentiment cools.
For investors weighing whether the current price lines up with fundamentals, it helps to see how the numbers stack up in more detail. This is where See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Ventas can be healthy for your process, since disagreement often highlights where the real questions lie. Move quickly to review the data and weigh the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Ventas?
Do not stop with Ventas. Fresh opportunities often show up where pricing, balance sheets, and cash flows line up in cleaner ways than headline stories suggest.
- Target resilient potential by hunting for companies with stronger financial footing using the 32 resilient stocks with low risk scores.
- Spot mispriced quality by scanning a focused list of 32 high quality undervalued stocks before others catch on.
- Build your income stream by zeroing in on reliable payers through a curated set of 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com