


CHAPTERS Group (XTRA:CHG) released updated figures in its half-year 2026 earnings report, posting €105.12 million in sales and a net loss of €21.16 million, which highlights the ongoing balance between growth and profitability.
At a share price of €44.0, CHAPTERS Group has delivered an 8.64% year to date share price return, while the 1 year total shareholder return of 17.65% and very large 5 year total shareholder return suggest momentum has built over a longer stretch, even as the latest results refocus attention on profitability risks.
Compare CHAPTERS Group's growth versus profitability trade off with a curated set of software-focused businesses in the 615 high quality undiscovered gems that pair strong fundamentals with expanding top lines.
CHAPTERS Group has built a broad, resilient looking software portfolio, and the share price has moved ahead of the latest loss making half year. The real issue now is whether you are paying too much for that strength.
Most Popular Narrative: 17% Undervalued
Against a last close of €44.0, the most followed narrative points to a fair value of €53 for CHAPTERS Group. This frames the current share price as materially discounted once long term cash flows are run through a 7.27% discount rate.
The main thing that has to go right is execution on AI-enabled transformation and larger, AI-ready acquisitions so that initiatives such as Lumera, Peak Mobility, Altamount and the Manuscript Method translate into sustained, higher quality earnings.
See why 2 investors see CHAPTERS Group as 17% undervalued.
Result: Fair Value of €53 (UNDERVALUED)
Still, the earnings loss and recent compliance problems around blocked accounts show how setbacks in integration or regulation could quickly challenge the CHAPTERS Group upside story.
Find out about the key risks to this CHAPTERS Group narrative.
Another View: CHAPTERS Group Looks Expensive On Sales
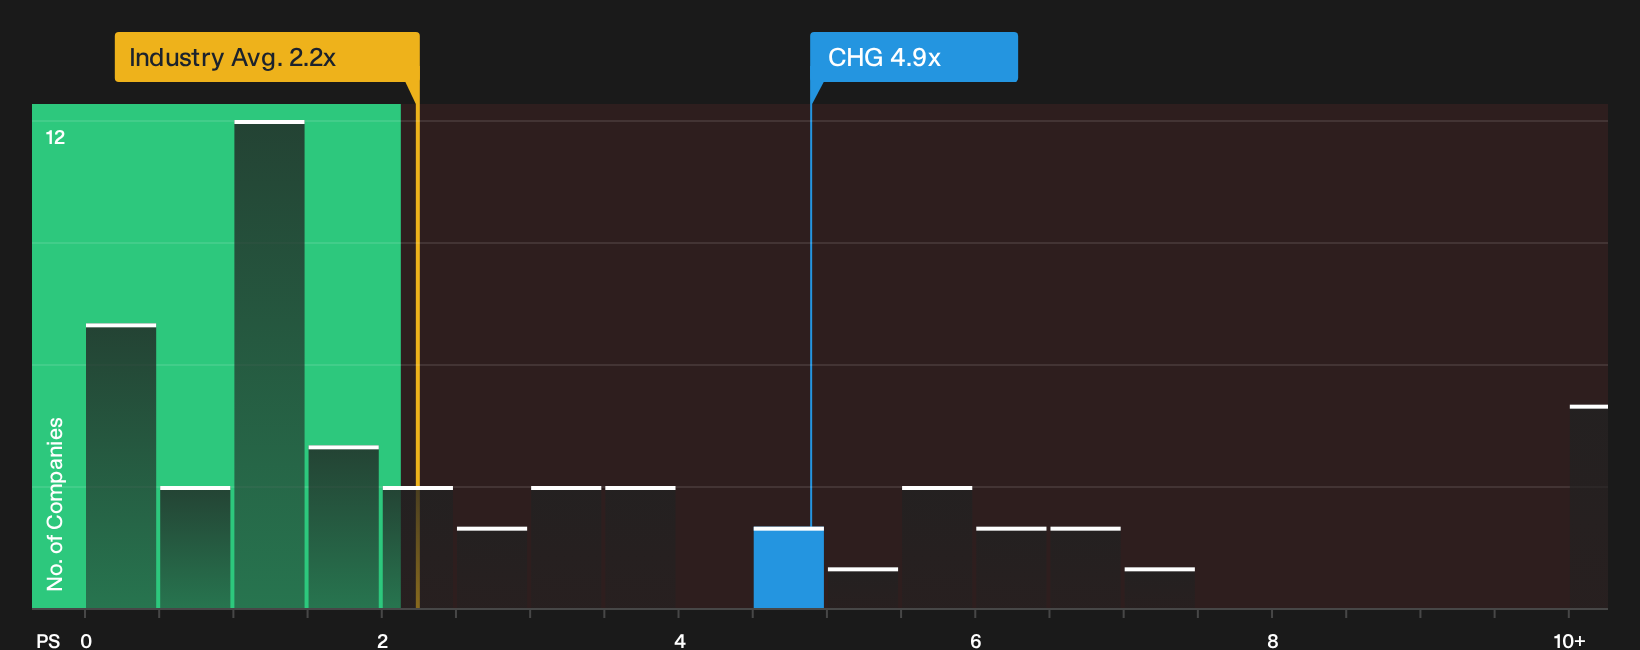
The SWS DCF model suggests CHAPTERS Group is undervalued, with an estimated future cash flow value of €85.59 versus a €44 share price. On a simple P/S lens, however, the picture is very different. The stock trades on 4.9x sales compared with 2.2x for the German software sector and a peer and fair ratio level of 3.3x.
That gap points to investors already paying a rich revenue multiple, which raises the question of how much mispricing is left if growth or margins fall short of the bullish case.
For a closer look at how this sales based view stacks up against earnings potential and peer pricing, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mix of enthusiasm and caution around CHAPTERS Group is hard to ignore, and that split sentiment is exactly where your own homework matters most. With at least one risk on investors’ minds and at least one reward drawing optimism, it is worth going through the full picture for yourself using the 2 key rewards and 1 important warning sign.
Looking for more CHAPTERS Group style investment ideas?
If CHAPTERS Group has you thinking about risk, reward, and price paid for quality, broaden your watchlist now using focused screeners that surface clear, data driven opportunities.
- Target potential mispricing by hunting for companies with strong fundamentals that still trade on modest valuations through the 188 high quality undervalued stocks.
- Prioritise capital preservation first by scanning for businesses with resilient metrics using the 224 resilient stocks with low risk scores.
- Strengthen the core of your portfolio by focusing on companies backed by robust finances through the list of solid balance sheet and fundamentals (203 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com