


Amidst global market volatility, driven by geopolitical tensions and fluctuating energy prices, Asia's stock markets have shown resilience with sectors like technology and consumer goods capturing investor interest. In this environment, companies with high insider ownership are often seen as promising investments due to the alignment of interests between management and shareholders.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Shanghai Skychem Technology (SHSE:688603) | 31.8% | 67.7% |
| SEERS (KOSDAQ:A458870) | 33.8% | 37.8% |
| Meitu (SEHK:1357) | 23.1% | 26.7% |
| Meiko Electronics (TSE:6787) | 19.2% | 34% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| JHT DesignLtd (SHSE:603061) | 23.1% | 48.6% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
We'll examine a selection from our screener results.
APT Medical (SHSE:688617)
Simply Wall St Growth Rating: ★★★★★☆
Overview: APT Medical Inc. focuses on the research, development, production, and sale of cardiovascular interventional medical devices in China with a market cap of CN¥35.62 billion.
Operations: The company generates revenue of CN¥2.90 billion from its medical products segment.
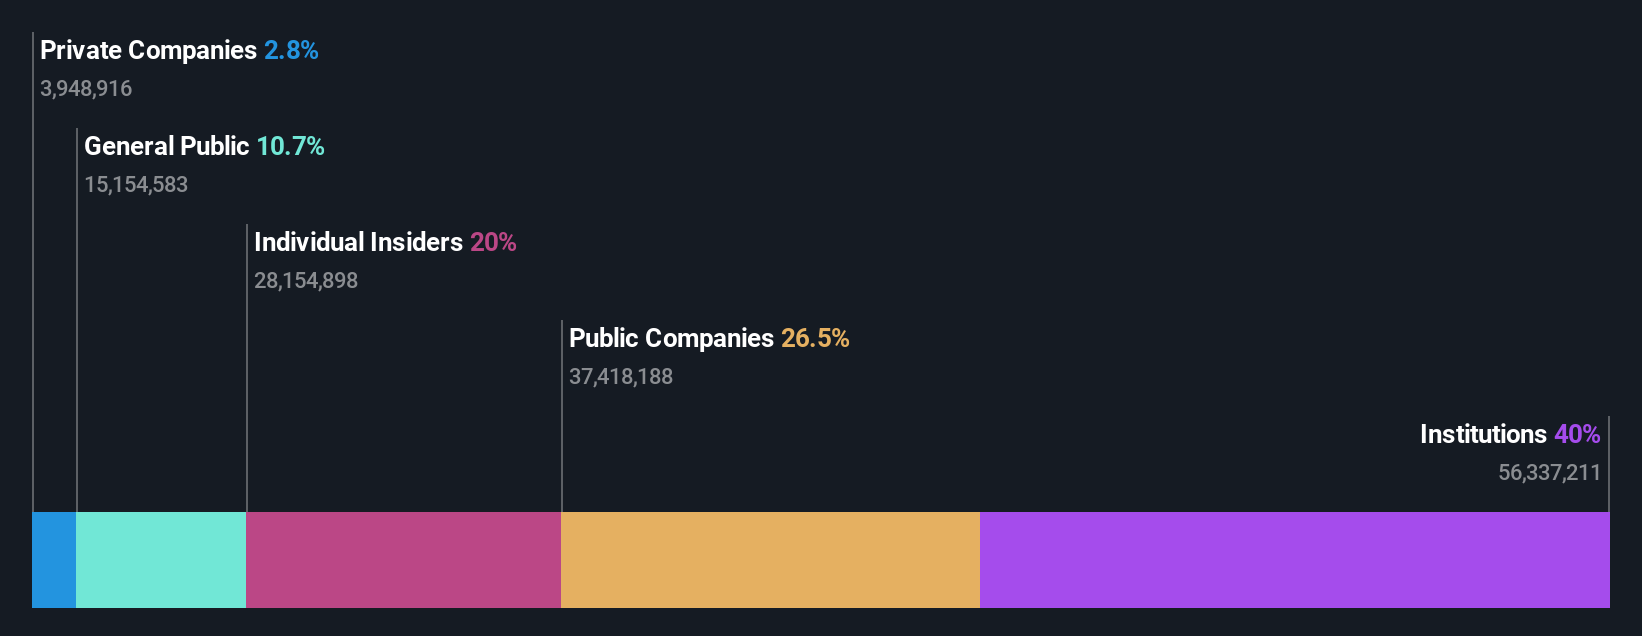
Insider Ownership: 20.3%
Earnings Growth Forecast: 21.8% p.a.
APT Medical demonstrates robust growth potential with high insider ownership, reflected in its strong financial performance. For H1 2026, net income rose to CNY 537.32 million from CNY 425.16 million year-on-year. The company's revenue is forecasted to grow at 21.9% annually, outpacing the broader Chinese market's growth rate of 16.7%. Despite trading at a significant discount to its estimated fair value, analysts anticipate a price increase of approximately 30%.
- Click here and access our complete growth analysis report to understand the dynamics of APT Medical.
- In light of our recent valuation report, it seems possible that APT Medical is trading behind its estimated value.
Shanjin International Gold (SZSE:000975)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Shanjin International Gold Co., Ltd. engages in the exploration, mining, and trading of precious and non-ferrous metal ores in China, with a market capitalization of approximately CN¥64.99 billion.
Operations: The company's revenue primarily comes from its Metal Commodities Trading segment, generating CN¥8.99 billion, and its Non-Ferrous Metal Mining and Processing segment, contributing CN¥8.52 billion.
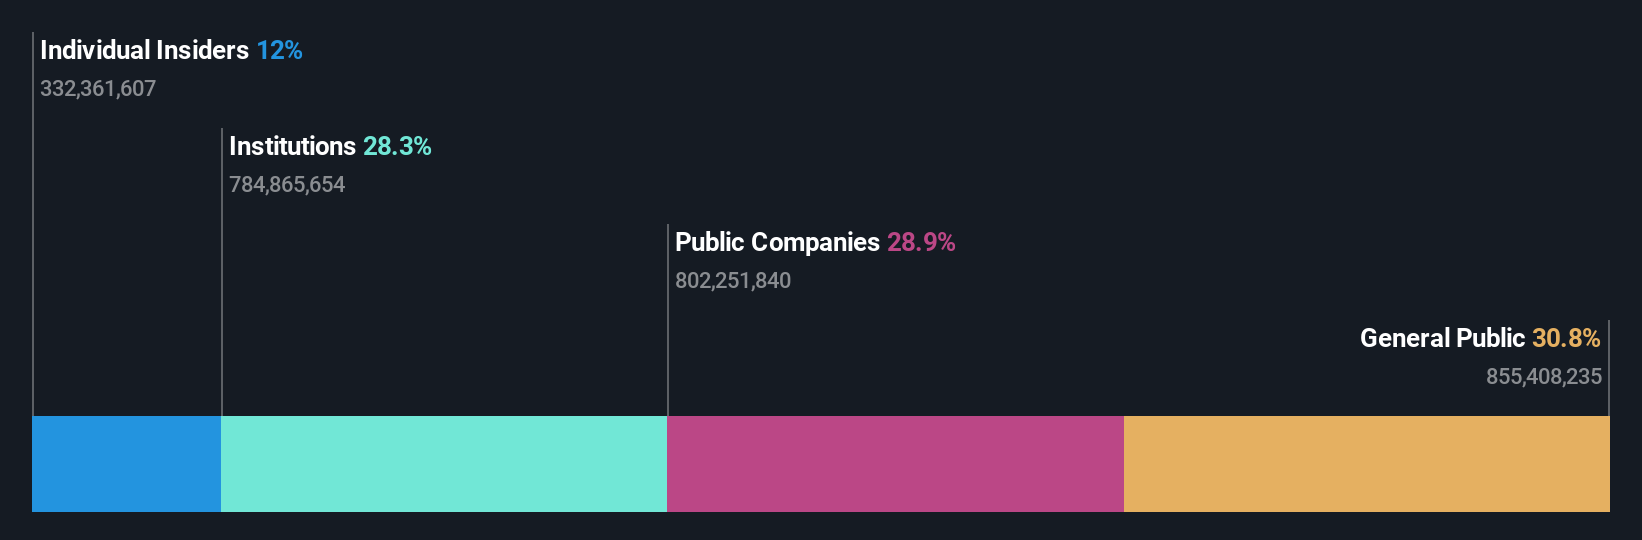
Insider Ownership: 12%
Earnings Growth Forecast: 31.3% p.a.
Shanjin International Gold's insider ownership aligns with its substantial growth prospects. Earnings are expected to grow significantly at 31.3% annually, outpacing the Chinese market's forecast of 26.8%. Revenue is projected to rise by 18.6% per year, slightly above the market average of 16.7%. Despite an unstable dividend history, Shanjin trades at a significant discount to its estimated fair value and reported strong H1 2026 financials with net income reaching CNY 2.42 billion from CNY 1.60 billion last year.
- Click to explore a detailed breakdown of our findings in Shanjin International Gold's earnings growth report.
- The analysis detailed in our Shanjin International Gold valuation report hints at an deflated share price compared to its estimated value.
Haian Rubber Group (SZSE:001233)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Haian Rubber Group Co., Ltd. focuses on the research, development, manufacture, sale, and management of mining tires both in China and internationally, with a market cap of CN¥8.39 billion.
Operations: The company's revenue is primarily derived from all steel giant tire sales amounting to CN¥1.53 billion and mining tire operation and management contributing CN¥664.01 million.
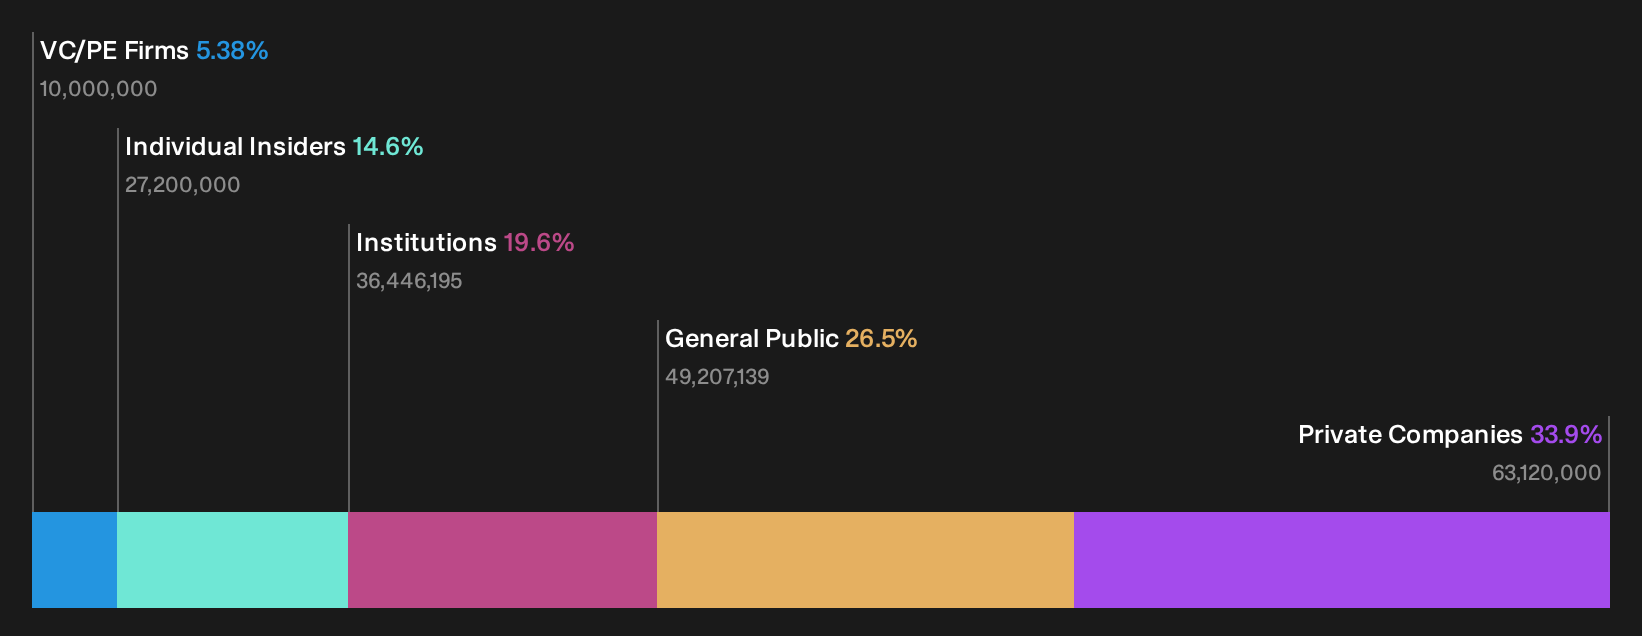
Insider Ownership: 14.6%
Earnings Growth Forecast: 33.3% p.a.
Haian Rubber Group's growth prospects are bolstered by high insider ownership, with earnings forecast to grow significantly at 33.3% annually, surpassing the Chinese market's 26.8%. Revenue is expected to increase by 23.1% per year, outpacing the market average of 16.7%. Despite a strong growth outlook and trading at a good value with a P/E ratio of 20.8x, recent financials showed declining net income from CNY 340.83 million to CNY 183.74 million year-over-year for H1 2026.
- Click here to discover the nuances of Haian Rubber Group with our detailed analytical future growth report.
- Our valuation report unveils the possibility Haian Rubber Group's shares may be trading at a discount.
Next Steps
- Get an in-depth perspective on all 496 Fast Growing Asian Companies With High Insider Ownership by using our screener here.
- Contemplating Other Strategies? The latest GPUs need a type of rare earth metal called Neodymium and there are only 32 companies in the world exploring or producing it. Find the list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com