


- EdgeConneX announced a 50-50 joint venture with Stockland to build, own, and operate hyperscale data center campuses in Australia, starting with Sydney and Melbourne and backed by 450MW of secured power and further power and planning applications in progress.
- The move pulls Stockland deeper into capital intensive digital infrastructure at the same time as community opposition builds around related AI and data projects, which could influence project timing, capital allocation, and future recurring income mix.
- We now examine how Stockland's entry into hyperscale data centers through the EdgeConneX joint venture could reshape its investment narrative.
Scan how other AI data and infrastructure plays stack up against Stockland by running the hand picked 92 AI infrastructure stocks.
Stockland Investment Narrative Recap
To own Stockland, you need to believe its mix of master planned communities, land lease projects, retail and logistics can convert population growth into steadier, higher margin income over time. The EdgeConneX data center JV fits that story by leaning into digital infrastructure, although it adds complexity on project delivery and capital needs in the near term.
The key short term swing factor remains how Stockland manages a shift toward lower margin Victorian residential settlements and the timing of larger logistics and data projects. Community opposition to AI linked developments adds execution risk. The biggest near term threat is that this more capital intensive phase pressures gearing, earnings stability and returns.
The fresh EdgeConneX partnership is the announcement that matters most here. It formalises Stockland’s push into hyperscale data centers in Sydney and Melbourne, with 450MW of power already secured. For you, that concentrates the story on whether management can convert land, planning approvals and global operator expertise into recurring income without stretching the balance sheet.
This JV also interacts directly with existing catalysts in logistics and capital partnerships. A larger pipeline, co funded with partners, can widen fee income and support long dated rental streams, while also muting Stockland’s direct revenue share and lifting reliance on joint ventures. Execution on these first campuses, especially against local community scrutiny, becomes an important reference point for the wider development program.
Stockland's current analyst narrative points to A$3.4b in revenue and A$1.1b in earnings by 2029, based on forecasts that the top line will decline 3.7% each year and profit will rise from A$994.0m today, implying an earnings uplift of about A$106m over that period.
Discover why Stockland's fair value suggests a 25% potential upside to its current price, an opportunity that may not remain available for long.
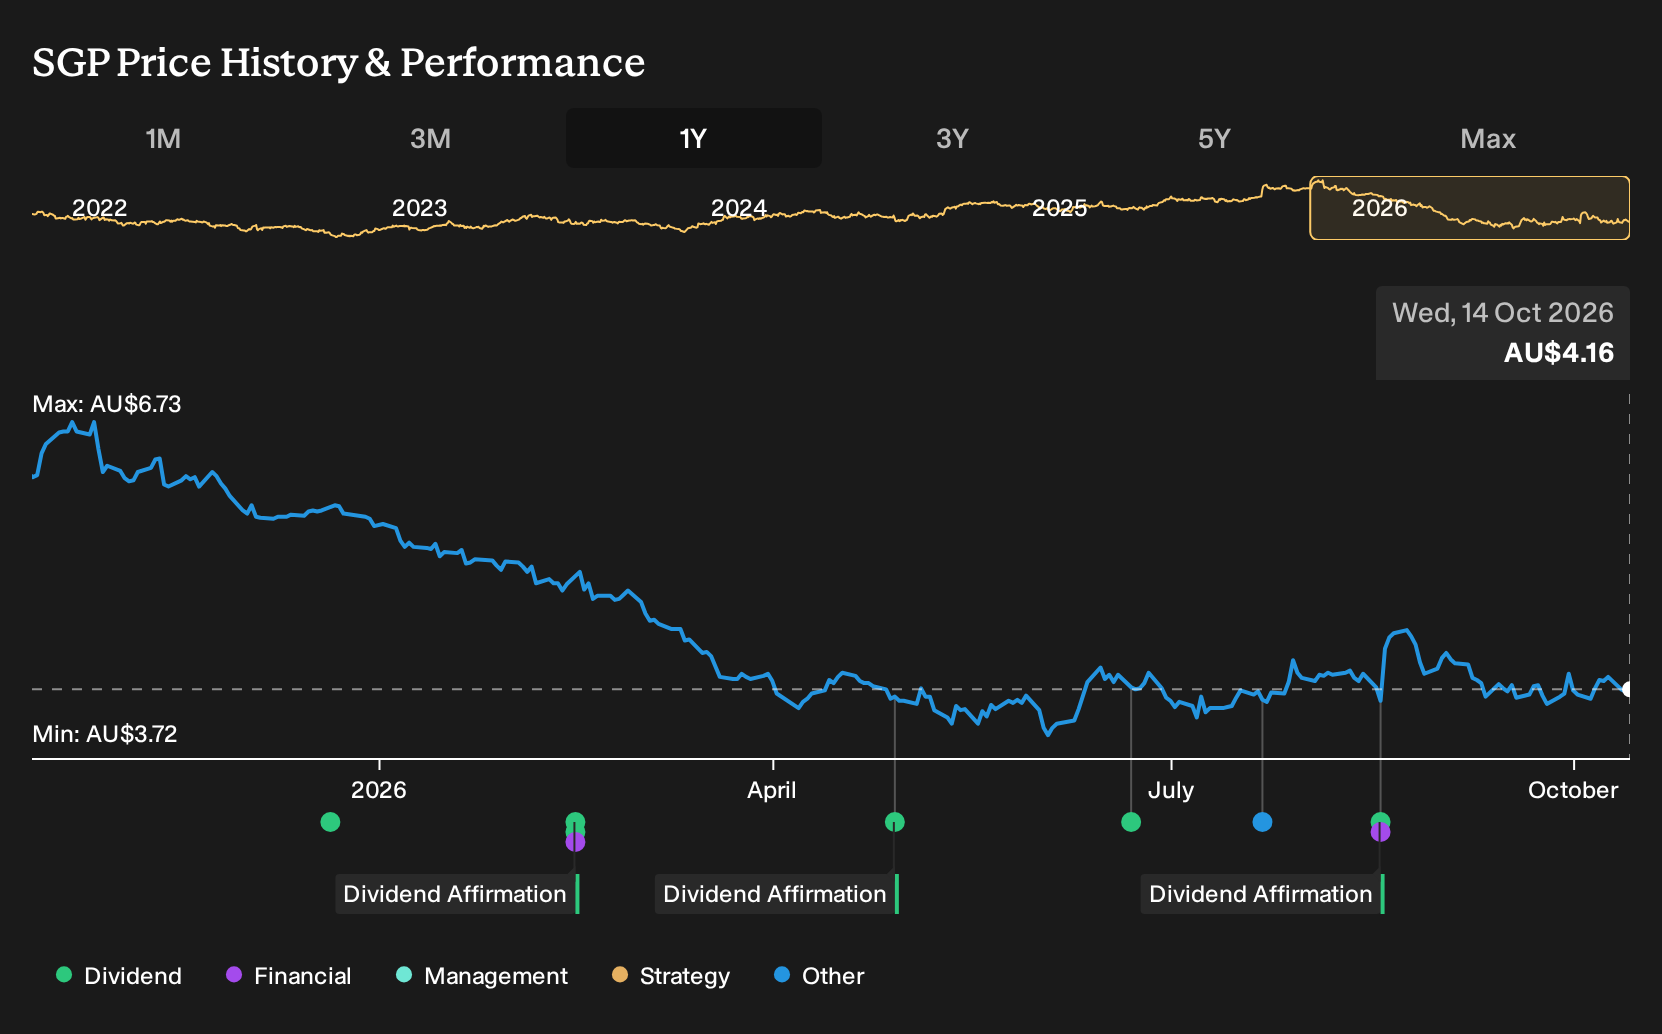
Exploring Other Perspectives
One alternate view puts the timing risk from the EdgeConneX data center build at the center of the Stockland story. The most pessimistic analysts were already working off revenue falling about 24.1% a year and earnings drifting to around A$867.0m by 2029. You can treat this joint venture news as a fresh reason to compare those assumptions with your own.
Explore 3 other Stockland fair value estimates, including one that suggests it could be worth just A$4.59.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Stockland research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Stockland. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Stockland's overall financial health at a glance.
Looking for more Stockland sized investment ideas?
If the Stockland story has sharpened your thinking, use that same lens across the wider market with a few targeted screeners that surface stocks by quality, balance sheet strength, and income potential.
- For investors hunting for stability first and returns second, start with a 6 resilient stocks with low risk scores that already clear a tougher quality and risk bar.
- If resilient finances matter most to you, focus on businesses with stronger funding profiles through a curated list of solid balance sheet and fundamentals (12 results) that you can sort by the metrics that matter to your process.
- For those building an income focused portfolio, there is a helpful 3 dividend fortresses that can help you quickly zero in on higher yielding ideas with room for further research.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com