


SiTime (SITM) is back in focus after fresh analysis linked the company’s silicon timing chips directly to rising AI data center build outs, spotlighting both its specialty role and possible pricing leverage as adoption broadens.
Short term momentum has cooled, with SiTime’s share price down 9.44% over the past day and 21.08% over the last week. This comes even though the year to date share price return sits at 41.89% and the 3 year total shareholder return is around 4.7x. This points to a story where recent volatility contrasts with a strong longer run track record as investors weigh how much of the AI data center opportunity is already reflected in today’s US$524.93 level.
Scan how other AI hardware and data center suppliers are setting up for potential breakouts by reviewing the hand picked 92 AI infrastructure stocks alongside SiTime’s timing chip story.
After a sharp pullback on a stock that is still up strongly this year, SiTime now presents a straightforward question: Does the current price still skew the risk reward balance toward buyers once you compare it with the company’s fundamentals and valuation?
Most Popular Narrative: 39% Undervalued
On the most followed narrative, SiTime’s fair value sits at $864.38 against a last close of $524.93, which leaves a sizable valuation gap that analysts are trying to explain through aggressive growth, expanding margins and heavier AI data center exposure.
Expansion of SiTime's content per device, particularly through customized clocks and clocking systems for AI, networking, and hyperscale platforms, enables increased dollar content per design win, directly supporting top-line growth and improving gross margins as these higher-ASP products become a greater share of sales.
See why 12 investors see SiTime as 39% undervalued.
Result: Fair Value of $864.38 (UNDERVALUED)
Still, that upside story leans heavily on AI data center demand staying robust and on SiTime keeping pace with fast product cycles, where any stumble could quickly challenge the 39% undervalued case.
Find out about the key risks to this SiTime narrative.
Another View on SiTime’s Valuation
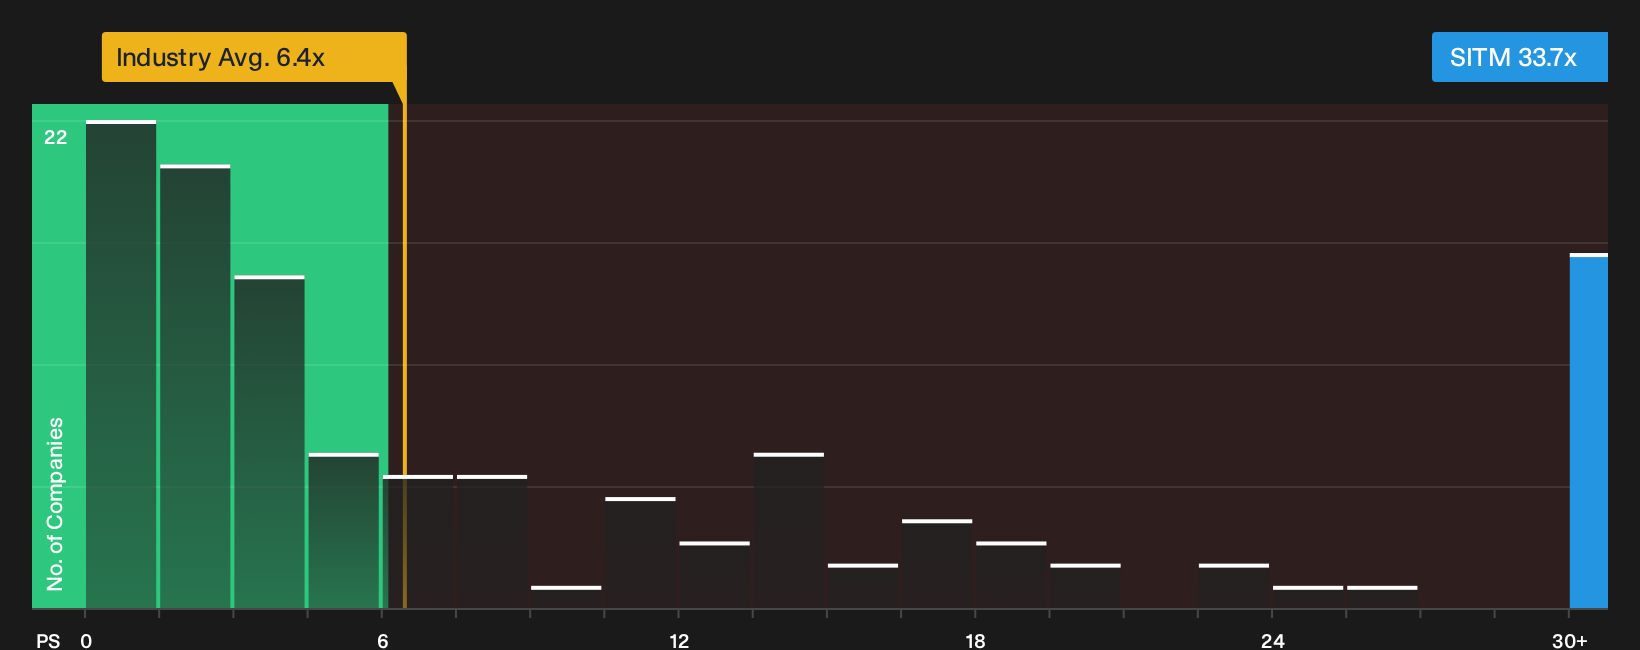
The popular story around SiTime leans on a rich future earnings path, yet current trading tells a very different tale. At about $524.93, the stock is described as expensive on a P/S ratio of 33.7x versus 12.2x for peers and 6.7x for the wider US Semiconductor group, while the fair ratio is estimated at 24.7x. That gap raises a simple question for investors: Is the AI timing chip narrative strong enough to support paying well ahead of both peers and the fair ratio, or does it leave less room if expectations cool?
To see how the current pricing stacks up against the underlying numbers, including that higher P/S ratio, take a closer look at the valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around SiTime can make the story feel split, which is exactly why it helps to review the underlying data, weigh both sides, and then judge the balance of risks and rewards for yourself through the 3 key rewards and 4 important warning signs.
Looking for more ideas beyond SiTime?
If SiTime has sharpened your thinking, do not stop here. Broader context across other opportunities often reveals better fits for your goals and risk tolerance.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) that could anchor your portfolio when sentiment swings.
- Highlight potential mispricings by reviewing the 32 high quality undervalued stocks that combine stronger financial quality with pricing that has not fully caught up.
- Spot opportunities that the crowd may be overlooking by sorting through the 20 high quality undiscovered gems before attention and capital move in.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com