


In October 2026, global markets are navigating a complex landscape marked by mixed performances across major indices and heightened volatility due to geopolitical tensions in the Middle East, fluctuating oil prices, and ongoing inflationary pressures. While the S&P 500 saw gains, small-cap stocks as represented by the Russell 2000 Index experienced a decline amidst these challenges. In this environment, identifying promising small-cap stocks involves looking at companies that demonstrate resilience through strong fundamentals and strategic insider buying, which may indicate confidence from those closest to the business.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Q Technology (Group) | 3.4x | 0.2x | 45.32% | ★★★★★☆ |
| Timbercreek Financial | 16.9x | 9.8x | 37.31% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 6.8x | 0.9x | 39.88% | ★★★★★☆ |
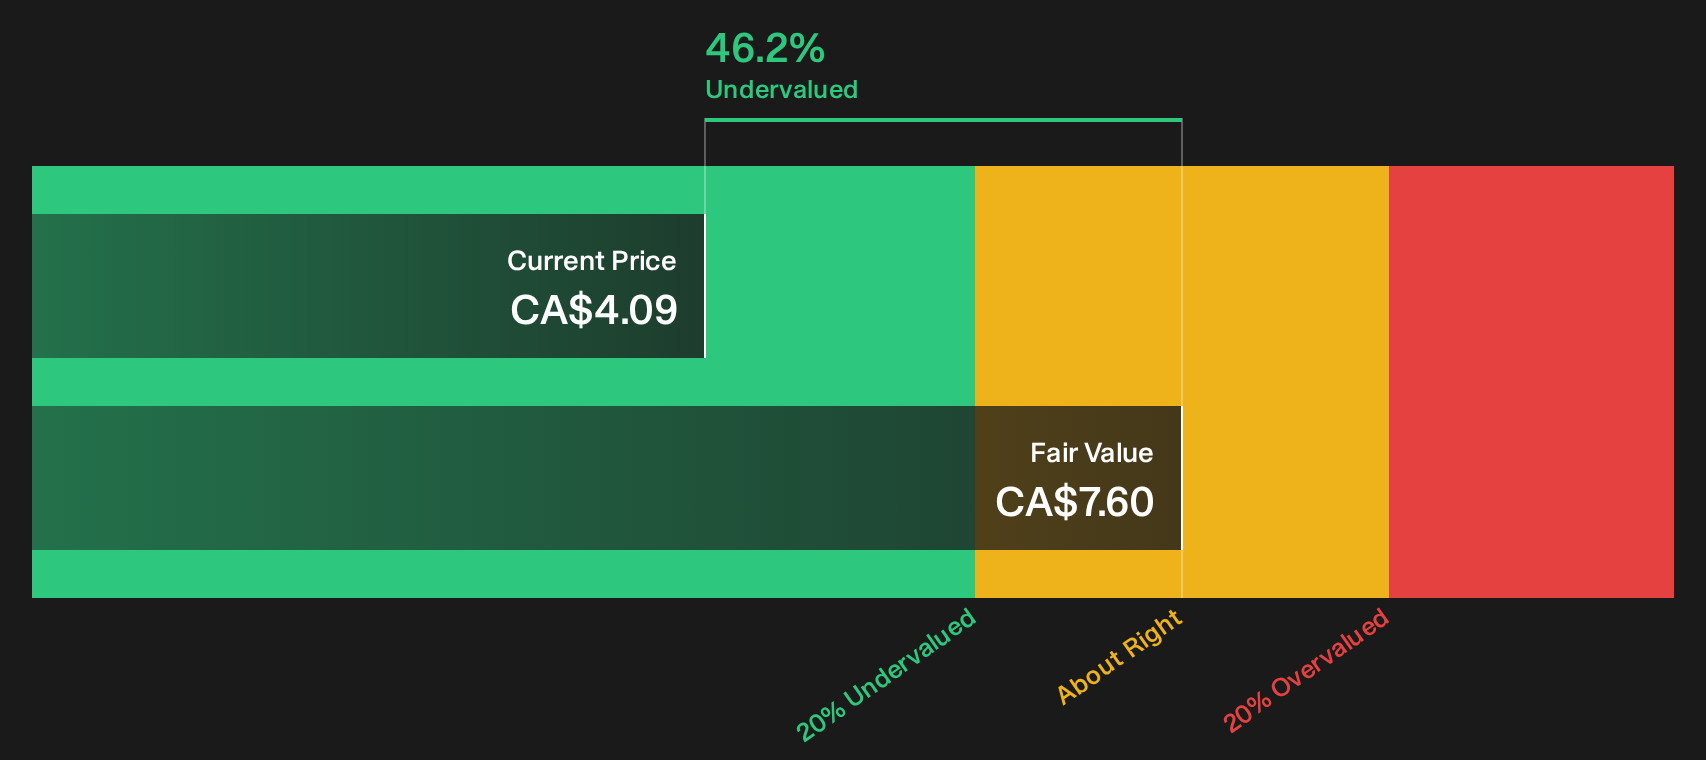
| Diversified Royalty | 25.2x | 10.0x | 46.79% | ★★★★☆☆ |
| Nexus Industrial REIT | 10.0x | 3.0x | 9.19% | ★★★★☆☆ |
| Franchise Brands | 26.8x | 2.0x | 48.17% | ★★★★☆☆ |
| Saniona | 7.3x | 3.2x | 31.98% | ★★★★☆☆ |
| Centurion | 16.6x | 3.2x | 18.26% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -215.83% | ★★★☆☆☆ |
| Linc | 11.9x | 12.3x | 35.56% | ★★★☆☆☆ |
We're going to check out a few of the best picks from our screener tool.
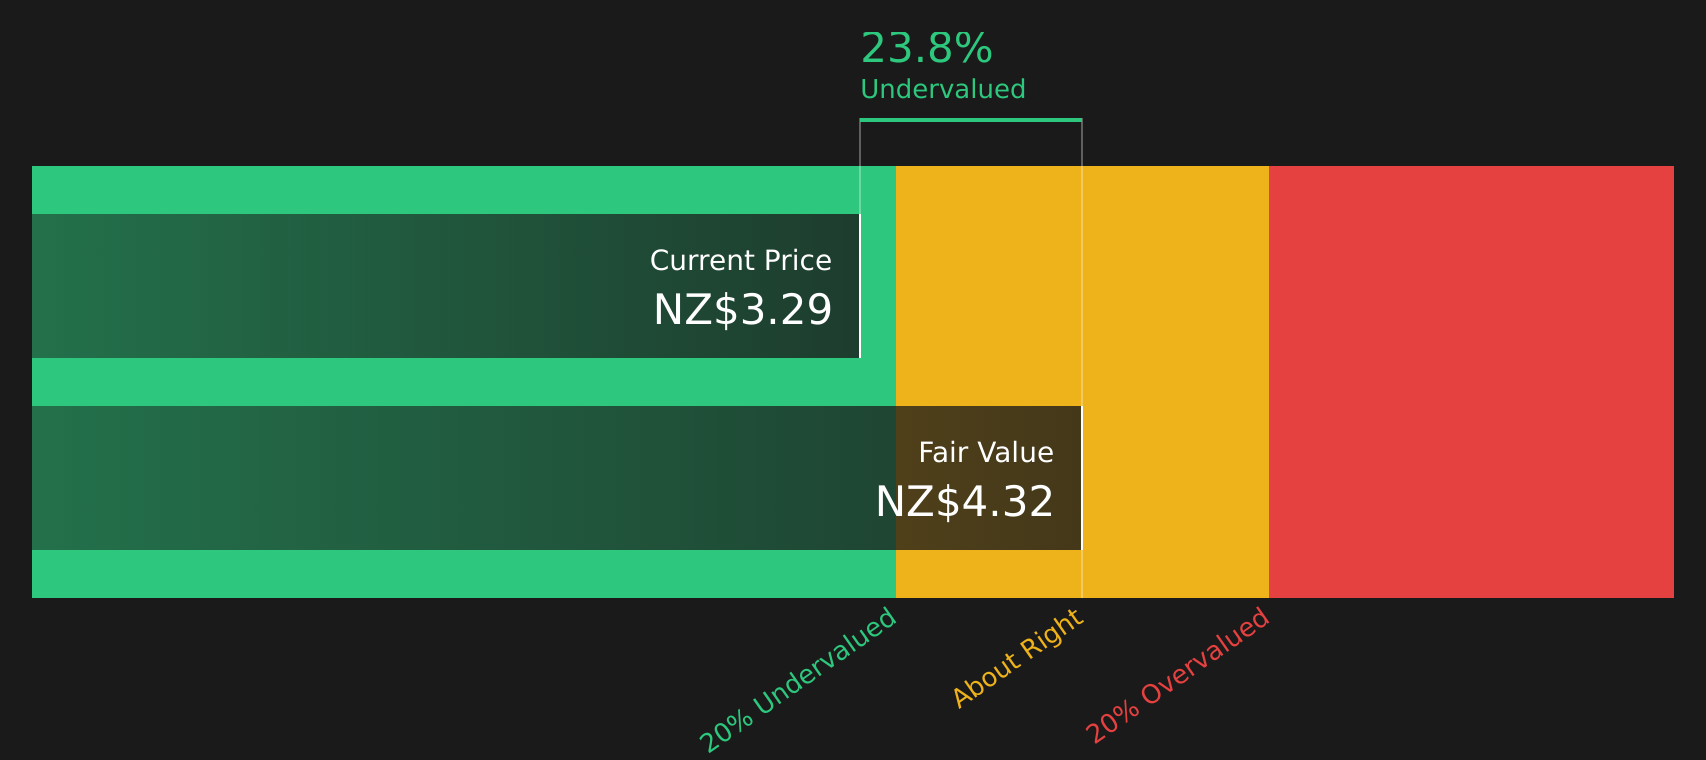
SKY Network Television (NZSE:SKT)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: SKY Network Television operates as a media and entertainment company in New Zealand, offering services such as Sky Box subscriptions, streaming, broadband, and advertising with a market capitalization of NZ$0.53 billion.
Operations: SKY Network Television generates revenue primarily from Sky Box subscriptions (NZ$445.22 million), streaming subscriptions (NZ$128.28 million), and advertising (NZ$131.72 million). The company's cost of goods sold significantly impacts its gross profit, which was NZ$212.55 million as of the latest data point, resulting in a gross profit margin of 25.77%. Operating expenses and non-operating expenses further affect the net income, with a recent net income margin recorded at 7.20%.
PE: 8.3x
Sky Network Television, a smaller company in the broadcasting industry, has shown signs of being undervalued. Despite earnings forecasted to decline by 10.9% annually over the next three years, recent insider confidence is evident with Keith Smith purchasing 100,000 shares for NZ$310,874 in August 2026. The company reported significant growth with sales reaching NZ$824.85 million and net income climbing to NZ$59.38 million for fiscal year ending June 2026. Additionally, they increased their dividend guidance for fiscal year 2027 to at least NZ$0.35 per share from last year's NZ$0.32 per share payment, indicating a commitment to shareholder returns amidst challenging conditions due to reliance on external borrowing as funding source.
Diversified Royalty (TSX:DIV)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Diversified Royalty is a multi-royalty corporation that acquires top-line royalties from well-managed businesses and has a market cap of approximately CA$0.53 billion.
Operations: The company generates revenue primarily through royalty streams, with a gross profit margin reaching 100% in recent periods. Operating expenses have shown an increase, reaching CA$11.09 million by mid-2026. Net income margins have displayed variability, peaking at 66.58% in mid-2022 and later decreasing to 39.71% by mid-2026, indicating fluctuations in profitability despite consistent revenue growth over time.
PE: 25.2x
Diversified Royalty, a smaller company in its sector, has recently attracted attention due to insider confidence. In September 2026, an insider purchased 100,000 shares for C$399,000. Despite a decrease in net income from C$9.02 million to C$3.14 million year-over-year for Q2 2026, the company maintains steady revenue growth and regular dividends of C$0.02375 per share monthly through October 2026. While liabilities are primarily funded through external borrowing—a riskier approach—earnings are projected to grow annually by over 33%.
- Navigate through the intricacies of Diversified Royalty with our comprehensive valuation report here.
Gain insights into Diversified Royalty's past trends and performance with our Past report.
Vital Infrastructure Property Trust (TSX:VITL.UN)
Simply Wall St Value Rating: ★★★★★☆
Overview: Vital Infrastructure Property Trust operates in the healthcare real estate sector with a focus on managing and investing in healthcare-related properties, and it has a market cap of approximately CA$1.06 billion.
Operations: The company has experienced fluctuations in its net income margin, with a recent shift to negative values, reaching -20.83% by June 2026. Despite this, it has maintained a relatively stable gross profit margin of approximately 75.19%. Operating expenses have varied over time but were recorded at CA$56.09 million in the latest period. The non-operating expenses have significantly impacted the company's net income, contributing to recent losses.
PE: -15.7x
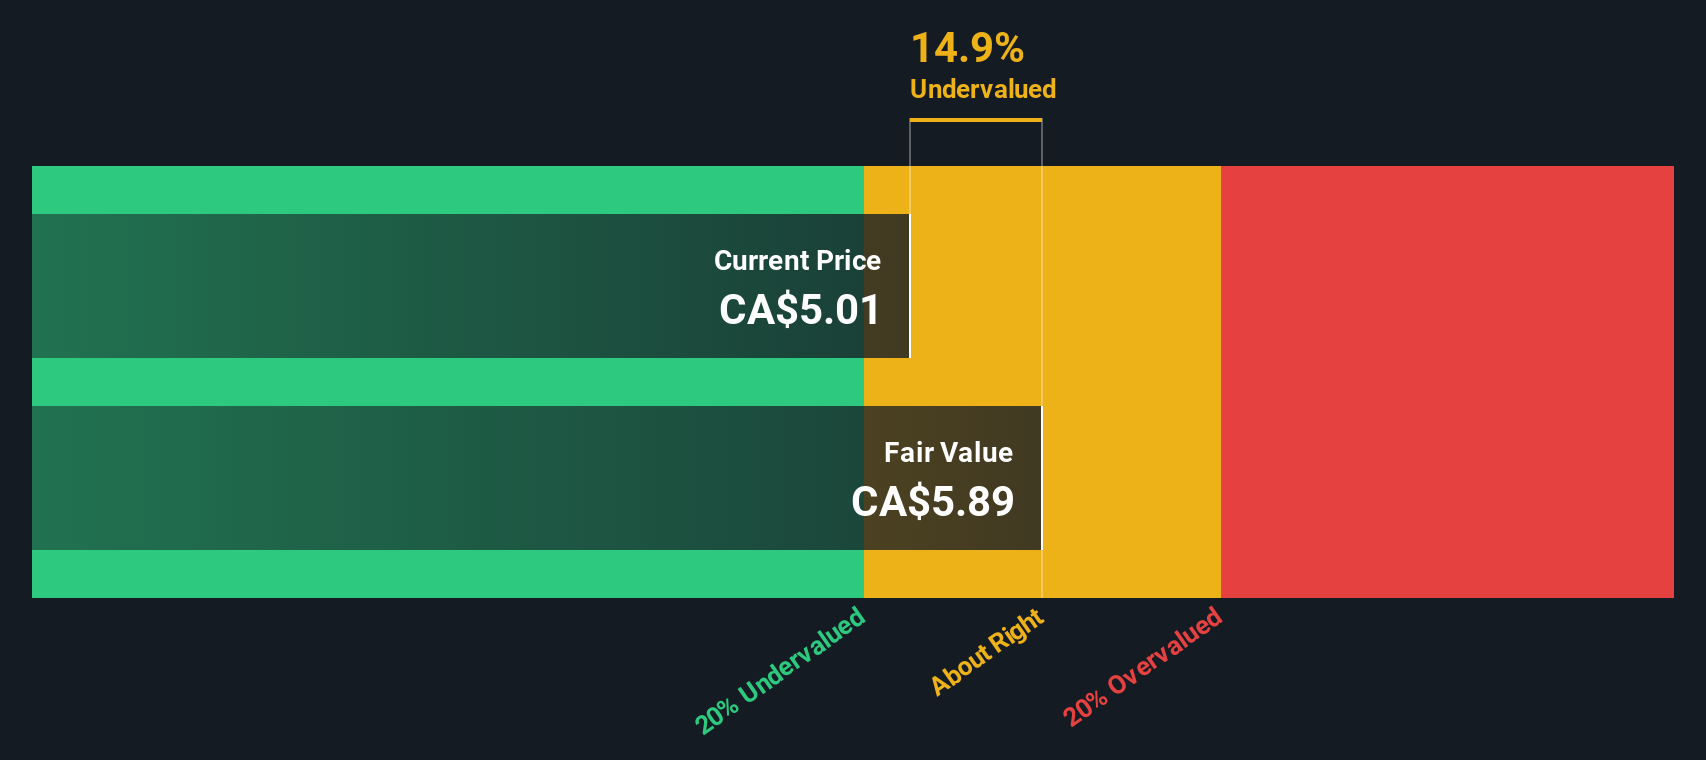
Vital Infrastructure Property Trust, a smaller company in the property trust sector, recently completed a CAD 300 million debenture offering to repay higher-cost debt and support corporate initiatives. Despite the challenging financials, with net income dropping significantly from last year, insider confidence is evident through recent share purchases. The acquisition of East New York Health Hub highlights their strategic focus on high-quality assets with stable tenants. Earnings are projected to grow by 154% annually, suggesting potential for future growth amidst current financial restructuring efforts.
Seize The Opportunity
- Discover the full array of 123 Undervalued Global Small Caps With Insider Buying right here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Unlock the power of informed investing with Simply Wall St, your free guide to navigating stock markets worldwide.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com