


Regeneron Pharmaceuticals has delivered solid long term gains for shareholders over the past five years, and a fresh run of clinical and partnership news has pushed investors to reassess what they are actually paying for its earnings today. With the stock recently closing at US$778.36, the key issue is how that price lines up with the profits the business is currently generating.
- Over the past 5 years the share price return of 39.6% puts real weight on the question of whether Regeneron's earnings justify the market's patience through shorter term ups and downs.
- Recent trial successes in rare disease and oncology, plus an expanded immunology alliance with Sanofi that brings US$1b upfront and large milestone potential, can influence expectations for future profitability and the timing of cash flows that underpin earnings based valuation work.
- Your read on Regeneron Pharmaceuticals is one view; the desks covering it have another. See what analysts think Regeneron Pharmaceuticals's shares could be worth.
The stock's next move may depend on whether Regeneron's current earnings profile and outlook make its present share price look well supported when set against those profits.
To see how Regeneron Pharmaceuticals compares with other potential ideas in terms of earnings power and pricing, line it up next to the 32 high quality undervalued stocks.
Is Regeneron Pharmaceuticals a Bargain on Earnings?
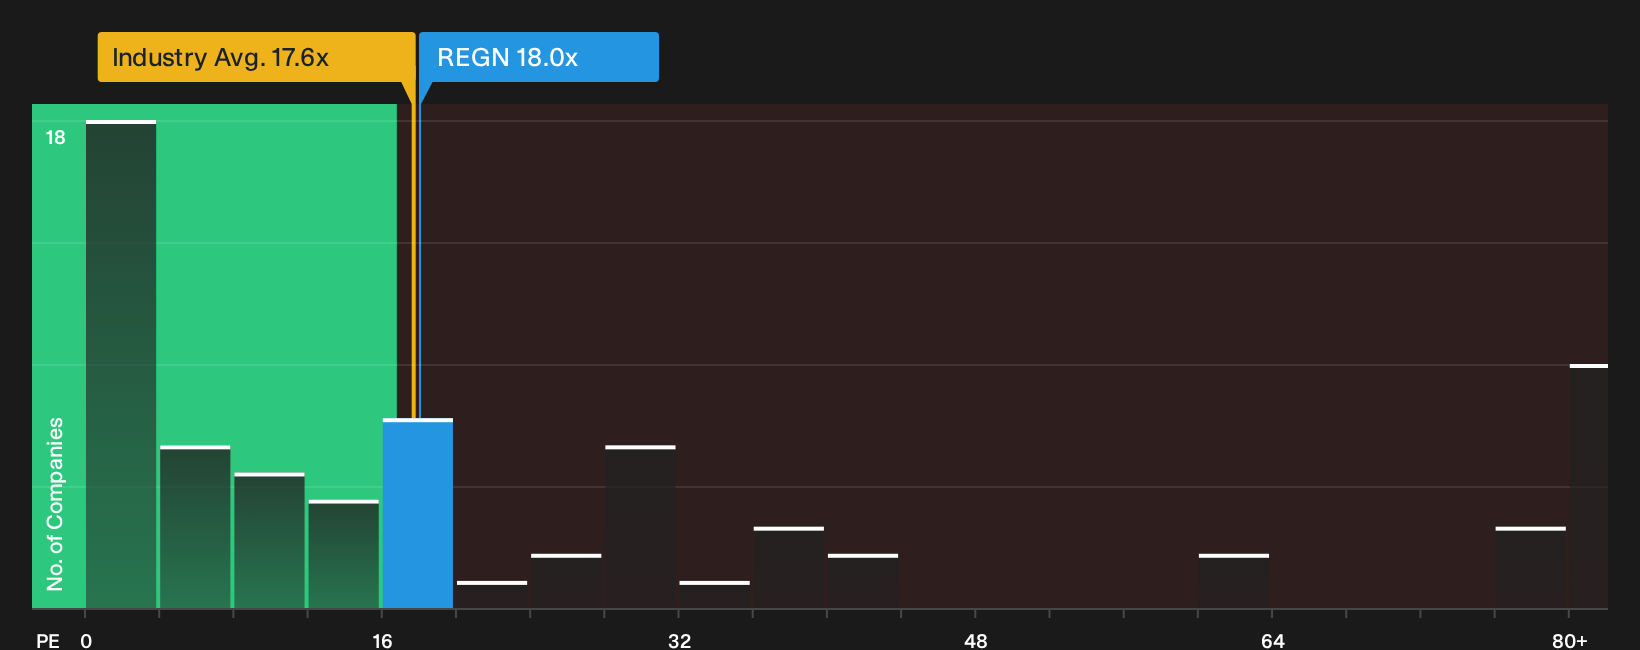
The P/E ratio fits Regeneron Pharmaceuticals because earnings remain a key lens investors use to judge mature drug businesses with established products and a visible profit base. On this measure, the stock trades at about 18.0x earnings, which is slightly above the broader biotech sector average of roughly 17.6x but sits well below a peer group closer to 28.5x. That mix suggests investors pay a modest premium to the typical biotech producer, yet the share price does not mirror the richer multiples seen across similar large listed peers.
Because the current P/E is lower than the more tailored fair multiple that accounts for Regeneron Pharmaceuticals' margins, risk profile and scale, the shares screen as undervalued on this earnings lens. The expanded immunology alliance with Sanofi, which brings US$1b upfront plus potential milestones, has sharpened the spotlight on how much of Regeneron's partnership and pipeline story is already captured in that multiple. The current discount points to some of that upside not being fully reflected in the price. Explore the numbers behind Regeneron Pharmaceuticals's P/E valuation.
The Regeneron Pharmaceuticals Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St's Community page pick up where the Regeneron Pharmaceuticals P/E puzzle leaves off by spelling out what kind of future growth, profitability and earnings profile would need to play out for the current share price to look either generous or conservative. Each one treats Regeneron Pharmaceuticals' implied fair value as a thesis about the business that can be tracked over time, rather than a single frozen snapshot.
Community views on Regeneron Pharmaceuticals split between those who see a discounted multi franchise story and others who think the current price already bakes in a lot of that potential.
Bull case: 9% undervalued
"Current valuation implies the market is heavily discounting the durability of Dupixent, the conversion of the retinal business to EYLEA HD, and the potential from the late stage pipeline and expanded Sanofi collaboration…"
Discover why this Narrative puts Regeneron Pharmaceuticals at 9% undervalued.
Bear case: 7% overvalued
"Bearish analysts expect Regeneron Pharmaceuticals to remain exposed to concentrated product risk as EYLEA faces biosimilar competition and Dupixent growth moderates against tougher comparisons in 2026…"
Explore why this Narrative puts Regeneron Pharmaceuticals at 7% overvalued.
Regeneron Pharmaceuticals: why the current share price is only half the story
Valuation work shows what you pay today, while the set of professional projections a few years out hints at what others think Regeneron Pharmaceuticals might be earning when you get there. Explore where analysts expect Regeneron Pharmaceuticals to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com