


AI chips are no longer just a story about future potential. TSMC has reported record Q3 revenue and net income for the sixth straight quarter, with high performance computing and advanced nodes carrying most of the load. That kind of momentum is pulling a select group of semiconductor heavyweights into the spotlight and raising fear of missing out for investors. This article walks through three stocks exposed to that same AI driven trend and explains why each one may deserve a closer look now.
The three companies below are just a sample of the AI semiconductor leaders that fit this theme. The full screen turned up 97 more large chipmakers with equally compelling AI related stories that are not covered here.
If you want to cut straight to the broader opportunity set, use the AI Semiconductor Leaders screener to identify, compare, and analyze the highest conviction ideas from the full list.
ACM Research (Shanghai) (SHSE:688082)
ACM Research (Shanghai) plugs directly into the AI Semiconductor Leaders theme because its tools sit inside the fabs turning wafers into AI and high performance chips. This gives investors exposure to that spending cycle rather than to any single GPU or accelerator design.
ACM Research (Shanghai) develops and sells semiconductor manufacturing equipment such as cleaning, plating, furnace, PECVD and stress free polishing tools, generating CN¥7.2b from semiconductor equipment and services, and the stock carries a market value of roughly CN¥125.8b.
"The company is executing on a robust expansion strategy, notably building new high-capacity R&D and production centers in both China (Lingang) and the US (Oregon). This will enable greater scale, improve customer proximity, and support global market penetration, potentially strengthening future topline revenue and improving net margins through improved operational efficiency."
What happens if a single pressure on wafer fab equipment demand shifts just as this larger footprint starts to feed through to earnings?
That kind of timing risk is exactly what the full narrative for ACM Research (Shanghai) unpacks, including how ACM Research (Shanghai) could still compound value if wafer demand stalls temporarily.

NAURA Technology Group (SZSE:002371)
NAURA Technology Group is a large Beijing based semiconductor equipment supplier in the AI Semiconductor Leaders theme, supplying etch, deposition and other wafer tools that can be used in advanced chip production. Around CN¥40.7b of revenue comes from electronic process equipment, CN¥2.6b from electronic components, and the stock carries a market value near CN¥425.8b.
NAURA Technology Group helps equip fabs that serve AI and data-heavy workloads, with a forecast P/E of 77.9x and revenue expected to grow 26.6% a year. Investor interest may depend on whether these growth assumptions hold up if there is any unexpected pressure on margins or changes in capital expenditure plans.
If those assumptions are even partly off, the analyst forecasts for NAURA Technology Group lays out where expectations are accelerating and where sentiment could flip the fastest.

King Yuan Electronics (TWSE:2449)
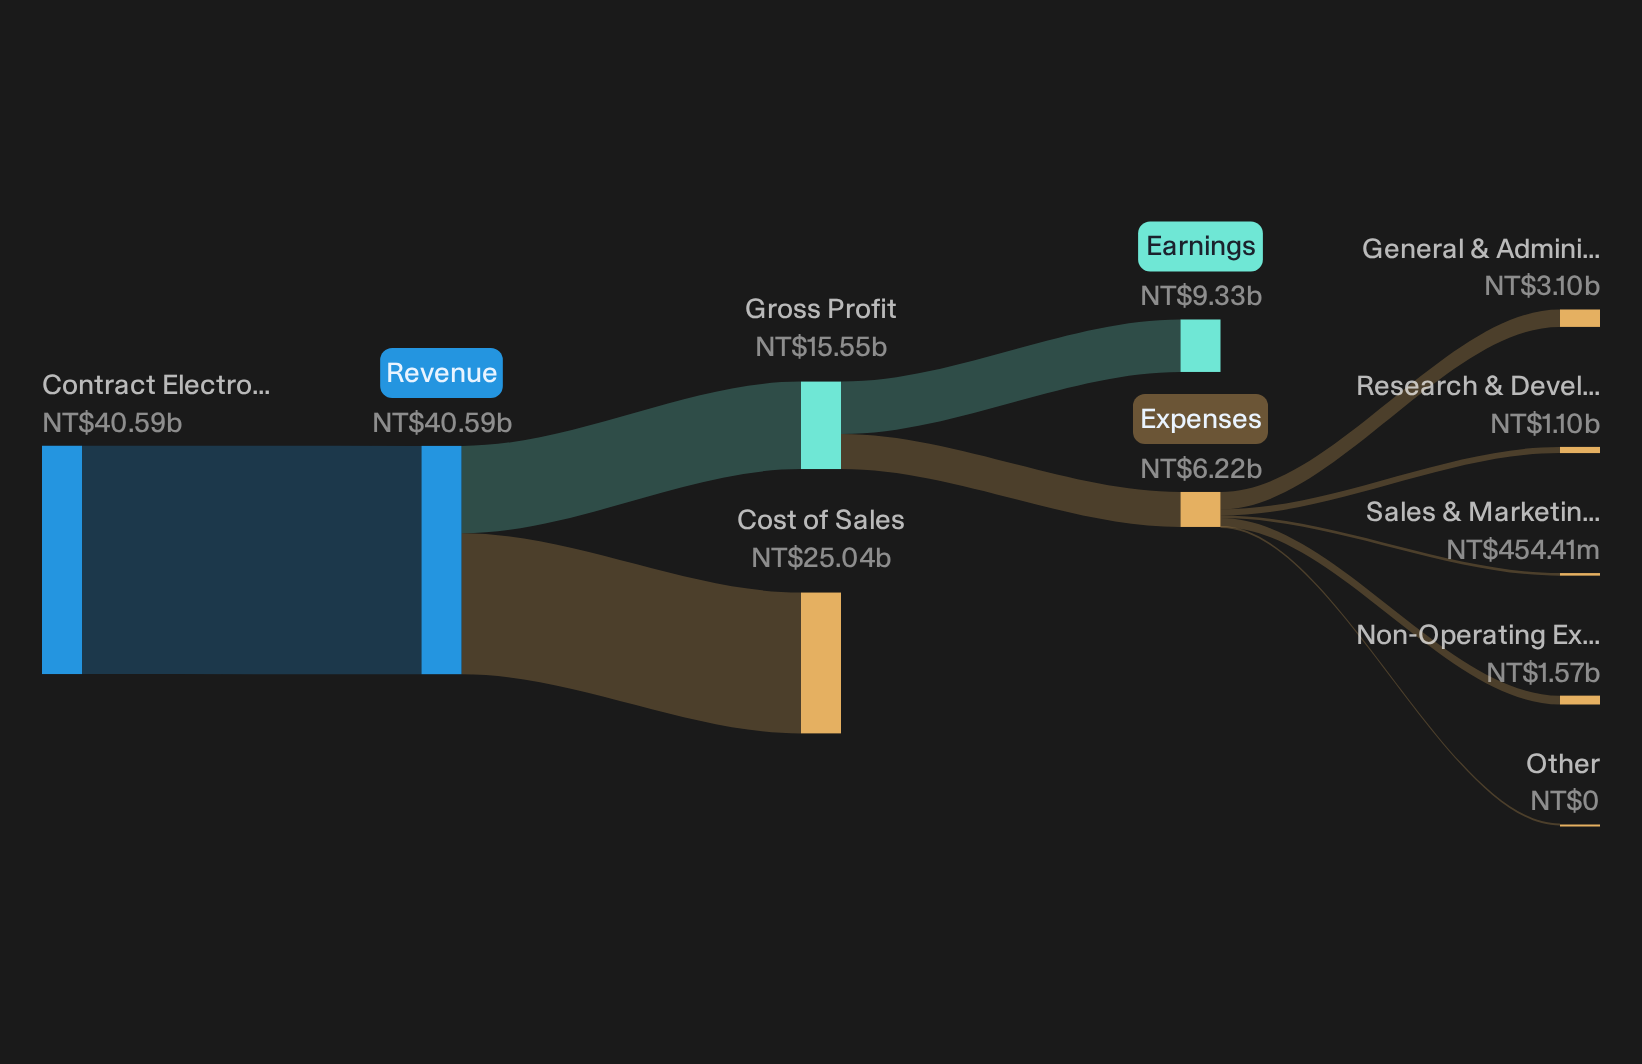
King Yuan Electronics runs IC testing and assembly for chips used in AI and high performance computing, giving investors exposure to AI semiconductor production volumes. The business generates about NT$40.6b from contract electronics manufacturing services and the stock is valued around NT$380.7b.
King Yuan Electronics sits in the AI Semiconductor Leaders theme as a pure-play tester and packager for advanced chips, where throughput scales directly with wafer volumes flowing out of major fabs. Recent earnings strength tied to AI and datacenter demand puts the focus on how one quiet shift in test mix and pricing could reshape margins just when expectations are highest.
That margin shift is the real story, and the analysis report for King Yuan Electronics shows where King Yuan Electronics profits could decouple from simple wafer volume headlines.
Seeking Fresh Alternatives Before They Fly
New themes move fast. Breakout areas today can get crowded quickly, and the best entry points drop away while everyone is still focused on yesterday's winners. Scan these fresh ideas before the crowd and consider them while they are still emerging.
- Spot resilient payers while yields are still climbing by running the 216 dividend fortresses before income investors focus on the same high payout opportunities.
- Track where capital is quietly shifting by checking the 195 high quality undervalued stocks while valuations still look reasonable and momentum is only starting to build.
- Focus on potential infrastructure drivers early by reviewing the 43 power grid technology and infrastructure stocks while these grid upgrades remain less widely followed for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com