


Rayonier (RYN) has drawn fresh attention after its recent share price moved to $18.65, with the timberland REIT trailing over the past month and past 3 months.
For context, Rayonier shares have been under pressure for a while. The 30 day share price return is down 7.9% and the year to date share price return is down 13.7%, while the 1 year total shareholder return has declined 14.0% and the 5 year total shareholder return is down 30.7%. This points to fading momentum rather than a short term wobble.
Scan beyond Rayonier's pullback and line up other real estate and infrastructure plays using our curated list of list of solid balance sheet and fundamentals (25 results).
Rayonier now trades at $18.65 after a steady slide, which puts a simple choice in front of you: step in at this level or wait for an even cheaper entry as the valuation story unfolds next.
Most Popular Narrative: 28% Undervalued
Rayonier is being framed as worth around $26 a share using a 7.97% discount rate, compared with the recent $18.65 close. This puts the focus firmly on how far the current price sits below that narrative fair value rather than on short term price swings.
Expansion of land based solutions, with about 80,000 acres under solar option, roughly 154,000 acres under carbon capture lease and recent solar transactions around US$10,000 per acre, positions Rayonier to grow recurring option, lease and sale income that is less tied to timber cycles and that can support both revenue and EBITDA mix over time.
See why 22 investors see Rayonier as 28% undervalued.
Result: Fair Value of $26 (UNDERVALUED)
Still, the Rayonier story can be knocked off course if pulpwood pricing pressure lingers, or if those rural, development and solar land pipelines stall.
Find out about the key risks to this Rayonier narrative.
Another View: Rayonier On Earnings Multiples
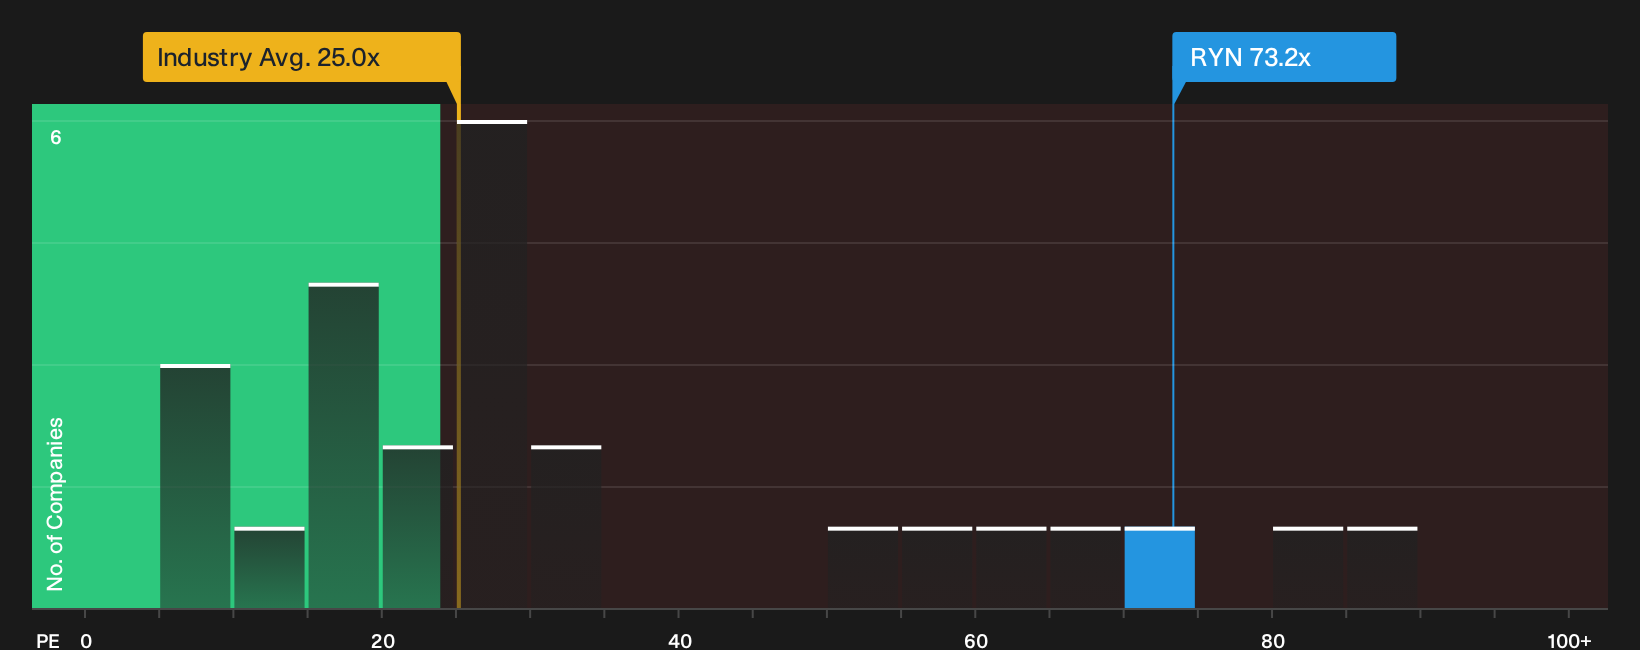
That 28% undervalued fair value story looks very different once you evaluate Rayonier through its earnings multiple. The stock trades on a P/E of 73.2x compared with about 25x for the North American Specialized REITs group and roughly 18.9x for peers.
The fair ratio for Rayonier is estimated at 64.7x, which is already high. Trading above that level points to less room for error if the upbeat earnings path or land conversion plans slip. The question is simple: are you being paid enough to carry that valuation risk?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Rayonier's value story. Consider acting while sentiment is split and pressure test the thesis yourself with the 2 key rewards and 4 important warning signs.
Looking for more ideas beyond Rayonier?
If Rayonier has you rethinking where to put fresh capital, use that momentum. Broaden your watchlist now so you are not reacting after the next move.
- Target quality at a discount by scanning companies on our 32 high quality undervalued stocks that pair stronger fundamentals with what may be more modest expectations baked into the share price.
- Prioritise resilience by checking the 32 resilient stocks with low risk scores that screens for businesses with sturdier financial profiles and potentially steadier risk scores.
- Spot future contenders early by reviewing the 20 high quality undiscovered gems which highlights underfollowed stocks with stronger looking fundamentals before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com